Weekly update #157
Builders Fintech Funding Index: 143 (last full week, week of 26 Oct). 30 equity rounds recorded, against a 12week average of 21. Median disclosed USD round: index 173. Our round coverage expanded in September 2026, so the Index overstates activity until midDecember. Full reading
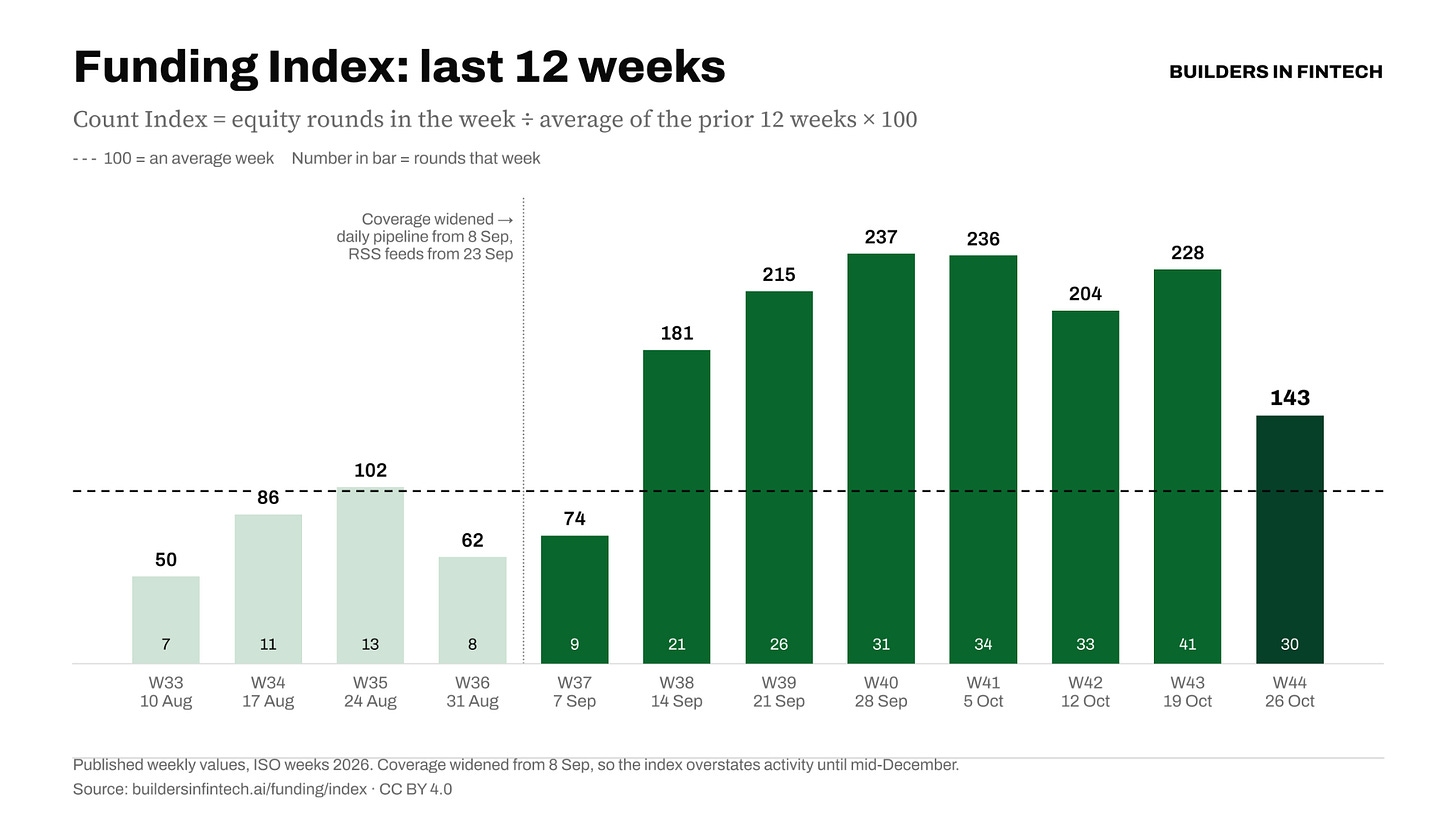
Builders Fintech Funding Index: 143 (last full week, week of 26 Oct). 30 equity rounds recorded, against a 12-week average of 21. Median disclosed USD round: index 173. Our round coverage expanded in September 2026, so the Index overstates activity until mid-December. Full reading
Revolut closed a funding round at a $115B valuation, CD&R and GTCR are weighing a $40B take-private of Global Payments, and Hoxton Wealth took $135M from Aspirity Partners, its first outside funding since 2018. Below: McKinsey & Company‘s Global Banking Annual Review 2026 ($1.3T of net income, fintechs at 17% of the top banks’ and fintechs’ combined revenue, AI adoption seven times faster than digital banking), the week’s rounds and funds, and three managers raising now.
Builders in Fintech: No new episode this week (we release bi-weekly), but you can always recover the last one with Andrej Benčić, co-founder and CEO of Tenderly. You can check the last episodehere on YouTube orhere on Spotify.
All episodes: YouTube · Spotify · Apple Podcasts · Amazon. Founders and VCs who want to come on the show: message me on LinkedIn.
Builders in Fintech Daily: yesterday’s rounds and news, every weekday at 8:00. Subscribe here.
Can AI agents use fintech products? We checked.
This week we published the first Agent-Ready report. We scored 1,317 fintech products on five things an AI agent needs: to find the product, read its API docs, test it, connect to it, and see who runs it.
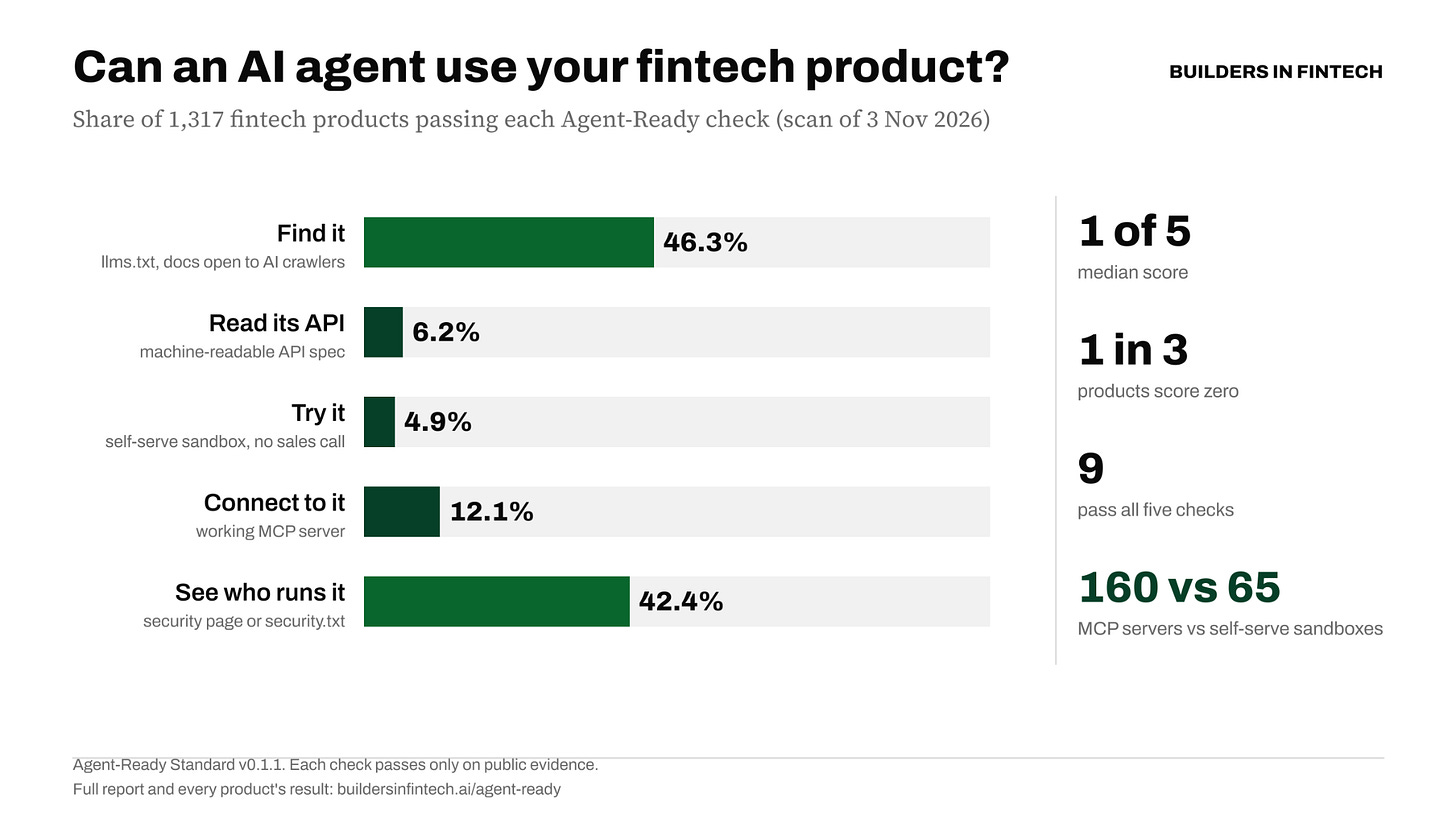
The short version: nine products passed all five checks (Alchemy, Alpaca, Blockdaemon, Chift, Jithox, Kintsugi, PayMongo, Socure and Stripe). A third passed none. The biggest gap is access: only 6% let an agent read the API docs without signing up, and 5% let it test without a sales call.
Every product’s score, with the evidence behind it, is now on its page on the site. If your product is in the database and you think we missed something, there’s a correction link on the page.
Read the report: buildersinfintech.ai/news/agent-ready-report-2026 · See the leaders: buildersinfintech.ai/agent-ready
The report: banks at the customer tipping point
McKinsey & Company, Global Banking Annual Review 2026: Precision with speed. The Financial Services Practice’s preview of its annual review: 2025 results, a new regional map of banking models, and four forces moving the customer relationship away from incumbents. Here my main takeaways:
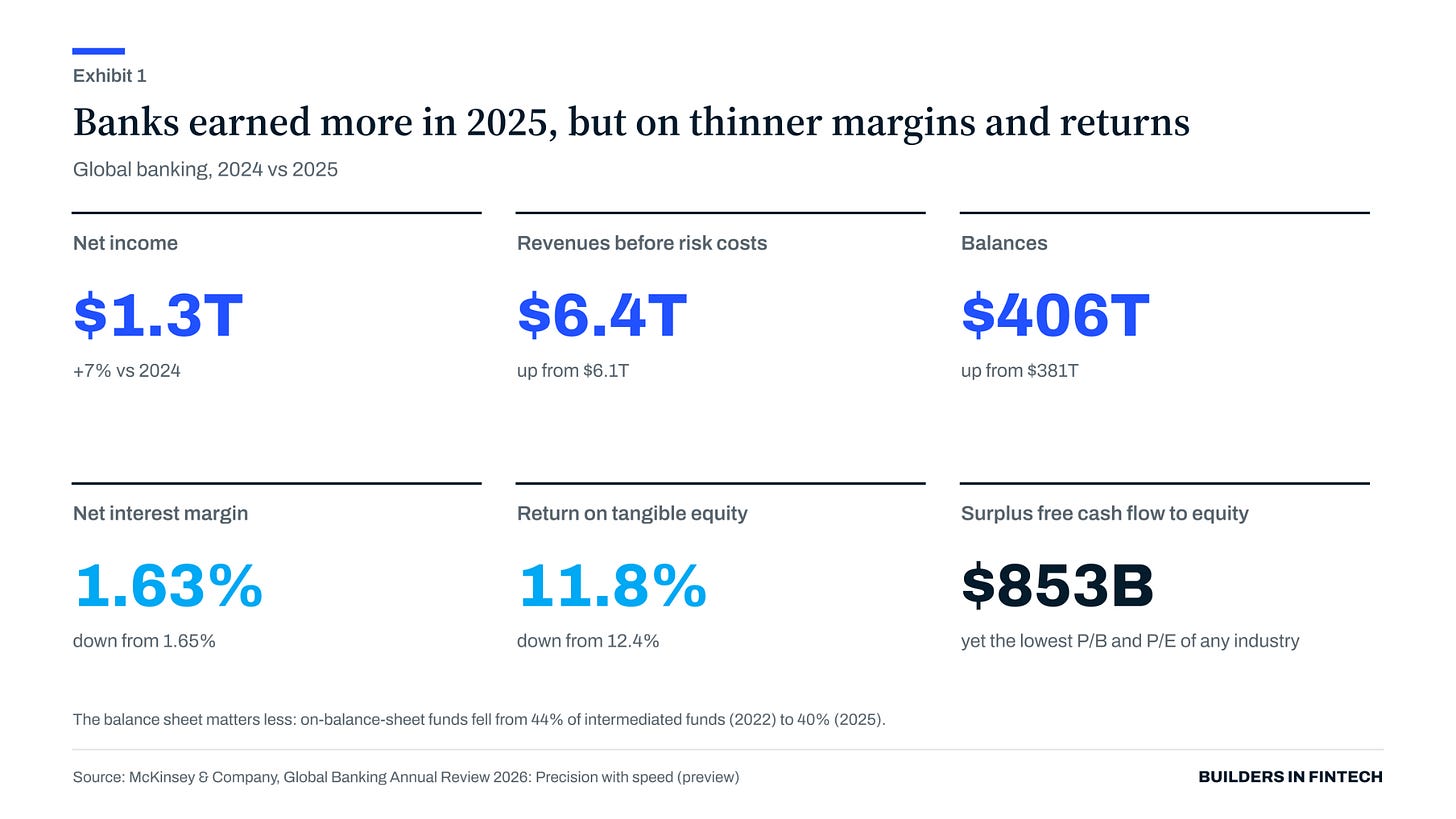
The numbers. Global banking net income rose 7% to $1.3T in 2025. Revenues before risk costs reached $6.4T, from $6.1T, on balances of $406T, from $381T. Net interest margin slipped from 1.65% to 1.63%, return on tangible equity from 12.4% to 11.8%. Banks still posted $853B of surplus free cash flow to equity, yet trade at the lowest price-to-book and price-to-earnings of any industry. The balance sheet matters less: on-balance-sheet funds fell from 44% of intermediated funds in 2022 to 40% in 2025, and transaction banking plus distribution now bring 47% of revenues and 57% of profits.
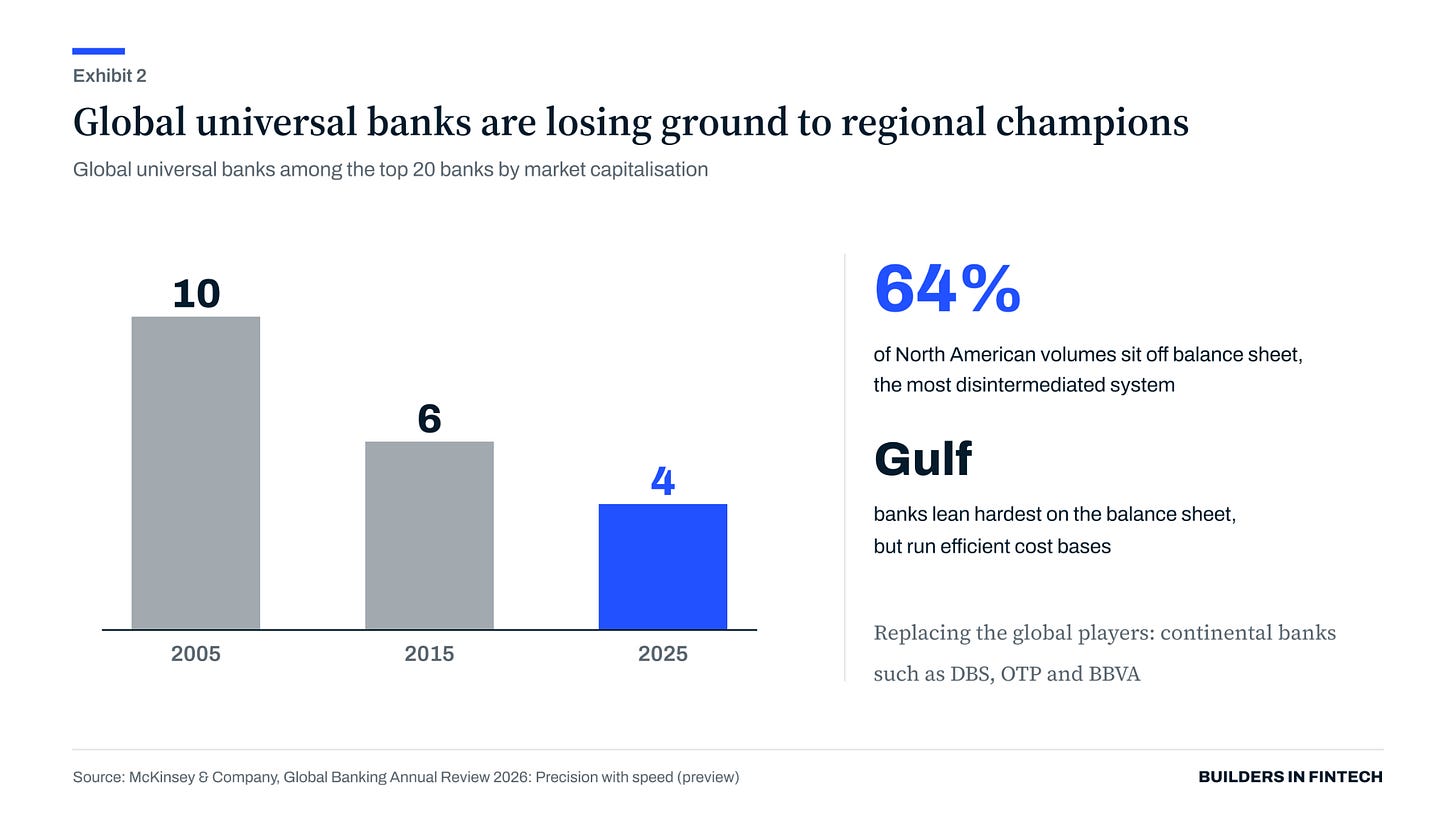
The regional map. Business models are diverging by region. North America is the most disintermediated system, at 64% of volumes off balance sheet; Gulf banks lean hardest on the balance sheet but run efficient cost bases. Global universal banks are retreating: four of the top 20 banks by market capitalisation in 2025, against ten in 2005 and six in 2015, with continental players such as DBS, OTP and BBVA replacing them.
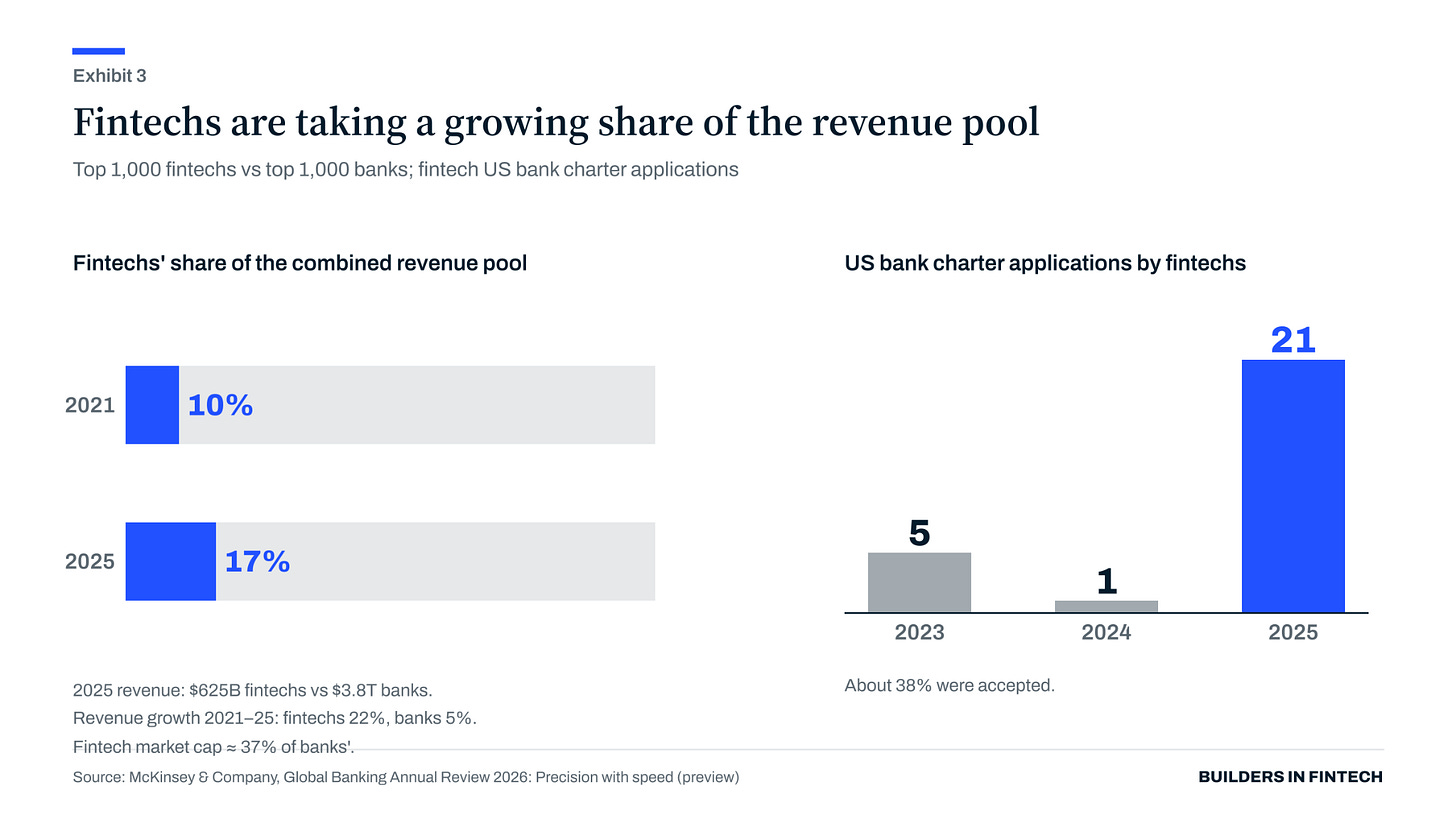
Fintechs. The top 1,000 fintechs generated $625B of revenue against $3.8T for the top 1,000 banks. Fintech revenue grew 22% from 2021 to 2025, bank revenue 5%, lifting fintechs’ share of the combined pool from 10% to 17%. Their market capitalisation equals about 37% of the banks’. Fintechs filed 21 US bank charter applications in 2025, against one in 2024 and five in 2023; about 38% were accepted.
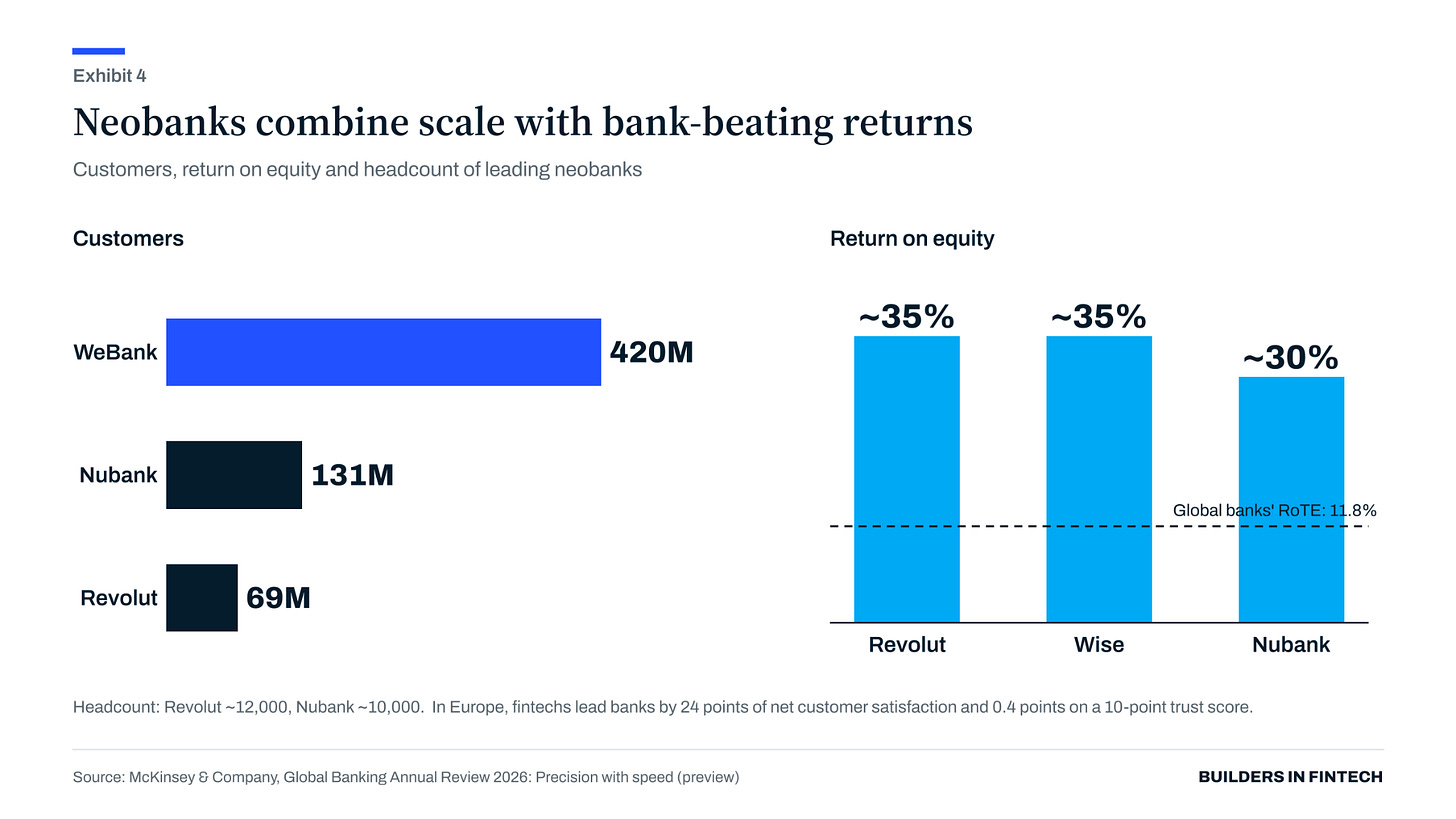
Neobanks. Revolut has 69M customers, Nubank 131M and WeBank 420M. Return on equity is about 30% at Nubank and about 35% at Revolut and Wise, with Revolut and Nubank running on roughly 12,000 and 10,000 employees. In Europe, fintechs lead banks by 24 points of net customer satisfaction and 0.4 points on a 10-point trust score.
Agents and stablecoins. Gen AI reached 45% of US working-age adults in two years; digital banking took 15. Net interest income is about 60% of retail bank revenue, and agents that sweep idle cash to higher yields put that spread at risk. The report puts stablecoin circulation at roughly $300B, supporting about $400B of real payment activity in 2025, small today but a direct pressure on deposits.
The read. The report’s argument is that incumbents lost their grace period: their most valuable customers were also their slowest adopters, and AI adoption does not follow that age curve. The strongest evidence is on the other side of the ledger, where Revolut’s $115B round puts a neobank above most of the banks it competes with. Positioned well: neobanks with banking licences, and banks that can ship in quarters rather than years. Exposed: deposit-heavy banks in markets where customers already trust a fintech more than their own bank. Watch the licence queue, since the 21 fintech charter applications will decide how much of this stays outside the regulated perimeter.
The week in six stories
- Revolut closes a funding round at a $115B valuation. Glade Brook Capital Partners is named as lead. The valuation compares with $75B in November 2025. [verify: press describes a secondary share sale; no source confirms Glade Brook as lead of the completed deal]
- CD&R and GTCR weigh a $40B take-private of Global Payments. The Financial Times reported that GTCR, the largest shareholder, would roll a stake of about $10B into the bid. The $40B includes debt; talks are at an early stage.
- Block agrees in principle to pay $764M to settle the DOJ anti-money-laundering probe. Block’s 10-Q confirms an agreement in principle on a three-year deferred prosecution agreement. [verify: the $764M figure is not in the filing or in press found]
- Hoxton Wealth secures $135M from Aspirity Partners. It is the first outside capital since the firm’s 2018 founding. Hoxton manages more than $5B in assets; completion is subject to regulatory approvals.
- Revel closes a round of more than €120M led by Openbank. [verify: no source found for the amount or the lead]
- Pliant raises $80M as Citi Ventures joins the cap table. The Berlin-based corporate card and payments company raised $40M in April 2025.
Also: tZERO to go public through a $350M pre-money SPAC deal with FG Imperii; UMB Financial to buy El Dorado Savings Bank for about $506M; Bilt buys Lava in a $300M deal; Mercado Bitcoin halts withdrawals after more than $40M is drained; Monzo reported to be exploring a round at about £7.5B; DoorDash buys Instacart for $17B; Fourthline and Veridas complete their merger; ECB picks Nexi and Deutsche Telekom as a digital euro network provider.
Funds. Six new vehicles this week: Creandum ($750M, its largest fund yet); Norrsken Evolve (€62M pre-seed fund); Octopus Ventures (first close of First Cheque II, targeting more than £20M); Evertrue Capital ($17M Fund I, early-stage AI and fintech); Robin Capital (€15M Fund II, pre-seed and seed in AI, robotics and space); IA Capital Group (initial close of Inter-Atlantic Opportunity Fund I, anchored by QBE Ventures).
All rounds
Equity
- Revolut — closes a funding round at a $115B valuation, led by Glade Brook Capital Partners
- Hoxton Wealth — $135M from Aspirity Partners, first outside funding since 2018
- Revel — round of more than €120M led by Openbank
- Amity — Series D of more than $100M, Krungsri Finnovate joins as an extension
- Pliant — $80M, Citi Ventures joins the cap table
- LO:TECH — $12M Series A led by MMC
- Kabilio — €10M to put AI agents inside accounting firms
- Finpilot — $10M Series A led by Lobby Capital, AI agents for institutional investing
- Takenos — $7M seed extension, stablecoin platform across Latin America
- Conlio — €6.4M to automate freight document checks
- CoverGo — $6M first close of Series B1 led by Betatron Venture Group, insurtech
- enza — $6M Seed+ led by 4DX Ventures, African payments infrastructure
- Lombard Systems — $4M to standardise financing against tokenised assets
- mamun — $3M seed led by Phaze Ventures, Gulf-Asia trade finance
- Granter — €1.6M to take its AI grant consultant from Portugal to Spain, Germany and Italy
- Crediflow AI — £1.5M to automate commercial loan processing
- Finfra — Series A extension from ADB Ventures, first investment of the NextFin Asia fund
- Soter Insure — SC Ventures and SBI join its Series B, led by Galaxy
No debt or credit rounds were posted this week.
VC funds
- Creandum — $750M, its largest fund yet [link]
- Norrsken Evolve — €62M pre-seed fund, final close
- Octopus Ventures — first close of First Cheque II, targeting more than £20M
- Evertrue Capital — $17M oversubscribed Fund I, early-stage AI and fintech in the UK and Europe
- Robin Capital — €15M Fund II, pre-seed and seed in AI, robotics and space
- IA Capital Group — initial close of Inter-Atlantic Opportunity Fund I, anchored by QBE Ventures
Market news
Stablecoins, crypto and tokenisation
- OKX brings its Mastercard stablecoin card to most US states
- Mercado Bitcoin halts withdrawals after more than $40M is drained from its wallets
- Circle reports $865M Q3 revenue and reserve income and cuts 5% of its workforce
- tZERO to go public through a $350M SPAC deal with FG Imperii Acquisition Corp.
- Morgan Stanley tokenises US stocks and Treasuries through DTCC’s new service [link]
- Uniform Labs launches Multiliquid Treasury, 24/7 T-bill yield for corporate cash [link]
- SBI to invest in US digital bank Erebor, eyeing blockchain settlements [verify: headline written from the Nikkei URL; amount and terms not in the doc] [link]
M&A and capital markets
- CD&R and GTCR weigh a $40B take-private of Global Payments
- DoorDash buys Instacart for $17B, 56% below its 2021 peak
- Bilt acquires sports loyalty platform Lava in a $300M deal
- UMB Financial agrees to buy El Dorado Savings Bank for about $506M
- Fourthline and Veridas complete their merger to create a European identity and fraud prevention group
- eToro agrees to acquire Argentine app LB Finanzas
- LTV co-led investor group acquires card decline recovery platform Kipp
- OpenAI cuts its funding target to $20B at a $1.25T valuation
- Monzo is reported to be exploring a venture round at about £7.5B
- Sequoia Capital is closing its London office
- British Business Bank commits £2M to co-invest with South East Angels
Regulation and licensing
- ECB selects Nexi and Deutsche Telekom as a digital euro network provider under a ten-year contract
- Revolut registered as a bank in New Zealand, its seventh banking licence and the first digital bank in the country
- Grey (YC W22) secures CBN approval to operate as an international money transfer operator in Nigeria
- Block agrees in principle to pay $764M to settle the DOJ anti-money-laundering probe
- Paraguay’s central bank puts digital lender ueno bank into resolution as its governor resigns
Results
- Mastercard reports $9.8B Q3 net revenue, up 14%, with value-added services up 19%
- Zilch reports £147.5M FY26 revenue, up 36%
- Chime reports $718M Q3 revenue, up 32%, and raises its 2026 outlook
AI, payments and partnerships
- Mastercard and Tencent’s TenPay Global sign an MoU on QR acceptance, remittances and agentic payments
- Anthropic adds personal finance tracking to Claude in US beta
- TBC Georgia becomes the first bank in Georgia to launch palm payments
- Deblock extends its card round-up to physical gold
- Birbank opens a redesigned Ganja branch built around a digital corner
On the platform
Companies raising and products listed on Builders in Fintech this week.
Raising now on the platform
- PagameYa — records the money owed between friends and follows each debt until it is paid, through WhatsApp and a web link, no app needed. Pre-seed, Argentina, raising $250K.
- Dividends — AI-powered SaaS that lets users own a piece of an established online business and share in its monthly cash flow. Pre-seed, United States, raising $1M.
Listings are provided by the companies, not verified, and not an offer. Raising? Get listed at [buildersinfintech.ai/raising](https://buildersinfintech.ai/raising).
Products
- Pliant — business credit cards, payment apps and card-issuing APIs for companies. API documentation and an MCP server available.
- Circle — USDC and EURC stablecoins plus payments, wallet and developer infrastructure. Developer docs and llms.txt available.
Raising now
Space for GPs and solo GPs launching funds. Not paid. If you’re raising and want to be listed, message me on LinkedIn.
- Parallax Ventures — fintech, LatAm. Raising Fund II. link · gennari@parallax.vc
- Founder Factor — YC-focused. Closed investments in YC W26 and is expanding the current vehicle. link
- RedFish Capital Partners — private equity, Italian SMEs in growth and mature phases. €200M+ AUM. Raising a new AIF with a soft commitment from the European Investment Fund. redfish.capital · investor.relations@redfish.capital
Listings are provided by the managers. Nothing here is investment advice.
Events, next 30 days
- Africa Stablecoin Summit — Johannesburg, 12–13 Nov
- Solana Breakpoint — London, 15–17 Nov
- Singapore FinTech Festival — Singapore, 18–20 Nov
- Fintech Nerdcon — San Diego, 19–20 Nov
- Bitcoin MENA — Abu Dhabi, 7–8 Dec
- Abu Dhabi Finance Week — Abu Dhabi, 7–10 Dec
Later:TOKEN2049 Dubai (21–22 Apr 2027) · Money20/20 Asia (Bangkok, 27–29 Apr 2027)
Want an event listed or sponsored? DM me.