Weekly update #117
The latest news from the fintech and VC ecosystems
Welcome to this edition of the weekly newsletter. The idea behind this is to gather all the information in the startup ecosystem in one place, with a special focus on the fintech market and the VC industry.
The latest episode of Builders was released last week! In this one, I sit down with Anil Stocker , CEO and founder of Kriya. You can find the full episodes here on YouTube, or here on Spotify and here on Apple Podcast. Here a short clip from the video:
Anil is a UK fintech entrepreneur and investor, best known as the CEO and co-founder of Kriya, formerly MarketFinance. He founded the company in 2011 to provide UK businesses with frictionless access to B2B payments, credit and embedded finance, and has since overseen the deployment of more than £4 billion in credit through invoice finance, business loans and PayLater solutions.
Under his leadership, Kriya raised over £50 million in equity and more than £500 million in debt from institutions including Barclays UK, Northzone, Mouro Capital, Deutsche Bank, Intesa Sanpaolo and the British Business Bank, before being acquired by Allica Bank in October 2025.
Before founding Kriya, Stocker worked in private equity at Lehman Brothers and later at Cogent Partners, focusing on alternative investments and post-crisis portfolio restructuring. He holds a first-class degree in Economics from the University of Cambridge, is a Forbes 30 Under 30 Finance alumnus, and is an active angel investor across fintech, SaaS and climate-focused startups.
With him, we will discuss the ups and downs of launching a fintech company, but also how tricky it is to sell it to a big player, what is coming after an exit, and the difference between being an investor and a founder.
Coming back to us, this week I’ve been reading two very interesting reports. The first one is from Crunchbase, and it’s an overview of investments in the fintech market in 2025, taken from their internal database. The second one, is “Fintech investment landscape 2025” from Innovate Finance, a comprehensive overview of fintech investments globally, with a focus on main geographical areas. Here my main takeaways:
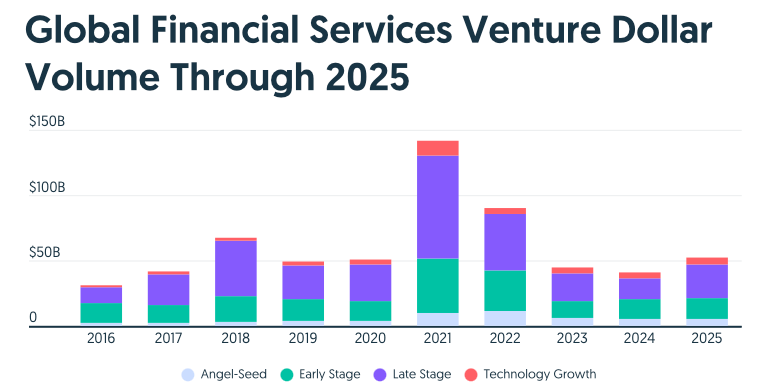
Let’s start from Crunchbase. Global venture investment in fintech rebounded in 2025, reaching its strongest level in several quarters, supported primarily by larger late stage financings, according to Crunchbase data. Total funding raised by VC backed financial technology companies worldwide reached 51.8 billion dollars during the year. This represents a 27 percent increase compared with 2024, when fintech startups raised 40.8 billion dollars.
Despite this recovery, overall funding levels remain well below the exceptional highs recorded earlier in the decade. In 2021, fintech investment peaked at 141.6 billion dollars, followed by 90.2 billion dollars in 2022. Still, the 2025 figures point to a clear upward trajectory, reversing the decline seen in 2024, when total funding fell below 2023 levels.
Importantly, 2025 marked the first time in recent years that global fintech funding surpassed pre pandemic benchmarks. Investment volumes exceeded the 50.8 billion dollars raised in 2020 and the 49.3 billion dollars recorded in 2019, suggesting a gradual normalization of capital flows into the sector.
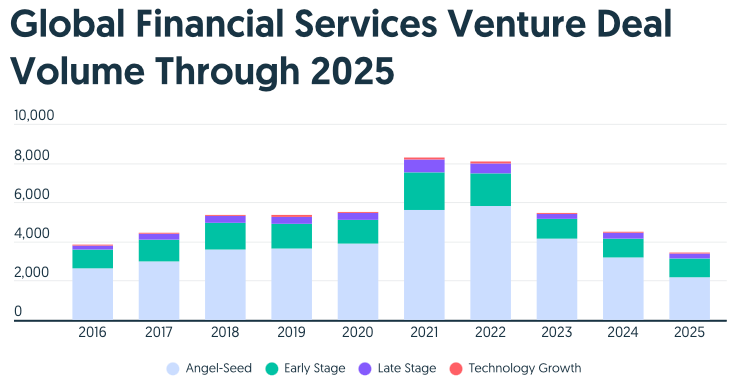
At the same time, deal activity continued to contract. A total of 3,457 fintech deals were completed in 2025, reflecting a 23 percent decline from more than 4,486 transactions in 2024. This divergence indicates a market characterized by fewer deals, but significantly larger average round sizes.
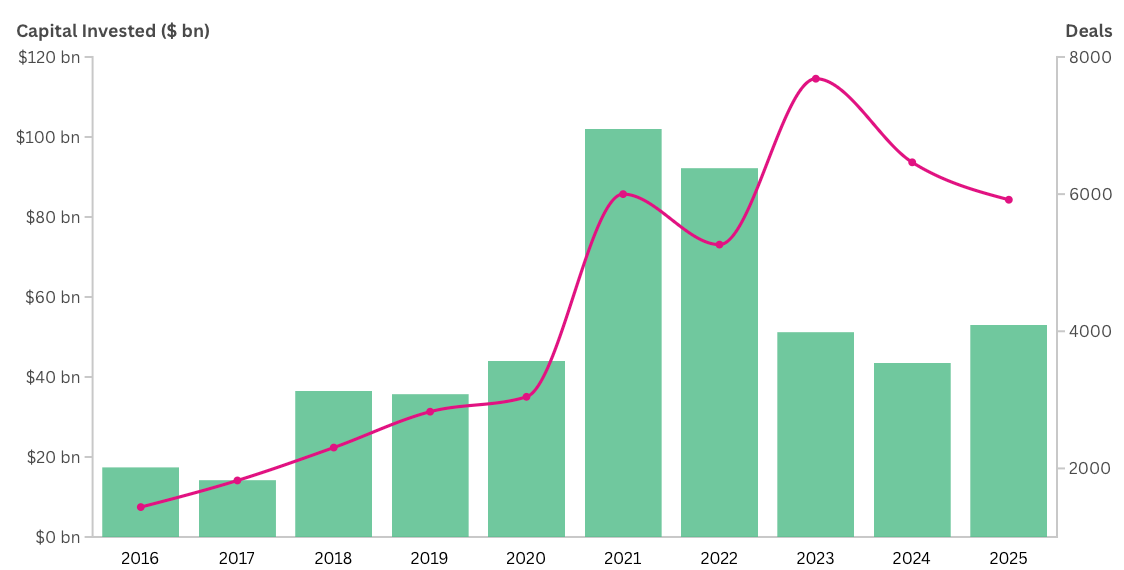
Innovate Finance shows similar data. Global FinTech investment returned to a growth trajectory, with the majority of regions recording increased activity. This rebound points to a more stable funding environment after several years of contraction and a broader investor recalibration. FinTech companies globally secured 53 billion dollars in funding across 5,918 transactions, underscoring sustained investor confidence in the sector, even as capital allocation remained disciplined and increasingly selective.
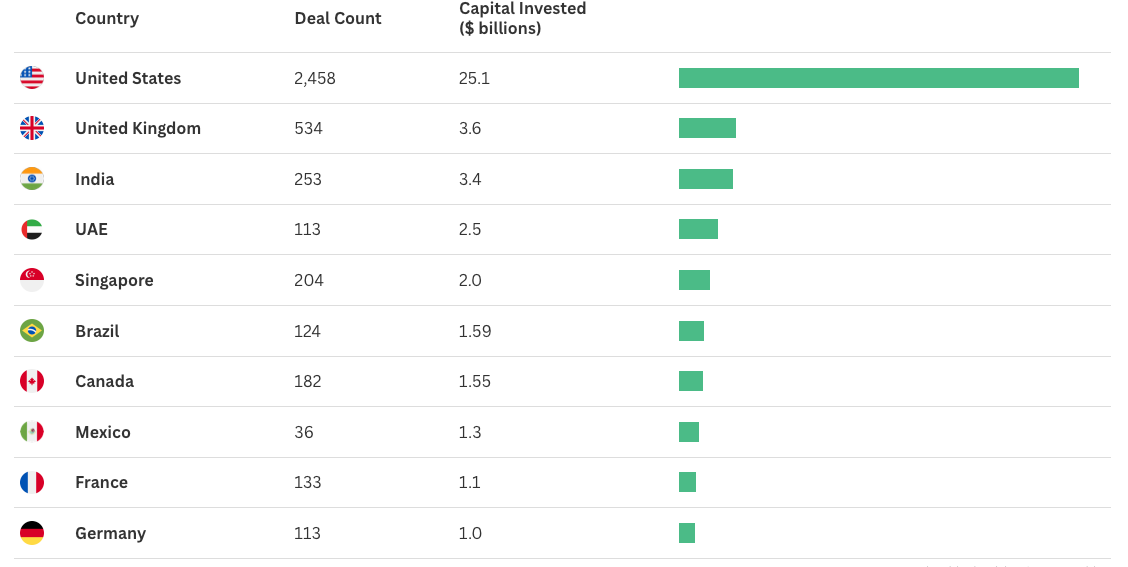
The US continued to lead the global FinTech landscape in 2025, attracting 25.1 billion dollars of investment across 2,449 deals and maintaining its position as the largest market by both capital deployed and transaction volume. The United Kingdom remained firmly in second place with 3.6 billion dollars raised, narrowly ahead of India, which ranked third with 3.4 billion dollars. The United Arab Emirates moved into fourth position globally with 2.5 billion dollars, marking its second entry into the global top ten, driven largely by Binance’s 2 billion dollar raise in the first half of 2025, the largest primary issuance in FinTech worldwide during the year.
Singapore secured fifth place with 2 billion dollars in funding. It was followed by a strong mid tier group in the Americas, with Brazil, Canada, and Mexico each raising between 1.3 and 1.6 billion dollars. France and Germany completed the top ten, reinforcing Europe’s continued importance in the global FinTech ecosystem.
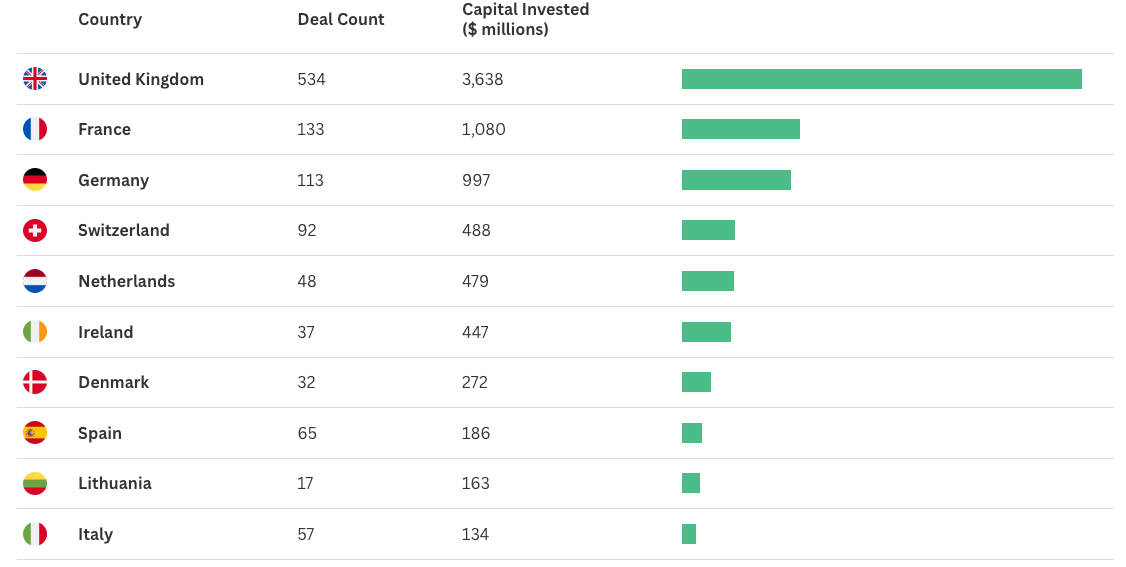
In 2025, Europe attracted a total of 8.8 billion dollars in FinTech investment across 1,391 deals, reflecting a broad and active funding environment across the region. The United Kingdom represented a significant share of this total, raising 3.6 billion dollars, while the rest of Europe accounted for the remaining 5.2 billion dollars.
The United Kingdom once again emerged as Europe’s largest FinTech market, securing 3.6 billion dollars across 542 transactions. France and Germany followed as the next most active markets, raising 1.08 billion dollars and 997 million dollars respectively. Both countries continued to draw capital into digital banking, payments, and financial infrastructure platforms.
Switzerland, the Netherlands, and Ireland each raised around 500 million dollars, demonstrating solid investment momentum, particularly in wealth management and payment processing. Spain, Denmark, Lithuania, and Italy rounded out the top ten European markets, each attracting between 100 and 300 million dollars in funding. Investment activity in these markets was increasingly focused on digital payments, lending, and cross border financial services, underscoring the depth and diversity of Europe’s FinTech ecosystem.
But let’s take a closer look at the main news of the last seven days. Revolut ends its beta phase and goes full operational in Mexico, N26 releases cards for under 18s in Germany, Nubank gets approval to launch a national bank in the US! But also, Checkout.com acquires Blue EMI, zerohash walks away from Mastercard deal and is looking for a new funding round, Circle extends USDC payments to EU and Asia, and Ledger is preparing for a potential IPO. Lots of new funds this week! 2150 closes a $210M fund, Basis Set a $250M fund, and Obvious Ventures a $360.36M fund. But also new vehicles from The Footprint Firm, TRAVELTECH.VC, seed + speed Ventures and Ascension Ventures. And finally, some very interesting funding rounds from fintech startups like Lunar, Vennre, Mesh, STAMP, Lerian, Sokin, Bleap and many others.
Let’s take a closer look:
Rounds
- Synthesia reaches $4B valuation in $200M Series E and enables employee liquidity
- Neem secures pre series A backing to build Pakistan’s full stack payments infrastructure
- Mine raises $14M Series A to launch AI money agent for Gen Z
- Lunar raises €46M to accelerate business banking and new lending products
- Vennre raises $9.6M to expand private market access across MENA
- Zocks | AI for Advisors raises $45M Series B to scale AI workflows for financial advisors
- Mesh becomes a unicorn with $75M Series C to build a global crypto payments network
- Paraglide AI raises €4.2M to deploy AI agents in accounts receivable across Europe
- Jelou AI raises $10M series A to turn WhatsApp into a transactional AI platform
- STAMP raises €4M to reinvent tax free payments for global shoppers
- Lerian raises $5.5M to challenge Pismo and Matera in core banking infrastructure
- Ex Revolut leaders raise $6M seed to scale onchain fintech app Bleap
- Mysa raises $3.4M to modernise finance operations for mid market enterprises
- Concourse raises $12M Series A and launches AI agents for finance teams
- Sokin secures $100M debt facility to scale embedded payments globally
- Dealroom.co raises €5.8M to expand global tech ecosystem intelligence
- Chip – your wealth app raises £17M at £208M valuation as Channel 4 Ventures backs TV expansion
- Valu secures $64M credit facility from National Bank of Egypt (NBE) to fuel regional growth
- Decagon raises $250M Series D, triples valuation to $4.5B
- WealthAi raises $800K pre seed to build an AI native OS for wealth managers
VC funds
- 2150 closes €210M Fund II, reaches €500M AUM to invest on climate tech
- The Footprint Firm closes €76M Fund I to scale Northern Europe climate tech
- TRAVELTECH.VC launches €50M travel tech fund to rebuild Europe’s digital tourism value chain
- Basis Set ventures closes $250M fund IV to back early system builders
- Obvious Ventures raises $360.36M fund V with focus on planetary, human, economic health
- b2venture raises €150M fund V to double down on European deeptech
- seed + speed Ventures closes €90M fund III to back enterprise AI in Europe
- Ascension Ventures secures up to €11.5M to back regional early stage founders in the UK
- Voyager Ventures closes $275M fund II, lifting AuM to $475M
- daphni Blue closes €260M fund to scale deeptech across Europe
News on the market
- J.P. Morgan acquires WealthOS to expand digital pensions infrastructure
- Ledger prepares for potential US IPO at valuation above $4B
- zerohash in talks to raise $250M at $1.5B valuation after stepping away from Mastercard deal
- Defaqto acquires Pearson Ham Group | The Pricing Specialists for £11m
- Revolut ends its beta phase and starts full operations in Mexico
- N26 expands into family banking with launch of ‘N26 for under 18s’
- Fiserv and Affirm extend BNPL to debit card programs
- Anchorage Digital and Tether.io launch USA₮, a US regulated dollar stablecoin
- Checkout.com acquires Blue EMI to add Euro stablecoin capabilities and opens Lithuania tech hub
- Circle extends USDC payments network to Europe and India
- Nubank receives conditional approval to establish US national bank
- finanzen.net GmbH acquires AI investing startup Vickii to scale personalised investing
- Nubank finally lands in Argentina with Buenos Aires tech hub!
- ZOHO.VC reaches 70% first close of inaugural fund ahead of schedule
Italian market
- -
And here some useful resources for everyone involved in the ecosystem:
Events you don’t want to miss
- FIBE | Berlin - 15th-16th April 2026 (Link here)
- Stablecon EMEA | Amsterdam - 19th-20th May (Link here)
You have a cool event you want to mention or to sponsor? Feel free to send me a DM.
Founders to watch in fintech
I also wanted to start shining a light on the most interesting fintech founders out there, so I thought to start sharing how I look for ideas to invest on. Every week, I will start sharing the most interesting founders in fintech, divided per area.
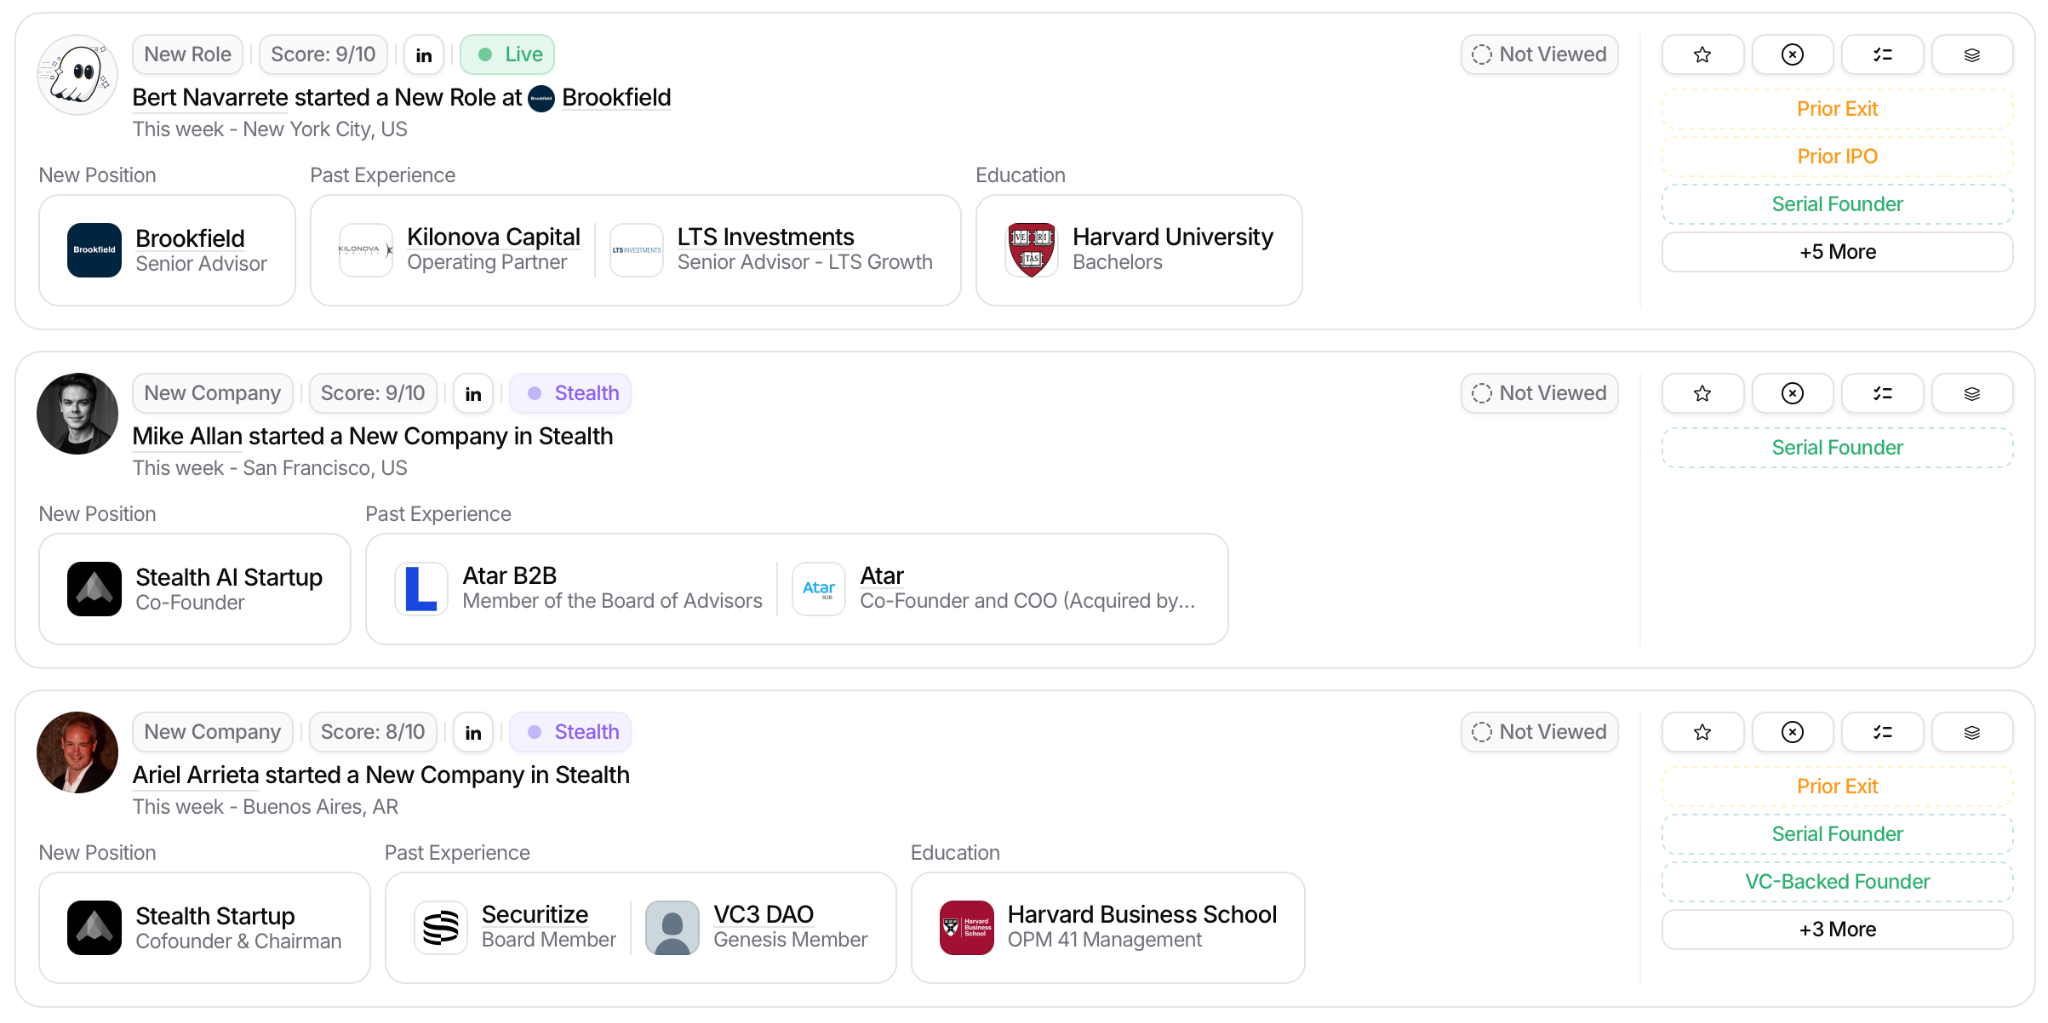
This week we take a look at the most interesting founders in fintech in Latam.
I usually use Spectre to scout for new ideas, the team is great and they also give me a free account once they learned I was a fan of the product. So if you wanna take a look at it, you can find it here.
New funds
I recently spoke with Marco Scotti from Raspberry Ventures. Thanks to their Y Combinator Alumni network, they unlock access to the top 10% of YC companies for Angel investors. Co-investing up to $3M across 15 - 25 companies in each YC batch, 4 batches a year, before Demo Day; and before the Silicon Valley VCs come in and take allocations in the best companies.
Their next batch YC W26m is closing February 1st, 2026. You can take a look here if you are interested!
Take also a look at the last edition of the newsletter, Weekly update #116.
Topics
Related funding
| Company | Round | Amount | Date |
|---|---|---|---|
| WealthAi Added · · Weekly update #117 | Pre-seed | 800,000 USD | 29 January 2026 |
| STAMP Added · · Weekly update #117 | 4,000,000 EUR | 26 January 2026 | |
| Chip Added · · Weekly update #117 | 17,000,000 GBP | 29 January 2026 | |
| Zocks Added · · Weekly update #117 | Series B | 45,000,000 USD | 26 January 2026 |
| Vennre Added · · Weekly update #117 | Pre-Series A | 9,600,000 USD | 27 January 2026 |
| Lerian Added · · Weekly update #117 | Seed | 5,500,000 USD | 27 January 2026 |
| Mesh Added · · Weekly update #117 | Series C | 75,000,000 USD | 27 January 2026 |
| Mine Added · · Weekly update #117 | Series A | 14,000,000 USD | 26 January 2026 |
| Concourse Added · · Weekly update #117 | Series A | 12,000,000 USD | 27 January 2026 |
| Valu Added · · Weekly update #117 | Credit facility | 64,000,000 USD | 29 January 2026 |
| Neem Added · · Weekly update #117 | Pre-Series A | 27 January 2026 | |
| Jelou AI Added · · Weekly update #117 | Series A | 10,000,000 USD | 26 January 2026 |
| Decagon Added · · Weekly update #117 | Series D | 250,000,000 USD | 29 January 2026 |
| Mysa Added · · Weekly update #117 | 3,400,000 USD | 27 January 2026 | |
| Dealroom.co Added · · Weekly update #117 | 5,800,000 EUR | 29 January 2026 | |
| Paraglide AI Added · · Weekly update #117 | Seed | 5,000,000 USD | 27 January 2026 |
| Sokin Added · · Weekly update #117 | Debt facility | 100,000,000 USD | 29 January 2026 |
| Lunar Added · · Weekly update #117 | 46,000,000 EUR | 27 January 2026 |