Weekly update #158
Builders Fintech Funding Index: 181 (last full week, week of 2 Nov). 30 equity rounds recorded, against a 12week average of 17. Median disclosed USD round: index 60. Our round coverage expanded in September 2026, so the Index overstates activity until midDecember. Full reading
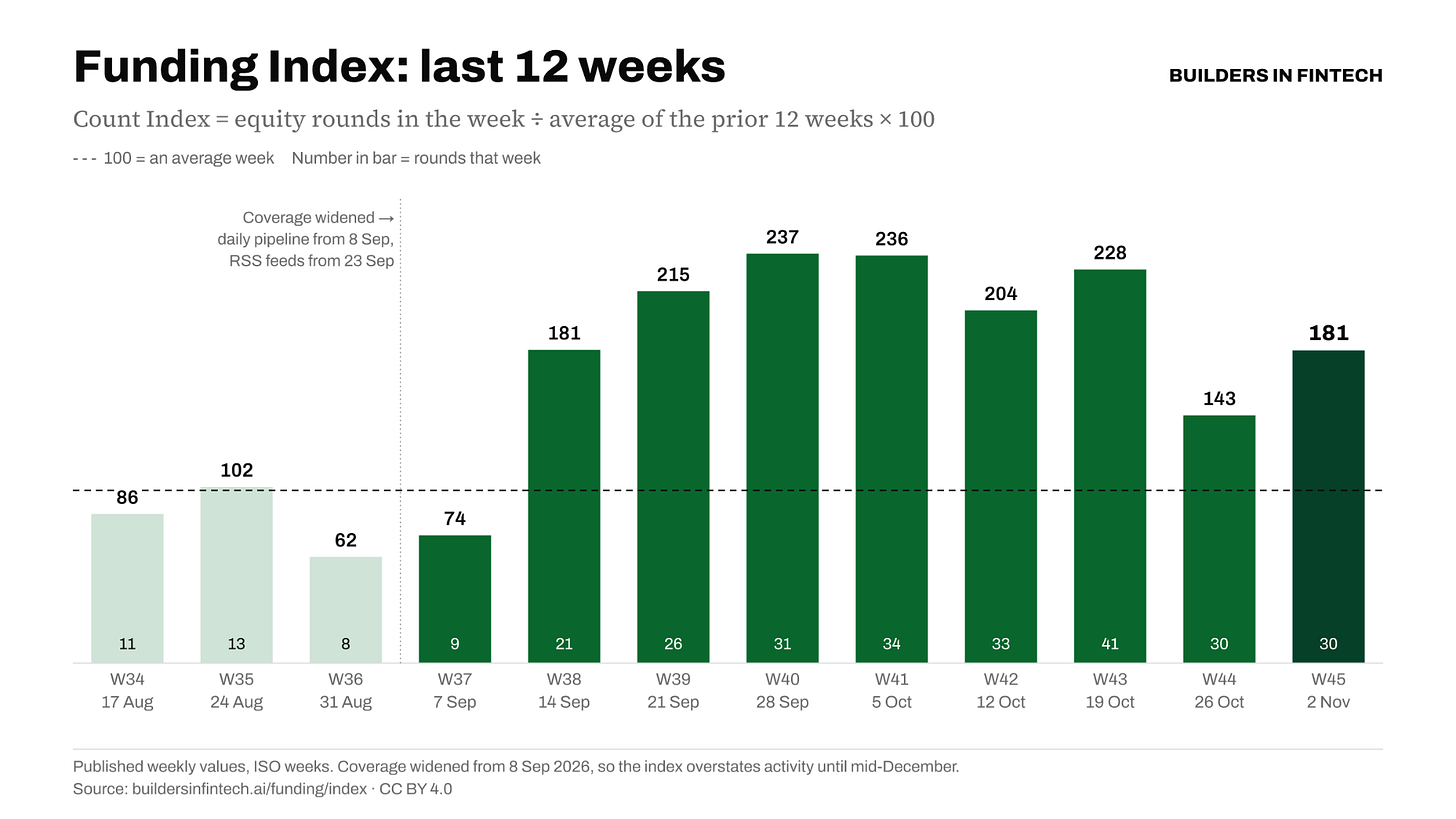
Builders Fintech Funding Index: 181 (last full week, week of 2 Nov). 30 equity rounds recorded, against a 12-week average of 17. Median disclosed USD round: index 60. Our round coverage expanded in September 2026, so the Index overstates activity until mid-December. Full reading
Imprint raised $130M at about a $1.9B valuation led by Khosla Ventures, Kalshi is in talks to raise at a $65B valuation, and Affirm agreed to buy Ratepay from Nexi. Below: McKinsey & Company‘s Banking on AI report on distressed credit (US card balances flowing into serious delinquency at 7% a year, CFPB debt-management complaints above 200,000, 7% of organisations with AI fully deployed), the week’s rounds and funds, and three managers raising now.
Builders in Fintech:Episode #56 aired on Tuesday, my guest was Lorenzo Romagnoli, co-founder of USDT0 , the interoperability layer for Tether’s USDT. Episode page and notes.
All episodes: YouTube · Spotify · Apple Podcasts · Amazon. Founders and VCs who want to come on the show: message me on LinkedIn.
Builders in Fintech Daily: yesterday’s rounds and news, every weekday at 8:00. Subscribe here.
The report: AI in collections and distressed credit
McKinsey & Company, Banking on AI: How a new operating model can transform distressed credit management. The Risk Practice on why banks that run AI in collections should move from separate use cases to an agentic operating model. Here my main takeaways:
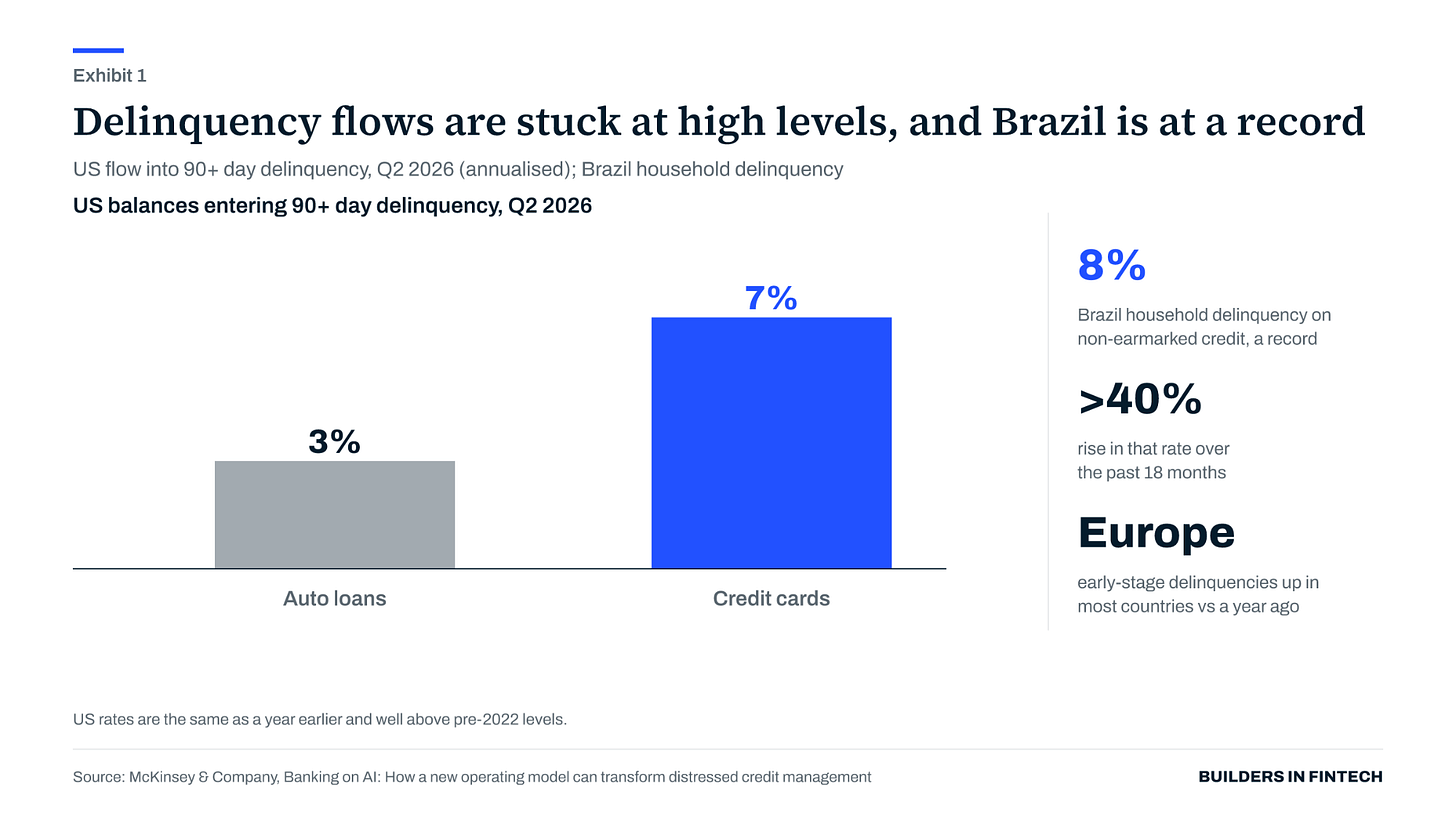
The pressure. In the US, auto loan balances entered 90+ day delinquency at an annualised 3% in Q2 2026 and credit card balances at 7%, the same as a year earlier and well above pre-2022 rates. Early-stage delinquencies rose in most European countries. In Brazil, household delinquency on non-earmarked credit is up more than 40% in 18 months, to a record 8%.
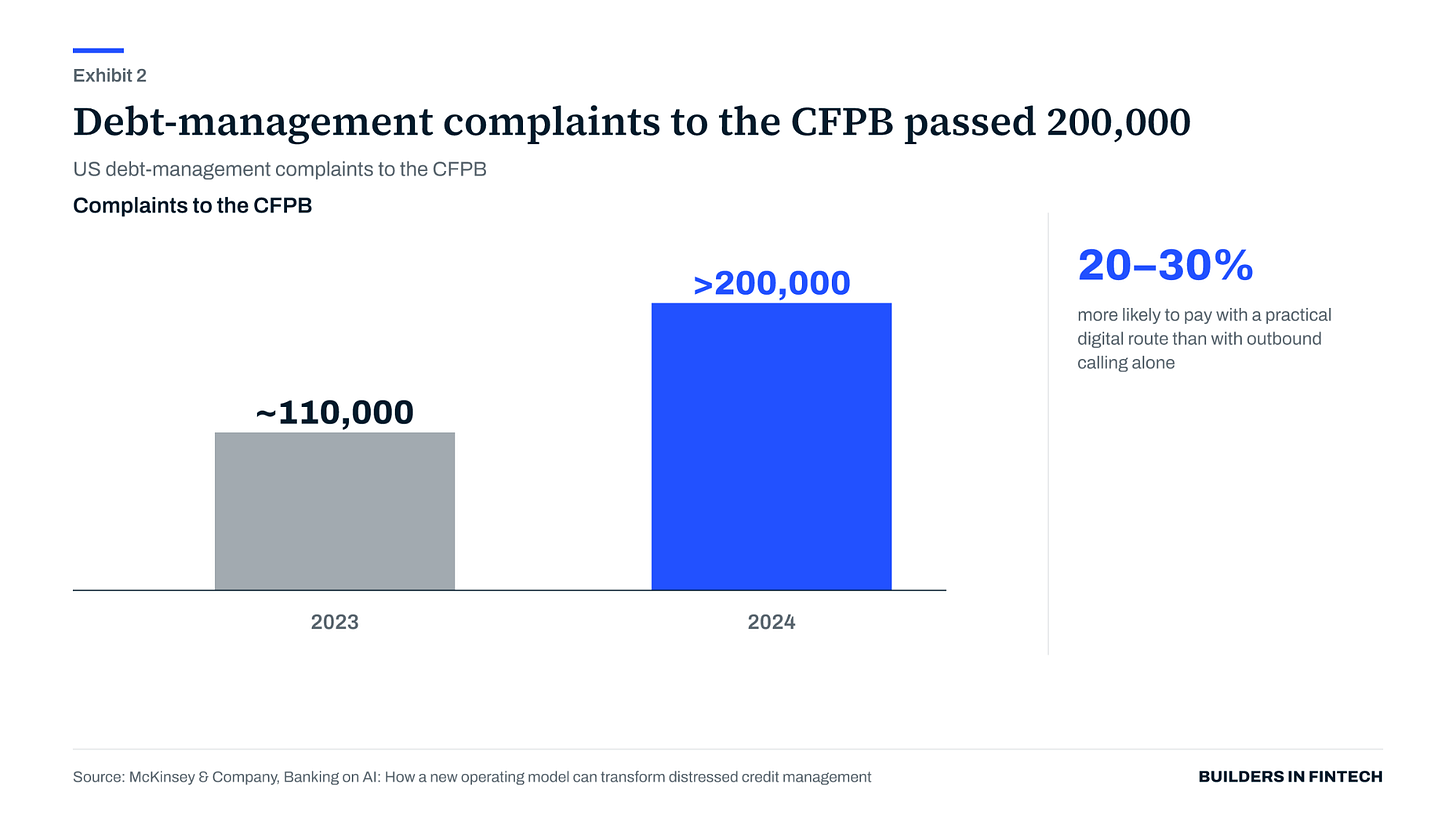
Conduct and service. US debt management generated more than 200,000 complaints to the CFPB in 2024, up from about 110,000 in 2023. Digital-savvy borrowers given a practical digital route to deal with arrears are 20–30% more likely to pay than those reached by outbound calling alone. Unit economics add a third pressure: cost per unit recovered, and capacity for a possible downturn, with digital-native lenders setting the benchmark.
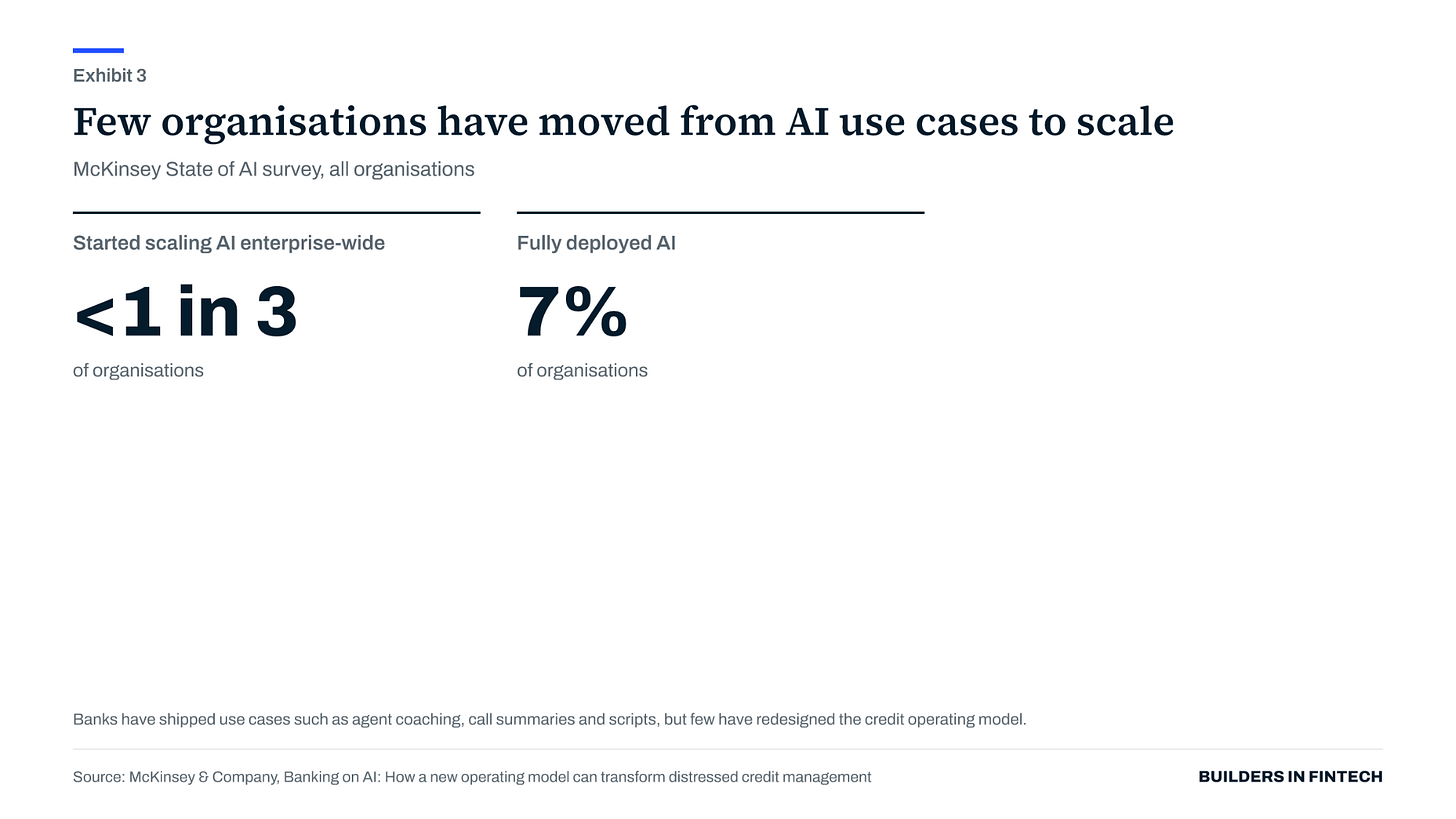
The adoption gap. McKinsey’s State of AI survey finds fewer than one in three organisations have started scaling AI across the enterprise, and 7% have fully deployed it. Banks have shipped use cases in collections (agent coaching, call summaries, generated scripts), but few have changed how their credit organisations run.
The model. Specialised agents across five building blocks: portfolio insights and strategy; segmentation and prioritisation, with daily recalibrated value-at-risk and self-cure models and early-distress flags in the performing book; allocation and routing, for example passing a case to an external agency after three failed digital attempts; digital and voice engagement; and human-assisted resolution, where a copilot coaches the collector and a restructuring agent prices offers on NPV, collateral and ability to repay. The agents sit on top of core banking, CRM and dialers as an orchestration layer, not a replacement.
Autonomy and rollout. Standardised, low-risk steps (segment definition, channel allocation, digital messaging, outbound calls on low-exposure accounts, post-call wrap-up) can run without case-by-case approval. Non-standard restructuring terms and allocation to external agencies keep a human in the loop. The path runs from MVP 0 (isolated use cases) to MVP 1 (one integrated flow, such as an early-bucket portfolio), MVP 2 (the full portfolio, with human approvals) and then full orchestration.
The read. The report is less about AI than about who owns the workflow. Collections is a process where the customer is already in trouble, the regulator is watching and every call has a measurable recovery value, so it is a clean test of whether agents can run a process rather than assist one. Positioned well: lenders that already reach borrowers digitally, and vendors such as Guava, which raised a $12.5M seed this week for voice AI agents in regulated industries. Exposed: card and auto lenders still built on outbound calling while US card delinquency flows hold at 7% and complaints have almost doubled. Watch Brazil, where household delinquency sits at a record 8%.
The week in six stories
- Imprint raises $130M at about a $1.9B valuation, led by Khosla Ventures. The New York co-brand card company raised $150M at $1.2B in December 2025. The equity comes with $1.5B of additional warehouse borrowing capacity.
- Kalshi is in talks to raise at a $65B valuation. Bloomberg reported the talks on 12 November, weeks after a $1B round at $40B co-led by Sequoia and Wellington. Terms are not final.
- Affirm agrees to buy Ratepay from Nexi. Ratepay serves merchants in Germany, Austria and Switzerland; Nexi and Affirm also signed an MoU to extend their DACH partnership. No price was disclosed.
- Clara raises a $65M Series C led by Citius, Kaszek and DEG, in $105M of financing. The rest is a renewed $40M facility from General Catalyst’s Customer Value Fund. Coatue, DST Global and Monashees took part.
- Nubank posts a record $1.1B quarterly net income and reaches 143M customers. Q3 2026 net income rose 31% year on year on an FX-neutral basis; revenue reached $6.3B, up 37%, and ROE was 32%.
- Western Union terminates its agreement to acquire Intermex. It delivered notice on 10 November after California’s DFPI set final conditions it would not accept. Every other jurisdiction had approved, and neither side owes a termination payment.
Also: Revolut commits at least $1B to Latin America and gets a conditional banking licence in Israel; Goldman Sachs, Citi and other banks commit about $270M to the Project Faro stablecoin venture; Coinbase gets a full OCC charter for Coinbase National Trust Company; Alta raises a $47.5M Series A led by Index Ventures; Cocos raises $34M led by Kaszek at a $508M valuation; Gemini reportedly sells its UK and European operations to KAST for under $10M; Metro Bank launches a formal sale process; Airwallex to invest more than SGD 2B in Singapore over five years.
Funds. Seven new vehicles this week: Norwest (Norwest 18, $4B, its largest fund in 65 years); redalpine (Fund VIII, $250M, its largest to date); Vine Ventures (Fund III, $236M, US and Israeli startups); Flashpoint Capital (Venture Growth Fund IV, $116M); Course Corrected (Fund II, €80M, European energy and resource transition); blacksheep (first close of BlackSheep II, €60M, targeting €100M, domain-specific AI); Enza Capital (first close of its AI Africa Fund, $21M).
All rounds
Equity
- Imprint — $130M at about a $1.9B valuation led by Khosla Ventures, co-brand credit cards, US
- Clara — $65M Series C led by Citius, Kaszek and DEG, in $105M of financing, corporate cards and spend management, Mexico
- Alta — $47.5M Series A led by Index Ventures, bringing total funding to $80M
- Cocos — $34M led by Kaszek at a $508M valuation
- Sumary — $25M seed led by Singular, AI accounting software
- Griffin — $20M Series B led by Octagon Partners at a valuation above $100M, UK
- Genios AI — $19.1M seed and Series A, out of stealth
- Uranium Digital — $16.5M Series A led by Blockchain Capital
- firmly — $15M Series A led by Squarepoint Capital, connects merchants to AI shopping channels
- Guava — $12.5M seed led by Acrew Capital, voice AI agents for regulated industries
- Marble — $11M seed led by Polychain, finances AI compute and runs institutional trading
- Palomma — $10M Series A led by Cometa, rent payments, Colombia
- ancep — $8.5M led by Creandum, AI agents for commercial insurance brokers
- Planky — €6.9M co-led by Innovation Global and Azimut, AI credit decisioning
- Lumepay — $6M pre-seed, African cross-border B2B payments
- Light Frame — $5.1M seed led by Fortino Ventures, wealth core banking software
- Seva Money — $5M seed co-led by Blockwall and Revent, wallets for remittance recipients
Debt and credit
- Momenta Finance — up to £200M facility from Lloyds, UK SME lending
- Zilch — a further £165M in debt facilities led by Deutsche Bank, UK
- Nexu — MXN 1,013M revolving credit line from BBVA Spark, auto loans, Mexico
- BillEase — PHP 500M credit facility from PBCOM, Philippines
VC funds
- Norwest — $4B Norwest 18, its largest fund in 65 years
- redalpine — $250M Fund VIII, its largest to date
- Vine Ventures — $236M Fund III, US and Israeli startups, above its $200M target
- Flashpoint Capital — $116M Venture Growth Fund IV
- Course Corrected — €80M Fund II, European energy and resource transition startups
- blacksheep — €60M first close of BlackSheep II, targeting €100M, domain-specific AI, Europe
- Enza Capital — $21M first close of its AI Africa Fund
Market news
Stablecoins, crypto and tokenisation
- Stripe’s Crypto Onramp powers USDC purchases in the new Samsung Wallet Stablecoin Account
- Coinbase lets US users borrow USDC against tokenised gold PAXG through Morpho
- Coinbase gets a full OCC charter for Coinbase National Trust Company
- Goldman Sachs, Citi and other banks commit about $270M to the Project Faro stablecoin venture
- Visa adds Western Union’s USDPT stablecoin to VisaNet settlement through Anchorage Digital
- DTCC to connect its Tokenization Service to Solana in the second half of 2027
- Securitize to acquire warehouse financing platform River One
- Gemini reportedly sells its UK and European operations to KAST for under $10M
M&A and capital markets
- Nexi agrees to sell payment provider Ratepay to Affirm
- Western Union terminates its agreement to acquire Intermex over California’s conditions
- National Bank of Canada to acquire RESP provider Embark for about C$226M
- Morgan Stanley agrees to acquire transfer agent Vinyl Equity
- WeRoad acquires Swiss TravelTribe, its first deal in a plan to add €70M in revenue through M&A
- Kalshi in talks to raise at a $65B valuation, up from $40B in October
- Crédit Agricole proposes merging Crédit Agricole Italia with Banco BPM
- Metro Bank launches a formal sale process after its most profitable half-year
Expansion and licensing
- Revolut commits at least $1B to Latin America, with Brazil its largest expansion market
- Revolut gets a conditional banking licence in Israel
- Wise launches Interest and Stocks for US customers, its first use of its US broker-dealer licence
- Airwallex to invest more than S$2B in Singapore over five years and grow its team past 1,000
- Depay launches USD virtual accounts for Latin American banks and wallets
AI, payments and products
- Revolut Pay goes live in the Uber app across the UK and Europe
- zerohash acquires an agent-identity infrastructure stack and names its creator Mark Meadows Head of Applied AI
- DoorID launches a 70-second check that ties a customer to an address
- Wealthsimple unveils AI assistant Penny among 12 new releases
- HSBC UK launches Tap to Pay for small businesses, powered by Stripe
Results and people
- Nubank posts a record $1.1B quarterly net income and reaches 143M customers
- Klarna names Robinhood’s Chris Koegel as CFO from 1 January 2027
On the platform
Companies raising and products listed on Builders in Fintech this week.
Raising now on the platform
Listings are provided by the companies, not verified, and not an offer. Raising? Get listed at [buildersinfintech.ai/raising](http://buildersinfintech.ai/raising).
Products
- Clara — corporate cards and spend management for companies in Mexico, Colombia and Brazil; the company raised a $65M Series C this week. API documentation, an OpenAPI spec and llms.txt available.
- Griffin — UK bank offering banking-as-a-service through an API; it raised a $20M Series B this week. OpenAPI spec, llms.txt and a self-serve sandbox available.
Raising now
Space for GPs and solo GPs launching funds. Not paid. If you’re raising and want to be listed, message me on LinkedIn.
- Parallax Ventures — fintech, LatAm. Raising Fund II. link · gennari@parallax.vc
- Founder Factor — YC-focused. Closed investments in YC W26 and is expanding the current vehicle. link
- RedFish Capital Partners — private equity, Italian SMEs in growth and mature phases. €200M+ AUM. Raising a new AIF with a soft commitment from the European Investment Fund. redfish.capital · investor.relations@redfish.capital
Listings are provided by the managers. Nothing here is investment advice.
Events, next 30 days
- Solana Breakpoint — London, 15–17 Nov
- Singapore FinTech Festival — Singapore, 18–20 Nov
- Fintech Nerdcon — San Diego, 19–20 Nov
- Bitcoin MENA — Abu Dhabi, 7–8 Dec
- Abu Dhabi Finance Week — Abu Dhabi, 7–10 Dec
Later:TOKEN2049 Dubai (21–22 Apr 2027) · Money20/20 Asia (Bangkok, 27–29 Apr 2027)
Want an event listed or sponsored? DM me.
Previous edition: Weekly update #157