Weekly update #149
The weekly update on the fintech and VC ecosystems
Ramp is in early talks for a ~$1B Series G at a $60B valuation, Chime is buying its partner Stride Bank for $590M to own a charter, and Circle agreed to pay $400M in stock for Tazapay. Below: SBI Ventures Europe’s H1 2026 read on European fintech (fewer deals, larger checks, regulation as the moat), the week’s rounds and funds, and three managers raising now.
Builders in Fintech: Season 5 aired last week on Tuesday with episode #51, where my guest was Gaston Irigoyen, CEO and founder of Pomelo. You can take a look at the full episode watch the full episode on YouTube on YouTube or listen to the full episode on Spotify on Spotify. This week another episode will be live on Tuesday at 10.30am CET!
All episodes: YouTube · Spotify · Apple Podcasts · Amazon. Founders and VCs who want to come on the show: message me on LinkedIn!
The report: European fintech, fewer deals and a regulatory moat
SBI Ventures Europe, European Fintech H1 2026: Selectivity, Regulation and the Infrastructure Opportunity. The report explores investments in the European fintech sector during H1, 2026. Here my main takeaways:
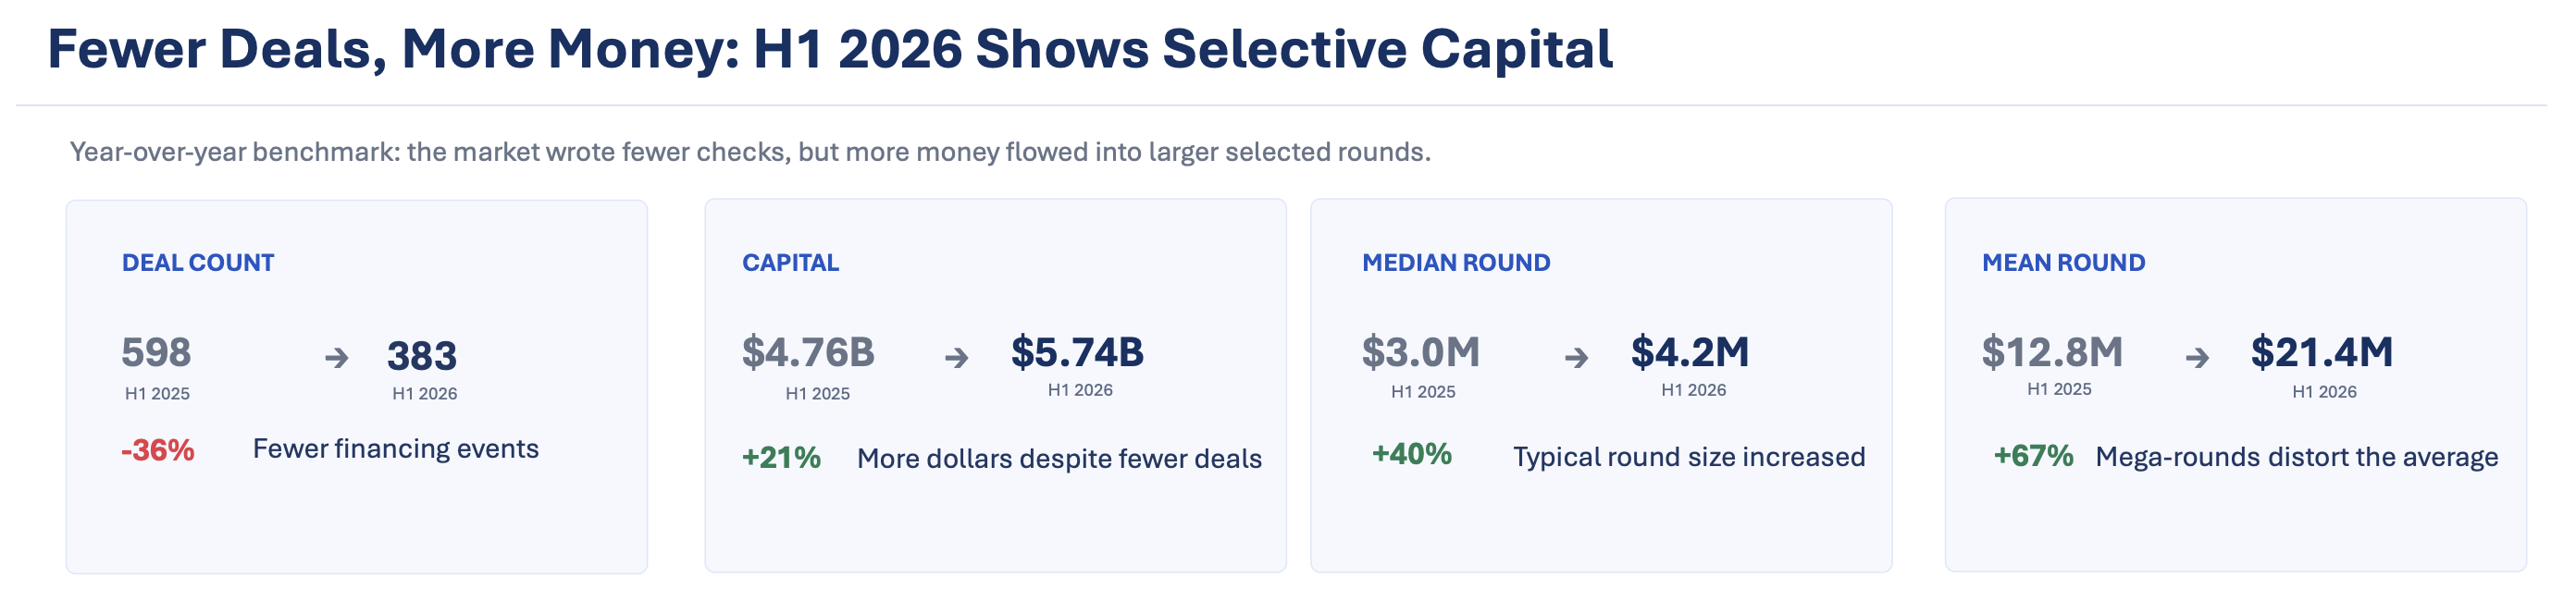
The numbers. 383 deals in H1 2026, down 36% from 598 a year earlier, but disclosed capital rose 21% to $5.74B. Median round went from $3.0M to $4.2M (+40%); the mean from $12.8M to $21.4M. 61% of deals were early-stage. The top 10 deals took $1.8B, or 31% of all capital, and $100M+ rounds went from 8 to 9. For scale: the US did 1,280 deals and $22.3B in the same period.
Where the big checks went. Alan $538M Series G, Pennylane $240M Series E, Morpho $175M Series C, 9fin $169M Series C, Allica Bank $155M Series D, Elliptic $120M Series D, Taktile $110M Series C, Primer $100M Series C, Keyrock $100M Series C, Upvest $90M equity (the $125M headline included a $35M debt facility). Three French companies took 53% of top-10 capital. Three digital-asset companies made the list.
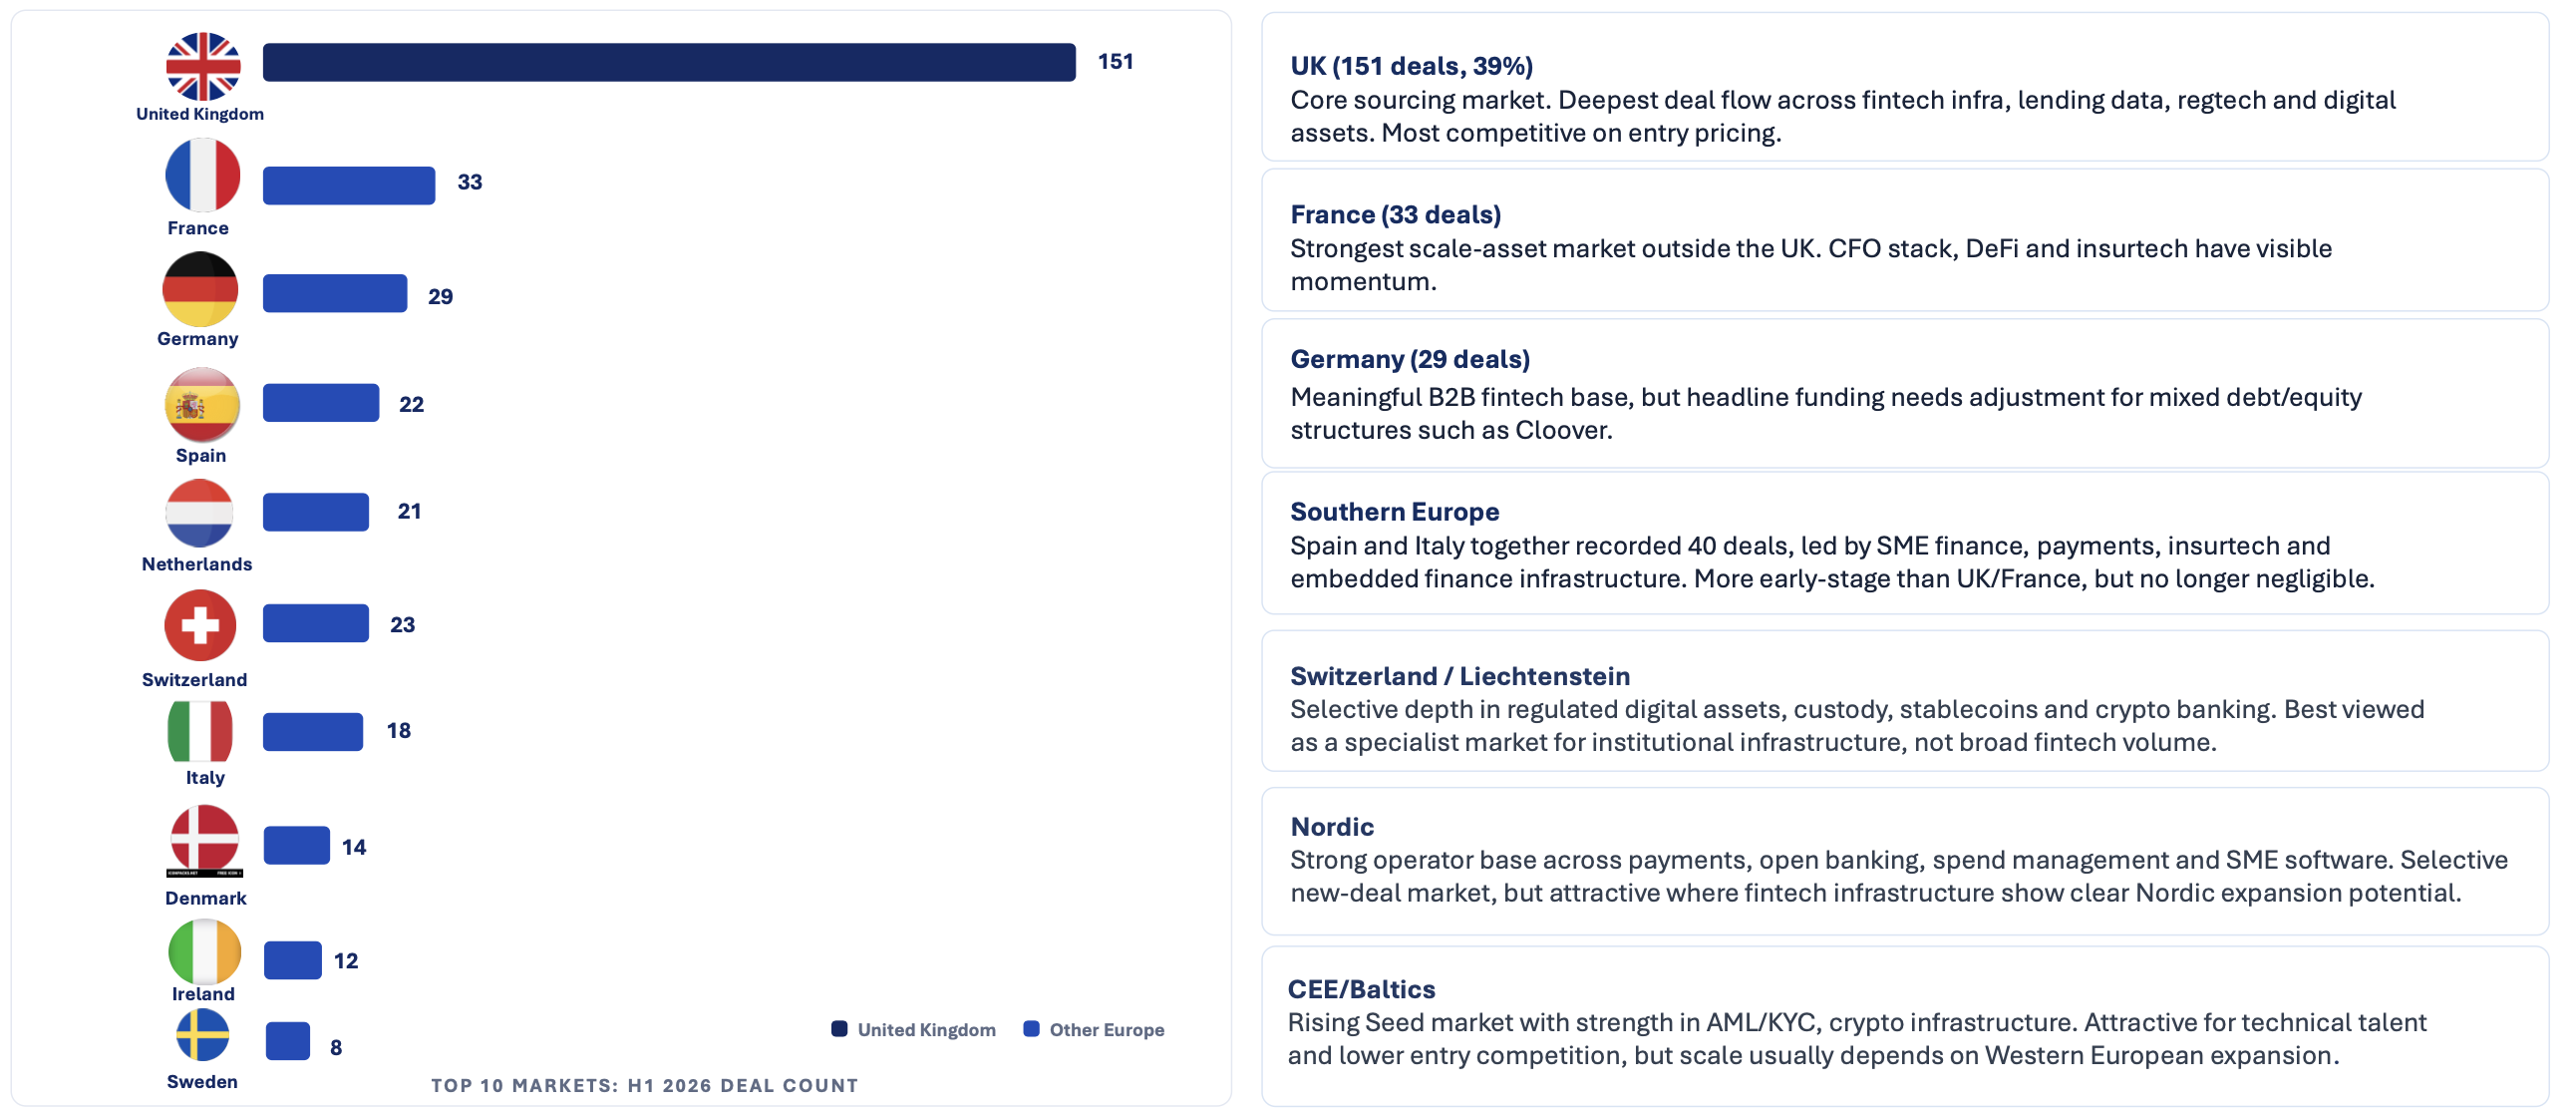
Geography. UK 151 deals (39% of the market, -26% YoY), France 33 (-37%), Germany 29, Switzerland 23, Spain 22 (+22%), Netherlands 21, Italy 18 (+12%), Denmark 14, Ireland 12, Sweden 8 (-56%). Spain and Italy together did 40 deals in a contracting market. Most active investors by deal count: Index Ventures (8), SFC Capital (7), Fuel Ventures and Seedcamp (6 each); among public investors Lazio Innova (10) and CDP Venture Capital (5); among strategics Coinbase Ventures (6).
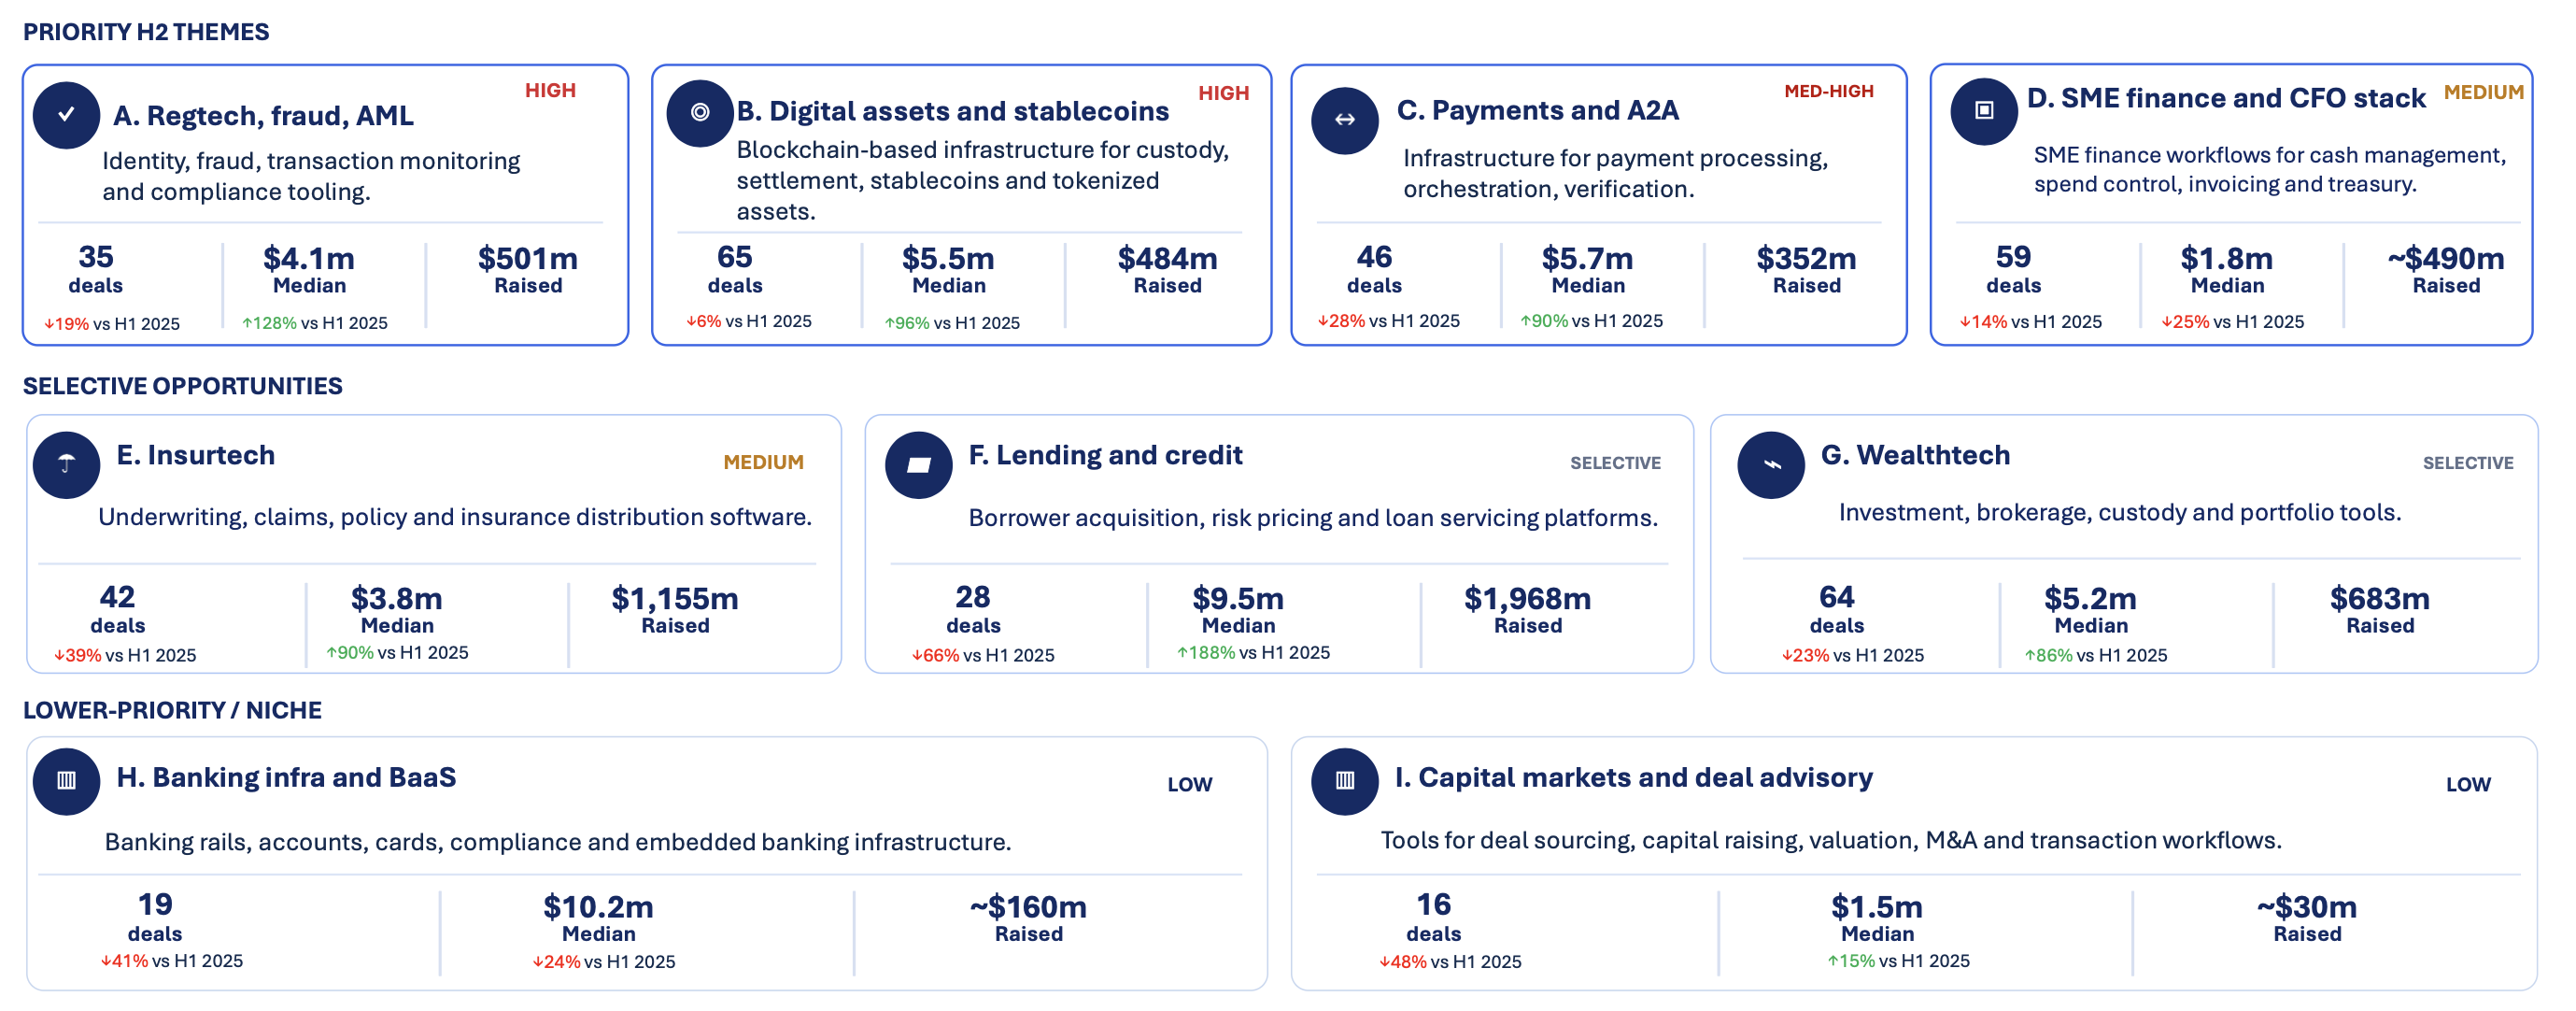
Sectors. Lending deal count collapsed 69% (78 to 24) even though the sector raised the most disclosed capital ($1.97B). Regtech/AML: 35 deals, median up 128% to $4.1M, $501M raised. Digital assets: 65 deals, median up 96% to $5.5M, $484M raised. Payments/A2A: 46 deals (-28%), median up 90% to $5.7M, $352M raised. SME/CFO stack: 59 deals, median down 25% to $1.8M. Banking infra/BaaS: 19 deals (-41%). SBI ranks regtech and licensed digital assets as the top H2 themes and lists generic BaaS, consumer BNPL and generic AI copilots as no-go areas.
Exits. 50 M&A transactions worth $4.0B, 22 PE/buyout deals worth $289M, zero VC-comparable IPOs. Largest: Inigo Insurance to Radian Group ($1.67B), PrimaryBid to SoFi ($519M), Lendo Group to Clar Global ($458M), Billhop to Ramp ($395M), October to Aether Financial Services ($155M). Named IPO candidates: Monzo, Zilch, Bitpanda, Revolut.
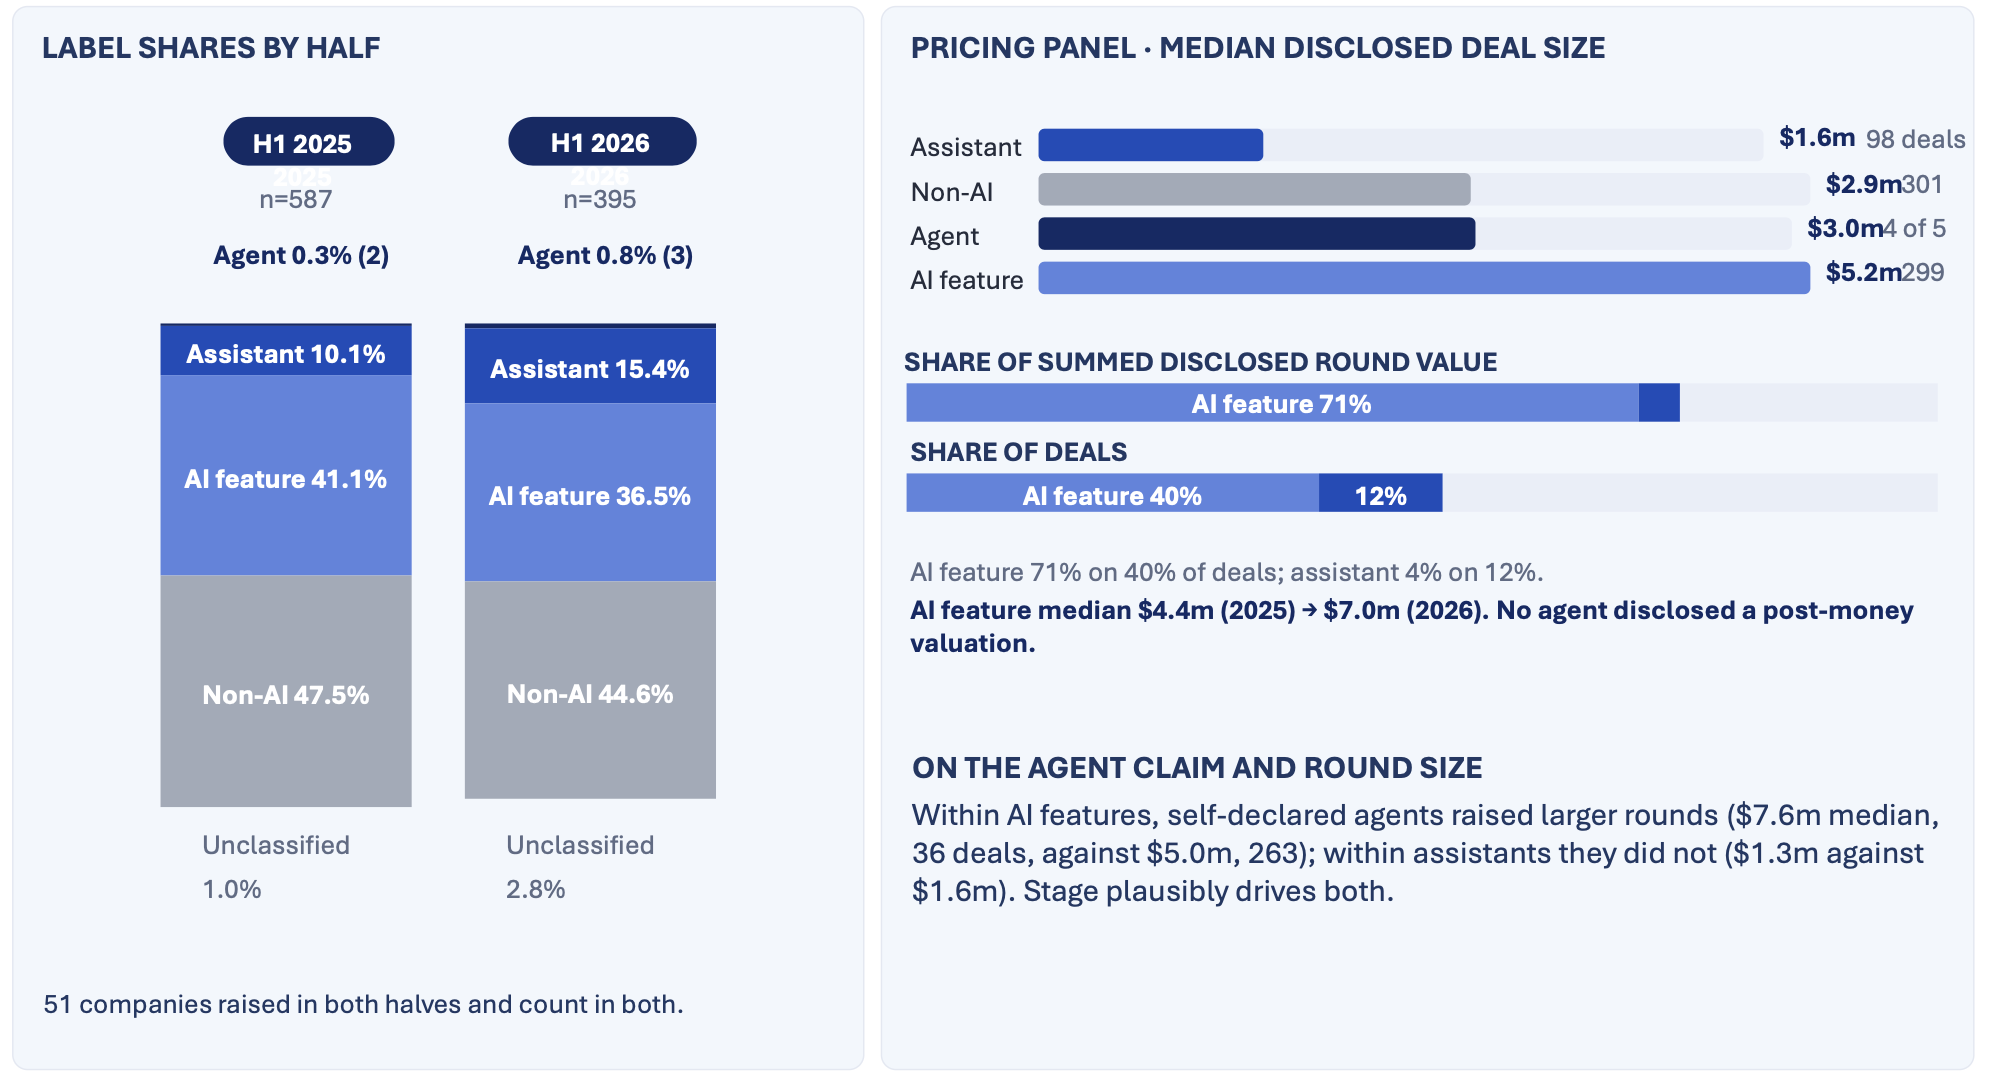
AI, counted properly. AI-tagged deal share rose from 30% to 42%. Of 931 fintechs screened across both halves, 481 ship a working AI product and 5 qualify as agents; 84 describe themselves as agents. AI-feature companies took 71% of disclosed round value on 40% of deals, with the AI-feature median rising from $4.4M to $7.0M.
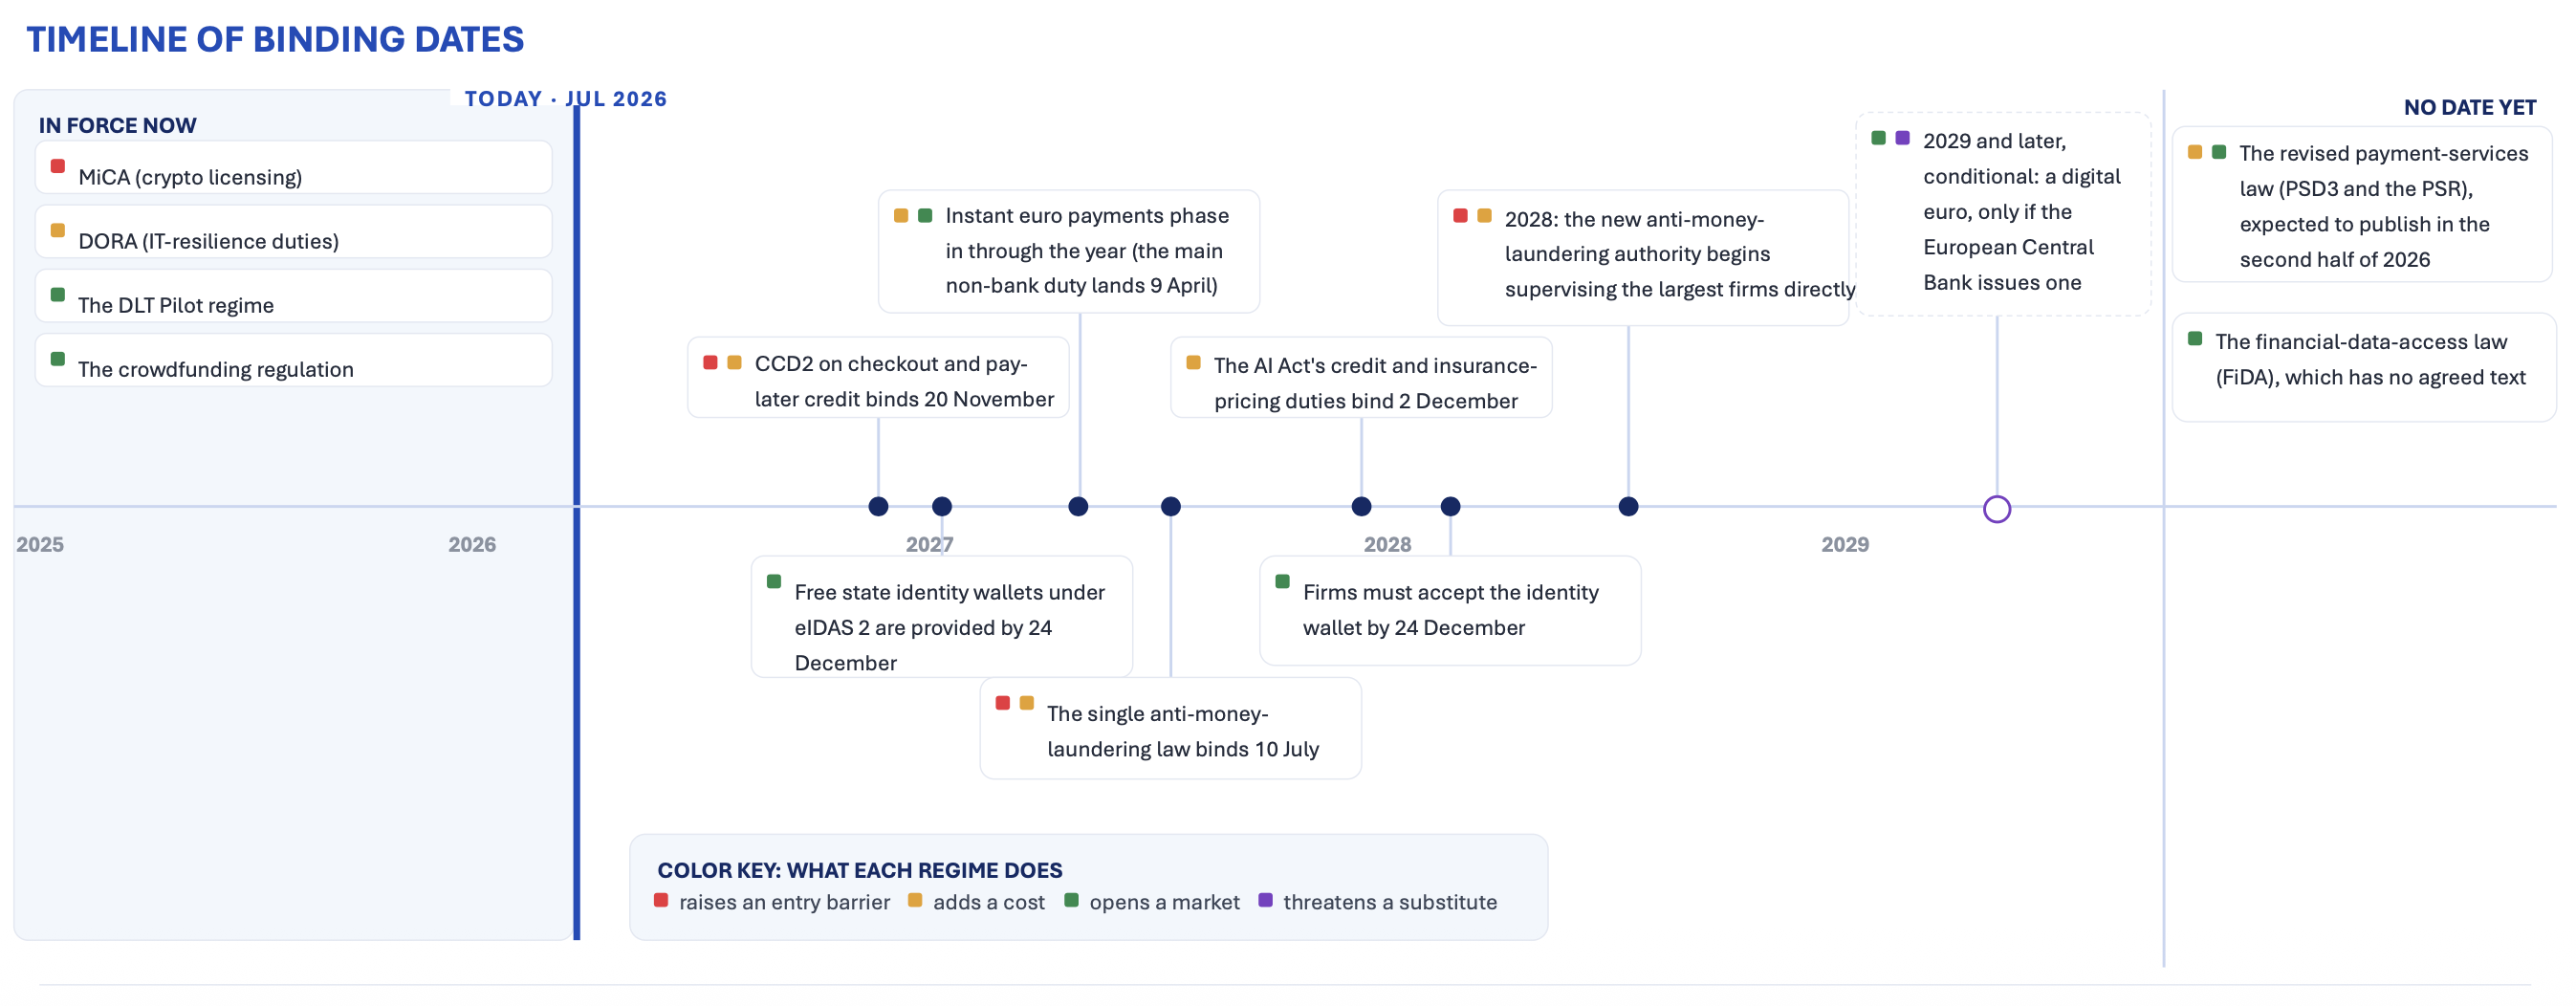
The regulatory calendar. MiCA fully live since 1 July 2026 (one CASP licence, €50–150k capital, passport to 27 states). CCD2 binds 20 November 2026. eIDAS 2 state wallets by 24 December 2026, mandatory acceptance by 24 December 2027. Instant Payments non-bank duty 9 April 2027. Single EU AML rulebook 10 July 2027, AMLA direct supervision from 2028. AI Act high-risk duties for credit scoring and insurance pricing 2 December 2027. PSD3/PSR text expected H2 2026; FiDA has no agreed text.
The read. The European market did not recover in H1; it filtered. A third fewer companies raised, but the ones that cleared raised at higher medians, and capital pooled where a licence, a compliance mandate or a settlement rail creates non-optional demand. That is where margin is moving: regtech medians more than doubled, licensed digital-asset infrastructure kept its deal count while everything else shrank, and payments capital went to rail operators rather than orchestration. The companies best positioned are the ones already holding the permission: Elliptic, Taktile, Keyrock, Upvest and the MiCA-licensed CASPs, plus the AML vendors selling into a July 2027 deadline. Exposed: Series A/B companies without a regulatory hook (growth-stage share fell from 23% to 17%), lending platforms without a named lender, and B2C apps facing rising CAC. This week’s news reads the same way: Chime, Block and Nubank all chose to own or apply for a charter, TRM Labs doubled its valuation on compliance demand, and Circle bought last-mile licences with Tazapay. Watch Italy and Spain, which grew deal count while the UK and France fell.
The week in six stories
- Ramp in early talks for a ~$1B Series G at a $60B valuation. Bloomberg reports the talks three months after the $750M Series F at $44B; annualised revenue passed $1.5B by June. Ramp declined to comment.
- Chime to acquire Stride Bank for $590M in cash. Stride, its bank partner for seven-plus years, becomes Chime Bank, N.A.; price is ~1.5x tangible book, closing expected H1 2027 pending OCC and Fed approval, with ~$100M of net synergies from removing sponsor-bank fees.
- Circle to acquire Tazapay for $400M in stock. The Singapore cross-border payments company handles $25B+ in annualised volume across 100+ markets, about 60% already in stablecoins; close expected 2027 subject to MAS approval.
- Nubank launches in the US. Deposits sit with FDIC-insured Lead Bank while the OCC charter for Nubank, N.A. completes; the account pays 3.50% APY, and Nu Global converts deposits into USDC or EURC for transfers across 35+ countries.
- FNZ raises $450M in new equity from existing shareholders. La Caisse, CPP Investments, Generation Investment Management and Motive Partners, following $650M from the same group in November 2025; the group has $2.5T of assets on platform.
- TRM Labs closes a Series C expansion at a $2B valuation. Led by Blockchain Capital, doubling the February Series C valuation; ARR has quadrupled in three years. Amount undisclosed.
Also: Harvey raises $550M at a $15.5B valuation co-led by Diffusion and Lightspeed; Bending Spoons to acquire Miro for $1.355B; Savvy Wealth raises $100M Series C at a $600M valuation led by Halo Fund; Kapital raises $125M from Tru Arrow Partners and Fasanara Capital; Grab in talks to buy a majority stake in Atome at a $2B+ valuation.
Funds. Seven new vehicles this week: CVC Secondary Partners ($10B, Secondary Opportunities Fund VI), Claret Capital Partners (€575M growth debt fund), Tether and Fasanara Capital ($400M StableFund, stablecoin-enabled private credit), Molten Ventures (£175M first close of a £350M growth fund), UK Government (£150M northern scaleup fund), Clean Growth Fund (£81.5M second close, fund II), The Techshop SGR (€43M first close, fund II, B2B AI).
All rounds
Equity
- Ramp — eyes $1B Series G at $60B valuation, reported
- FNZ — $450M new equity from existing shareholders
- Kapital — $125M equity and debt (Series C extension) from Tru Arrow Partners and Fasanara Capital, B2B financial institution, Mexico
- Savvy Wealth — $100M Series C at $600M valuation, AI-native RIA, led by Halo Fund
- Latitude — $35M Series A, stablecoin infrastructure
- OpenReserve — $25M seed led by a16z crypto, plus preliminary OCC approval for a full-service national bank
- Blee — $20M Series A, governance of AI-generated marketing content
- NAYLA — $17.9M pre-Series A, micro-business lending, Saudi Arabia
- fundcraft — €12M, fund operations platform
- Diameter Pay — $10M Series A co-led by CMT Digital and Lightspeed Faction
- HelmGuard AI — $7.3M, AI for governance, risk and compliance
- Olenbee — €7M, real-time employee benefits, France
- Creditstar Group — €4.6M from Kilde at €130M pre-money valuation
- Sav — $3.5M, AI-powered personal finance platform
- Outline — $3M, agentic FP&A platform
- Hello Clever — strategic round, undisclosed, approaching $100M ARR
VC funds
- CVC Secondary Partners — $10B, Secondary Opportunities Fund VI
- Claret Capital Partners — €575M growth debt fund
- Tether and Fasanara Capital — $400M StableFund, stablecoin-enabled private credit
- Molten Ventures — £175M first close of £350M growth fund
- UK Government — £150M northern scaleup fund
- Clean Growth Fund — £81.5M second close, fund II
- The Techshop SGR — €43M first close, fund II, B2B AI
Market news
Stablecoins and crypto rails
- Circle to acquire Tazapay for $400M in stock to expand USDC payments infrastructure
- Nubank launches in the US with cards, savings, crypto and stablecoins
- Block applies to launch national trust bank for crypto custody
- MoneyGram launches stablecoin backed card with Rain and Visa
- Coinbase files SEC notice registrations to offer single-stock perpetual futures in the US
- BVNK and Marqeta partner on stablecoin-backed card infrastructure
- Flex partners with Mesh to bring stablecoin deposits into business finance
- Robinhood takes minority stakes in Crypto.com and OG.com in a multi-year prediction markets deal
M&A
- Chime to acquire Stride Bank for $590M
- EQT agrees to acquire specialty (re)insurance broker McGill and Partners at a $2B valuation
- Bending Spoons to acquire Miro for $1.355B
- PayTabs Global to acquire Amazon Payment Services MENA in a $100M deal
- UniCredit acquires a minority stake in German fintech vc trade
Regulation and licensing
- Checkout.com launches US direct acquiring under its MALPB charter
- MoonPay secures a Dutch EMI licence to expand in Europe
- Revolut reportedly seeks two new licences in Luxembourg
AI and partnerships
- Plaid connects Grok to US users’ bank and investment accounts
- Ramp signs a strategic collaboration agreement with AWS and lists on AWS Marketplace
- Checkout.com to power Best Buy marketplace payments infrastructure
- Bank of America pilots a Zelle-UPI link for cross-border payments
- FC Bayern München names Wonderful as official enterprise AI partner
- SumUp becomes Manchester United’s official sleeve partner in a multi-year deal
- Ant Technology slowly building an HR stack
Expansion and operations
- Checkout.com US payment volume up 126% as North America expansion accelerates
- Deblock adds free embedded insurance for all customers
- PayPal files notice of 251 permanent job cuts at its San Jose headquarters
Founders to watch
Companies I’ve been talking with this week that I find interesting
- Finanz — Consumer finance learning app in Italy
- [Syeew](https://www.syeew.it/) — AI powerd ERP for multi point of sales chains
- Pegasus — Defense tech in Canada, selling to air defense both in CA and US
Let me know if you want to have a chat with them, always happy to make an intro.
Raising now
Space for GPs and solo GPs launching funds. Not paid. If you’re raising and want to be listed, message me on LinkedIn.
- Parallax Ventures — fintech, LatAm. Fund I: +50% IRR, 0.7x DPI. Raising Fund II. gennari@parallax.vc
- Founder Factor — YC-focused. Just closed investments in YC W26 and is expanding the current vehicle to double down on the batch.
- RedFish Capital Partners — private equity, Italian SMEs in growth and mature phases. 40%+ IRR track record, €200M+ AUM. Raising a new AIF with a soft commitment from the European Investment Fund. redfish.capital · investor.relations@redfish.capital
Performance figures are provided by the managers. Nothing here is investment advice.
Events, next 30 days
- Money 20/20 Middle East | Riyadh | 14-16 September (link Money 20/20 Middle East event details)
- European blockchain week | Barcelona | 16-17 September (link European Blockchain Convention event details)
- Nordic fintech week | Copenhagen | 23-24 September (link Nordic Fintech Week event details)
- Korea Blockchain Week 2026 | Seoul | September 29 - October 1 (link Korea Blockchain Week event details)
Later: Money20/20 USA, Las Vegas (18–21 Oct) · MERGE Madrid (27–29 Oct) · Hong Kong Fintech Week (2–6 Nov) · Africa Stablecoin Summit, Johannesburg (12–13 Nov) · Solana Breakpoint, London (15–17 Nov) · Singapore FinTech Festival (18–20 Nov) · Fintech Nerdcon, San Diego (19–20 Nov) · Bitcoin MENA, Abu Dhabi (7–8 Dec) · Abu Dhabi Finance Week (7–10 Dec) · TOKEN2049 Dubai (21–22 Apr 2027) · Money20/20 Asia, Bangkok (27–29 Apr 2027)
Want an event listed or sponsored? DM me.
Previous edition: Weekly update #148
Topics
Related funding
| Company | Round | Amount | Date |
|---|---|---|---|
| NAYLA Added · · Weekly update #149 | Pre-Series A | 17,900,000 USD | 7 September 2026 |
| Diameter Pay Added · · Weekly update #149 | Series A | 10,000,000 USD | 7 September 2026 |
| OpenReserve Added · · Weekly update #149 | Seed | 25,000,000 USD | 7 September 2026 |
| FNZ Added · · Weekly update #149 | 450,000,000 USD | 1 September 2026 |