Weekly update #143
The latest news from the fintech and VC ecosystems
Welcome to this edition of the weekly newsletter. The idea behind this is to gather all the information in the startup ecosystem in one place, with a special focus on the fintech market and the VC industry.
The latest episode of Builders was released last week! In this episode, I sit down with Kristy Kim, CEO and founder of TomoCredit. You can watch the full episode here on YouTube, or listen to it here on Spotify or here on Apple Podcast. Here a short clip from the video:
TomoCredit, a San Francisco fintech company focused on expanding access to financial services through technology. Since launching the business in 2019, she has led its development and the introduction of TomoIQ, an AI-powered financial advisor designed to support consumers in managing their financial lives.
Before founding TomoCredit, Kristy worked in business development at Credit Sesame and held investment roles at Kenetic, Oasis Labs and Vault12. She previously founded and led a venture-backed e-commerce company and served as Head of Global Business Development at Com2us Corporation, where she worked on international growth initiatives. Earlier in her career, she advised technology companies on mergers and acquisitions at J. Moore Partners, which later merged with B. Riley Financial.
Kristy is also a member of the Forbes Finance Council, where she contributes perspectives on fintech and personal finance. She holds an MBA from the University of California, Berkeley’s Haas School of Business and has served as a lecturer at Haas, teaching entrepreneurship and blockchain.
With her, we will talk about credit scoring in the US, fintech services and the importance of being in San Francisco to build your fintech startup.
Coming back to us, this week I’ve been reading a very interesting report, the “Stablecoin - pulse of digital money”, monthly review of the stablecoin market. The report is a monthly analysis of stablecoin growth, transaction activity, market structure, capital flows and the key indicators driving the evolution of digital money. Here my main takeaways:
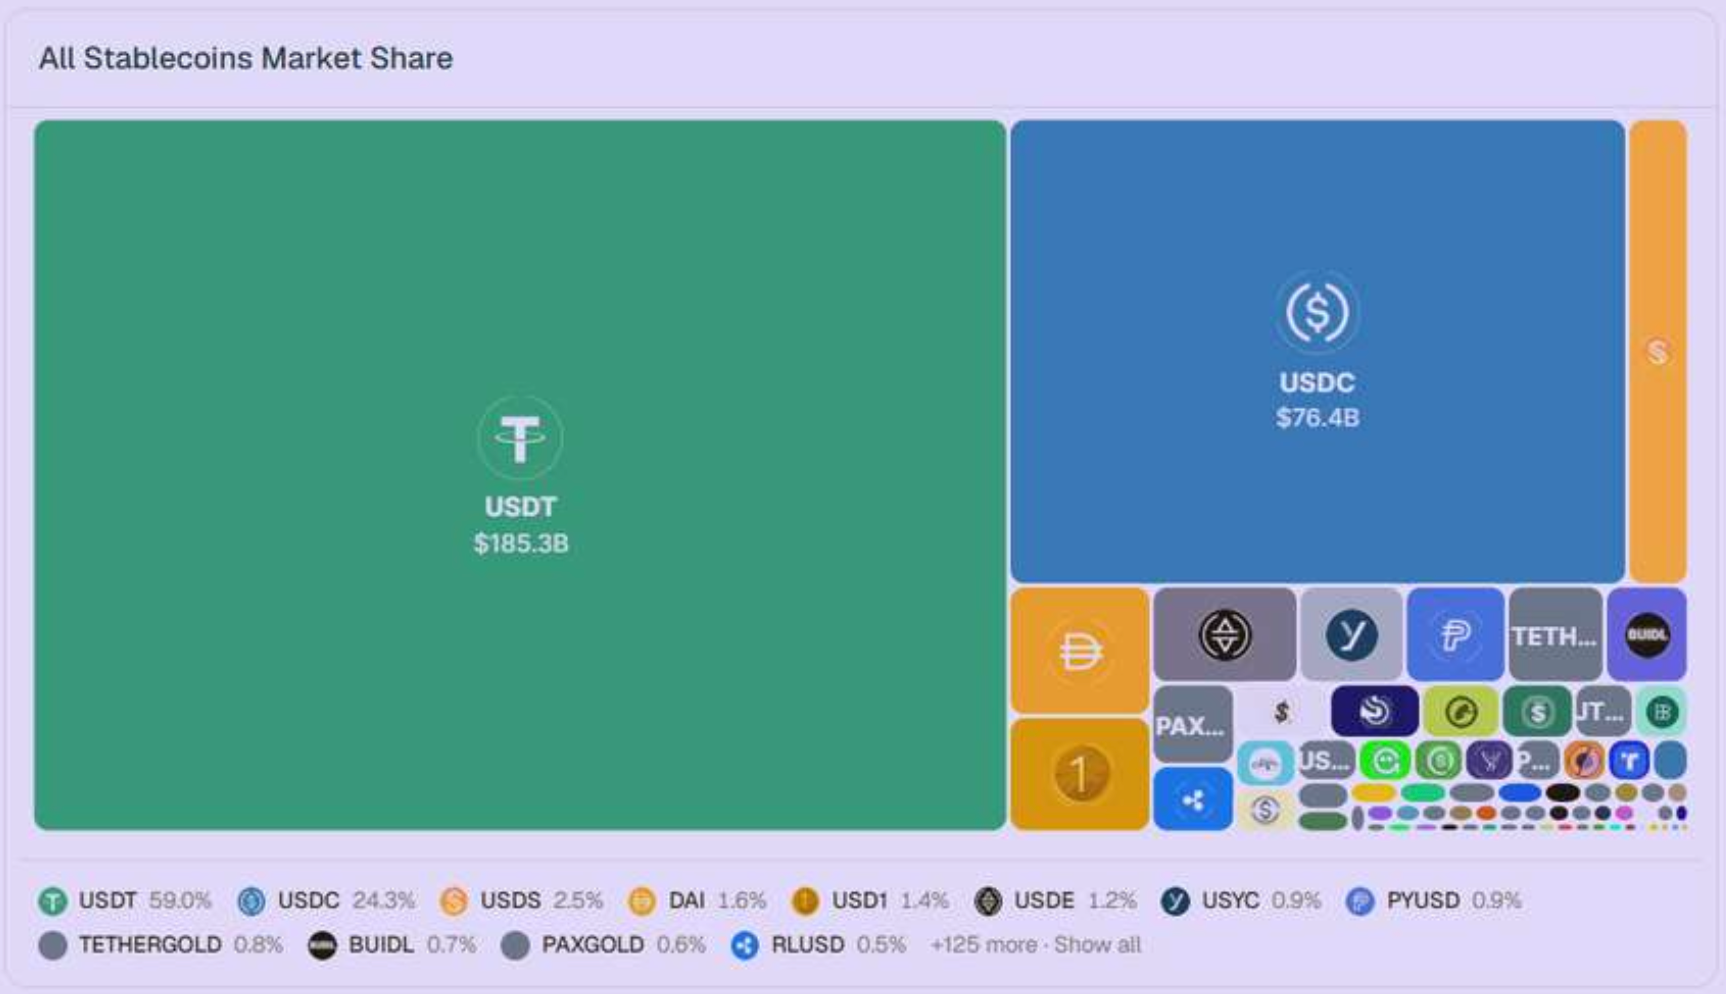
The stablecoin market remains highly concentrated, with Tether.io’s USDT and Circle’s USDC controlling more than 80% of total supply. USDT leads the sector with approximately 59% market share and over $185 billion in circulation. USDC follows with more than $76 billion, representing roughly 24% of the market.
Beyond these two dominant assets, the ecosystem is considerably more fragmented. Stablecoins such as USDS, DAI, USD1, USDe, PYUSD, RLUSD, BUIDL, and many smaller alternatives continue to develop specific use cases and market positions. However, none currently has the scale, liquidity, or adoption needed to compete directly with USDT and USDC.
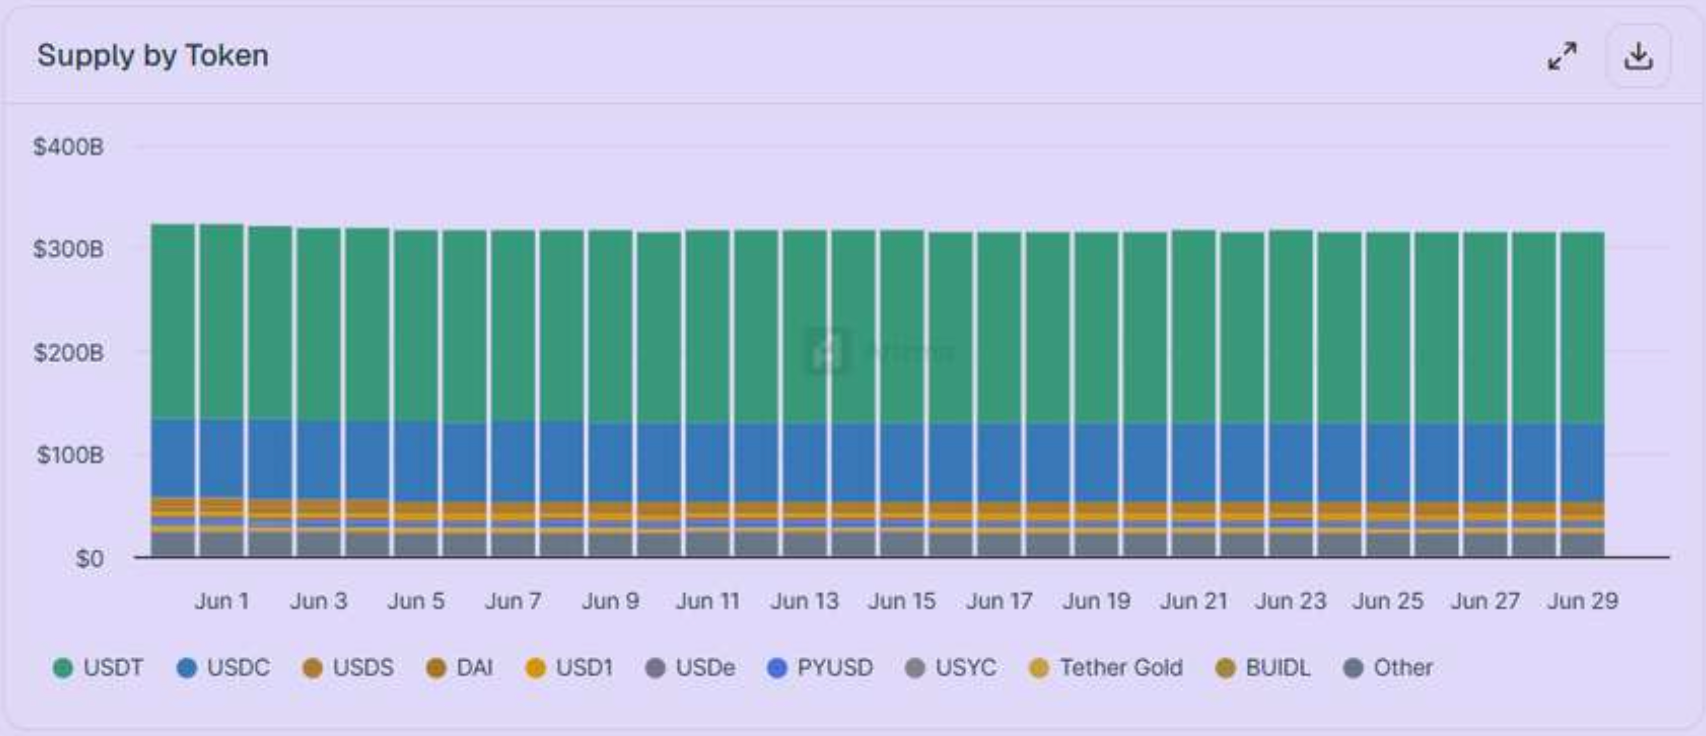
Stablecoin issuance remained notably steady throughout June, with total circulating supply fluctuating within a relatively narrow range. This contrasts with earlier periods of rapid expansion and suggests that market growth is becoming more closely linked to genuine transaction demand rather than speculative issuance.
Capital continues to enter the stablecoin ecosystem, but it is being deployed more efficiently. Instead of driving excessive supply growth, new inflows appear to support practical use cases, liquidity needs, and payment activity.
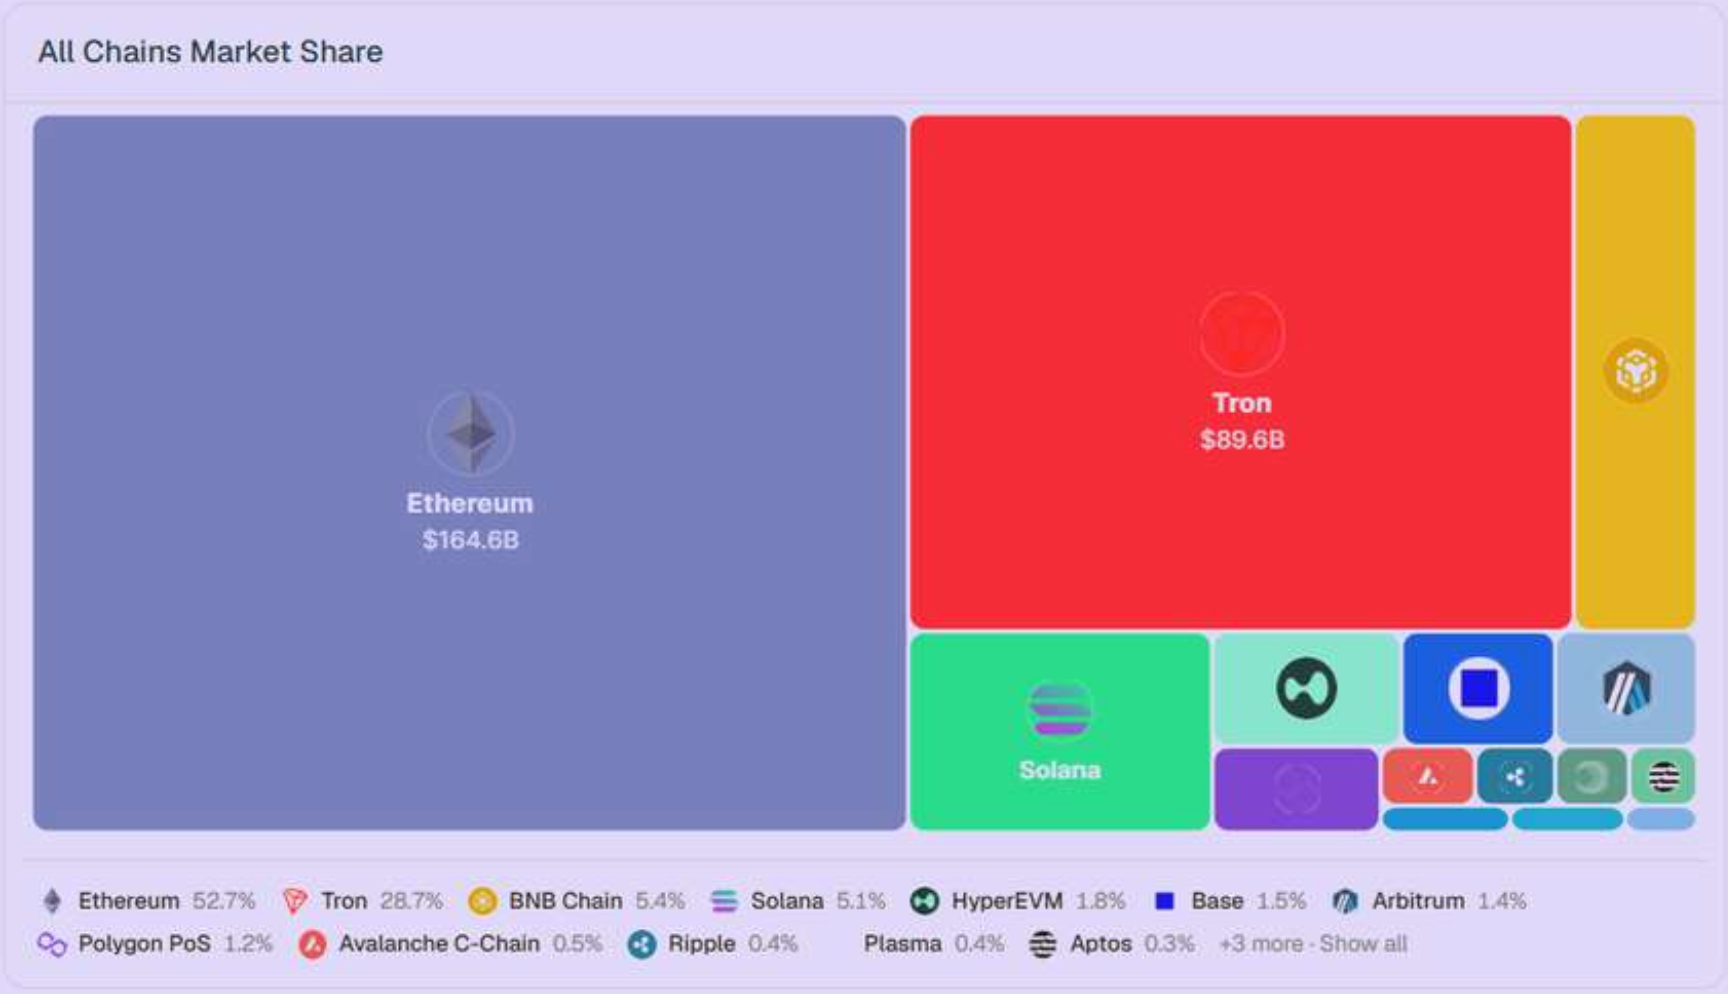
Stablecoin distribution across blockchains remains broadly consistent. Ethereum continues to hold the largest share of global stablecoin liquidity, while Tron remains a major settlement network for international transfers.
At the same time, Solana, Base, BNB Chain, HyperEVM, Arbitrum, and other emerging networks are gaining importance. Their continued expansion reflects the industry’s gradual shift toward a more diversified multi-chain ecosystem, where stablecoin activity is distributed across several networks rather than concentrated on a single blockchain.
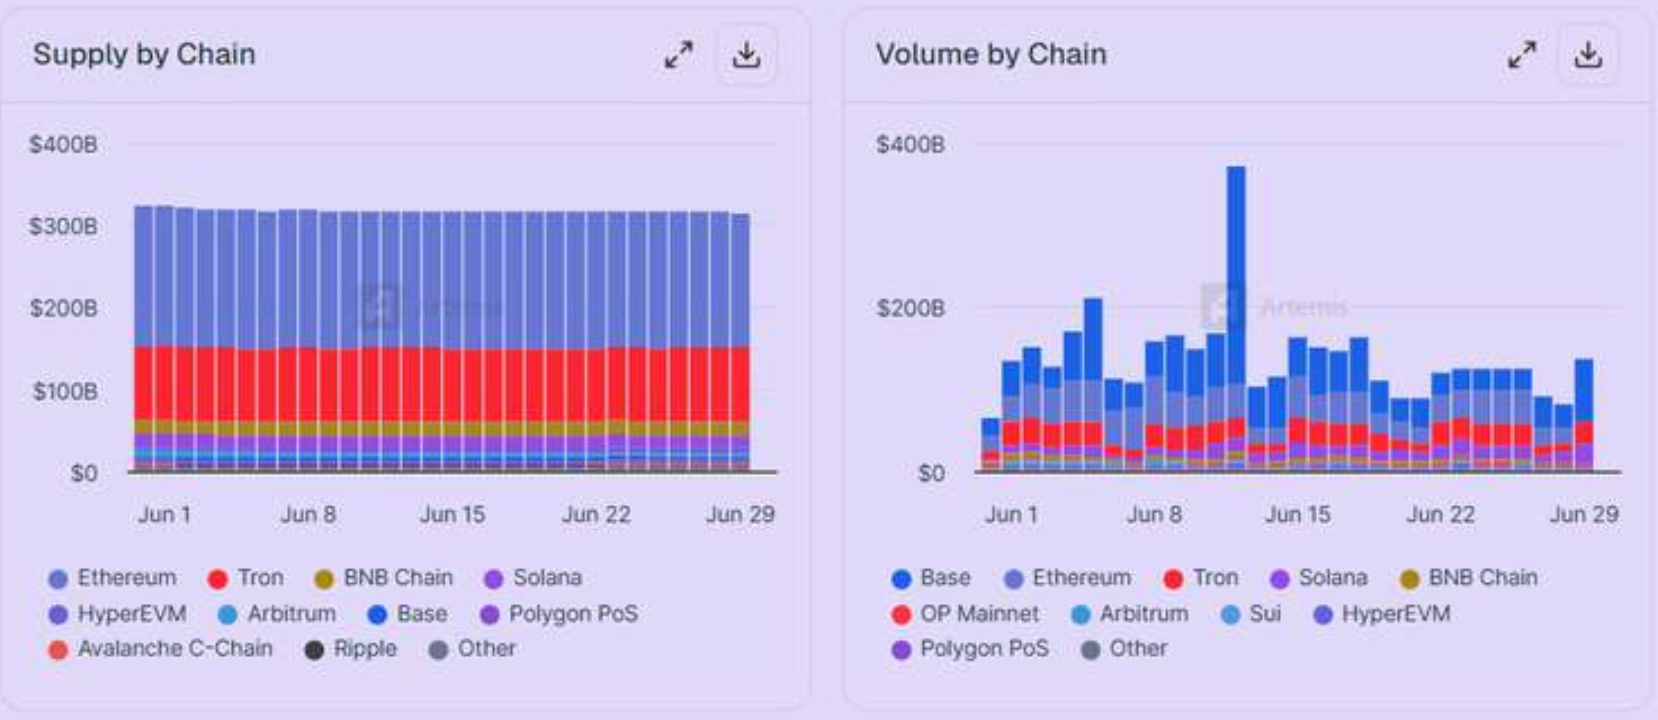
Stablecoin supply and transaction activity show that blockchains are increasingly serving different functions. Ethereum remains the leading network for holding stablecoin liquidity, while Base and Solana are processing a growing share of transaction volume. Tron continues to play an important role in cross-border payments due to its efficiency as a settlement network.
Rather than competing for the same use cases, blockchain networks are gradually becoming more specialized. Each chain is developing a distinct position based on liquidity, transaction capacity, cost, and settlement efficiency, contributing to a more segmented and mature multi-chain ecosystem.
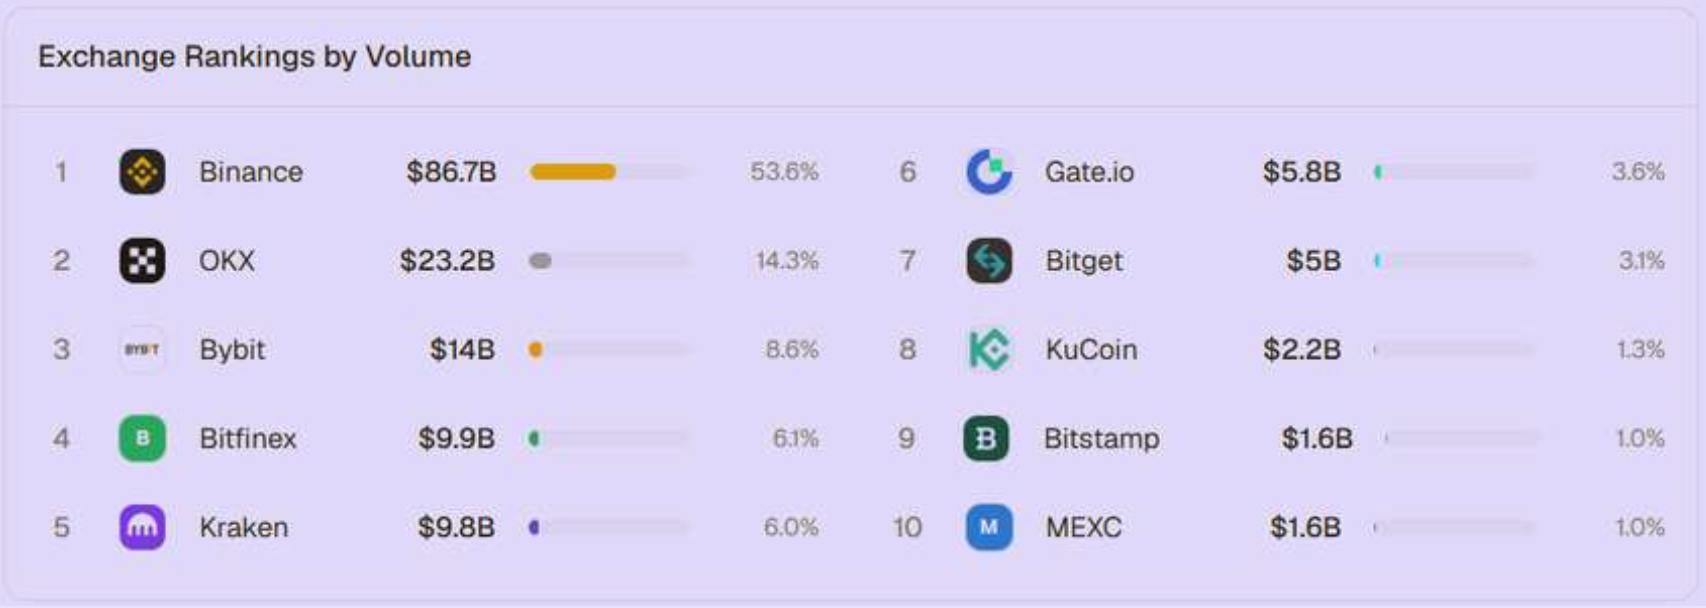
Stablecoin activity became more geographically balanced in June. Europe accounted for the largest share of tracked transactions, closely followed by North America, while Asia remained a major contributor. Latin America, Africa, and Oceania also continued to expand their presence as stablecoins gained importance for remittances, merchant payments, and cross-border commerce. This broader distribution suggests that adoption is becoming less concentrated in a few established regions.
Trading activity, however, remains dominated by a limited number of global exchanges. Binance processed the largest stablecoin trading volume by a significant margin, followed by OKX, Bybit, Bitfinex, and Kraken. While stablecoin usage is spreading across regions and use cases, exchange liquidity continues to be concentrated among the industry’s largest trading platforms.
But let’s take a closer look at the main news of the last seven days, Stripe becomes the official partner of The Ryder Cup, Revolut partners with OpenAI to offer ChatGPT in their paid plans, Wise was denied a banking license in the US and X money is now available for all US consumers. But also, Revolut is now the official front shirt sponsor of Como 1907 and landed an approval for a Greece branch, Scalapay expands partnership with Stripe across 30 new countries, Coinbase launches AI agentic payments for businesses and Western Union shuts down its digital bank. In the VC market, Italian Founders Fund closes a new $100M fund to invest in italian founders, Framework Ventures closes a $400M fourth fund, and Highland Europe closes a crazy new $1.1B fund. And finally, some interesting funding rounds from fintech startups like Ábaco, Addi, PEX, LemonEdge, InvestFi, Olomon and many others.
Let’s take a closer look:
Rounds
- Ábaco raises $53 million to expand SME financing in Latam
- Addi secures more than $630M to scale digital credit in Colombia
- World Foundation raises $52.5 million to scale world ID
- 9fin completes first employee share sale after $170 million raise
- PEX secures $160 million to scale payments and finance automation
- LemonEdge raises $21 million to modernise private market fund accounting
- iwoca secures £250 million facility amid £1 billion sale reports
- SiloReal raises $2.5 million to scale digital agricultural asset verification
- Centralize raises $15 million to build a deal GPS for enterprise sales
- Plend | B Corp secures up to €58.3 million to expand responsible lending
- Olomon raises $2.6 million to build a financial system of record for households
- Epic Markets raises $10 million to build multi asset brokerage platform for the UAE
- Freehand raises $75 million for autonomous supply chain AI
- InvestiFi raises $20 million to expand embedded investing
- Harvey secures strategic investment from Goldman Sachs and J.P. Morgan
VC funds
- Italian Founders Fund closes a €100 million fund to invest on Italian early stage startups
- UK pension providers plan £1 Billion tech scale up fund
- Framework Ventures closes $400 million fourth fund
- Highland Europe raises €1.1 billion for sixth growth fund
- Jump Capital closes $350M venture fund to invest in AI infrastructure and crypto
News on the market
- Stripe becomes official payment partner of The Ryder Cup
- Revolut becomes Como 1907 front of shirt partner
- Revolut opens private markets to retail investors in Italy
- Wise denied US banking license as shares fall 7%
- Coinbase launches AI agent payments through stablecoin infrastructure
- Circle acquires IBM Blockchain patents to lead US IP holdings
- Revolut explores UK store as physical banking models evolve
- X Money just went live for US users!
- MoonPay and Tempo partner to expand stablecoin payments
- Robinhood explores Crypto.com partnership for prediction markets
- Xero and Revolut Business connect cross border finance in New Zealand
- Western Union to shut down its digital bank
- Bloomberg acquires Canoe Intelligence to expand private markets capabilities
- Pemo secures central bank approval to expand SME financial services
- Credito Lombardo Veneto S.p.a. backs Satispay’s pay in 3 with €30 million securitisation
- Legora acquires Wexler following $600 million series D
- Revolut partners with OpenAI to offer ChatGPT access to customers
- Starling Bank enters telecoms with embedded eSIM plans in partnership with Gigs
- Increase acquires Twin City Bank to build a fintech native banking platform
- GoCardless and anvil automate payments for telecom and IT providers
- Scalapay expands Stripe integration across more than 30 countries
- Remitly launches global card that holds USDC
- Revolut gets approval for a local branch in Greece and to release GR Ibans
And here some useful resources for everyone involved in the ecosystem:
Events you don’t want to miss
- Global Fintech Fest 2026 | Mumbai | 9-11 September (link here)
- Money 20/20 Middle East | Riyadh | 14-16 September (link here)
- European blockchain week | Barcelona | 16-17 September (link here)
- Nordic fintech week | Copenhagen | 23-24 September (link here)
- Korea Blockchain Week 2026 | Seoul | September 29 - October 1 (link here)
- TOKEN2049 | Singapore | 7-8 October (link here)
- Money 20/20 USA | Las Vegas | 18-21 October (link here)
- MERGE Madrid 2026 | Madrid | October 27-29 (link here)
- Hong Kong fintech week | Hong Kong | 02-06 November (link here)
- Africa Stablecoin Summit 2026 | Johannesburg | 12-13 November (link here)
- Solana Breakpoint 2026 | London | 15-17 November (link here)
- Singapore FinTech Festival 2026 | Singapore | 18-20 November (link here)
- Fintech Nerdcon | San Diego | 19-20 November (link here)
- Bitcoin MENA 2026 | Abu Dhabi | 7-8 December (link here)
- Abu Dhabi Finance Week 2026 | Abu Dhabi | 7-10 December (link here)
- TOKEN2049 Dubai 2027 | Dubai | 21-22 April, 2027 (link here)
- Money20/20 Asia 2027 | Bangkok | 27-29 April, 2027 (link here)
You have a cool event you want to mention or to sponsor? Feel free to send me a DM.
Founders to watch in fintech
I also wanted to start shining a light on the most interesting fintech founders out there, so I thought to start sharing how I look for ideas to invest on. Every week, I will start sharing the most interesting founders in fintech, divided per area.
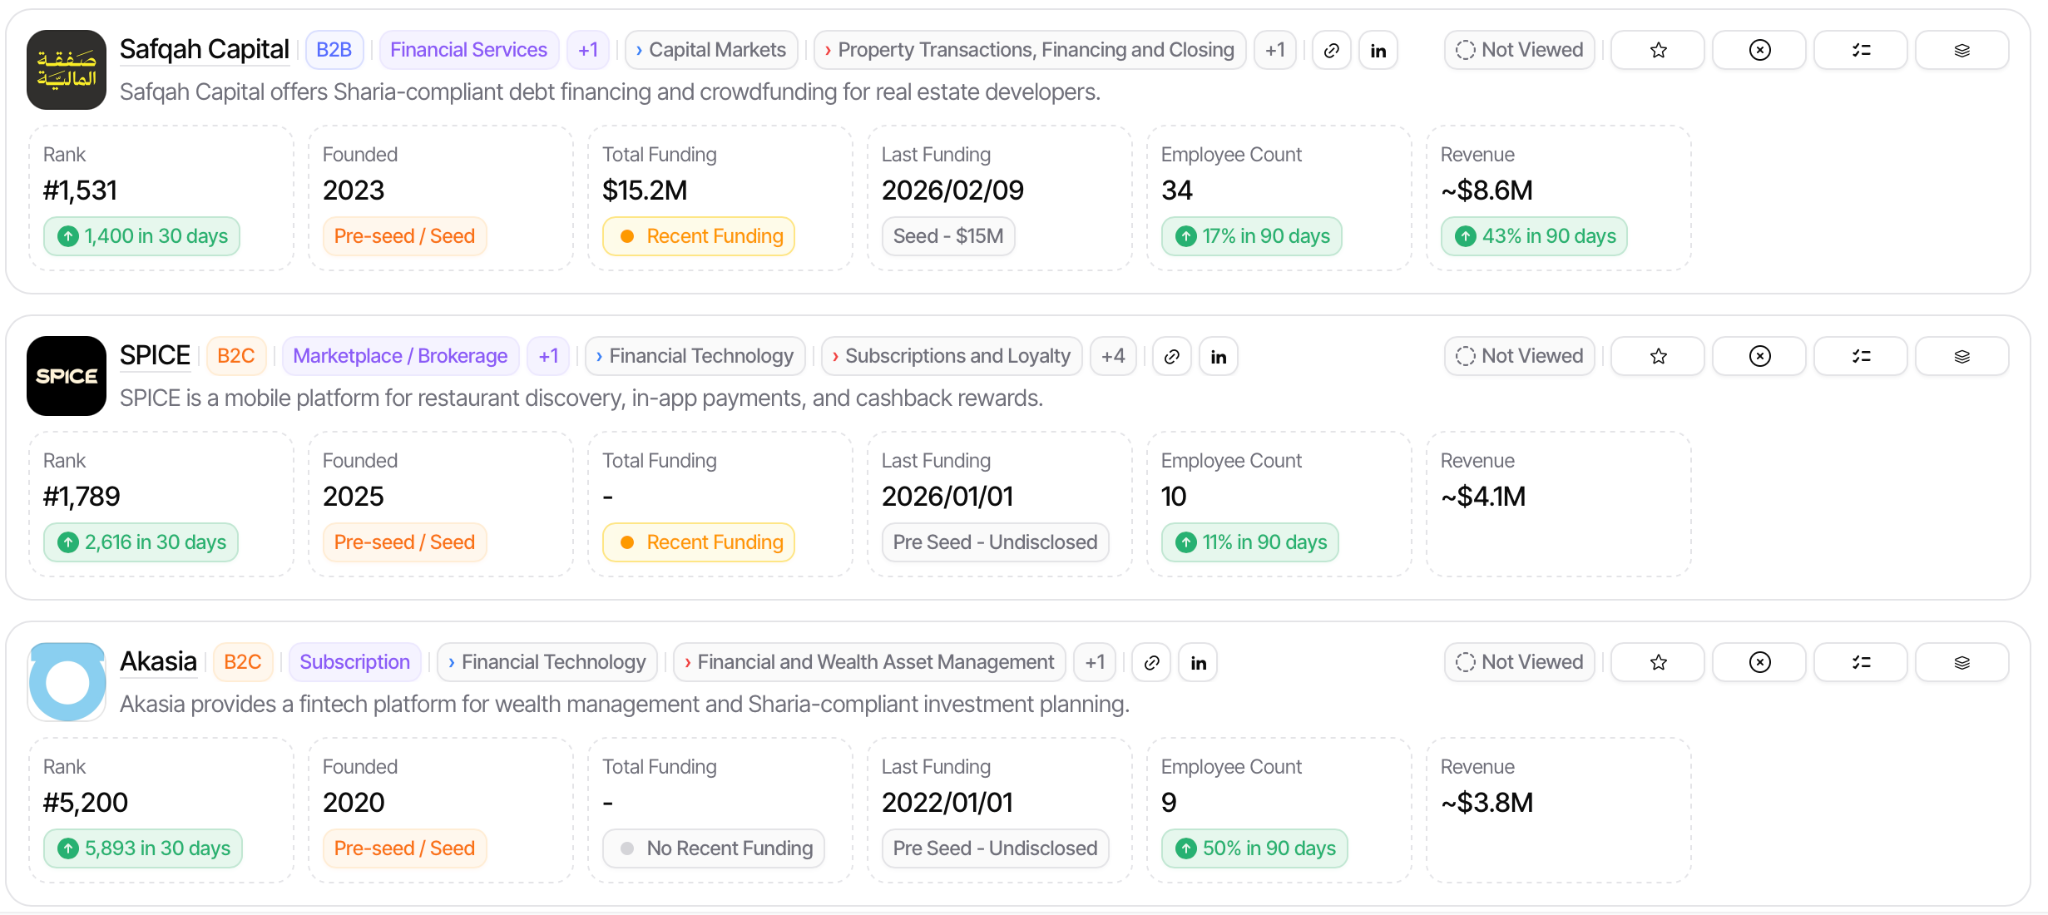
This week I took a look at the most interesting fintech startups in Saudi Arabia, focusing on companies bootstrapped in the early stage (pre-seed and seed).
I usually use Spectre to scout for new ideas, the team is great and they also give me a free account once they learned I was a fan of the product. So if you wanna take a look at it, you can find it here.
VCs and PEs raising new funds now
I would like to leave this part of the newsletter as space for VC and solo GP that are launching new funds right now. I frequently speak with GPs and LPs, and I like the idea of giving them a showcase where to announce what they are doing. Here the new funds raising right now that I have been talking with:
- Parallax Ventures, a fintech VC fund focused on Latam. They closed Fund I with a strong +50% IRR and 0.7x DPI, and are now raising Fund II. Take a look here if you want to know more or reach out directly to the GP at gennari@parallax.vc for details.
- Founder Factor, VC focused on YC companies, that just closed investments on the latest YC W26. They are expanding the current vehicle to double down on the current batch. You can take a look here if you are interested.
- RedFish Capital Partners, a private equity investor focused on Italian SMEs in growth and mature capital phases, with a track record exceeding 40% IRR and with over €200M in Assets. Currently raising its brand new AIF, which has already secured a soft commitment from the European Investment Fund (EIF). You can check them out at redfish.capital or contact the team at investor.relations@redfish.capital.
Overall, very interesting to see where the VC ecosystem is heading recently, between new emerging managers, solo GP and micro funds.
Always happy to support if I can! If you are raising a fund and you want to be listed here send me a message on Linkedin.
And finally, take also a look at the last edition of the newsletter, Weekly update #142
Topics
Related funding
| Company | Round | Amount | Date |
|---|---|---|---|
| Addi Added · · Weekly update #143 | 630,000,000 USD | 27 July 2026 | |
| Plend Added · · Weekly update #143 | Credit facility | 20,000,000 GBP | 28 July 2026 |
| Iwoca Added · · Weekly update #143 | Debt facility | 250,000,000 GBP | 29 July 2026 |
| Epic Markets Added · · Weekly update #143 | Pre-seed | 10,000,000 USD | 21 July 2026 |
| Ábaco Added · · Weekly update #143 | Seed | 2,600,000 USD | 22 July 2026 |
| Freehand Added · · Weekly update #143 | Series B | 75,000,000 USD | 29 July 2026 |
| Centralize Added · · Weekly update #143 | Series A | 15,000,000 USD | 29 July 2026 |
| PEX Added · · Weekly update #143 | Debt + equity | 160,000,000 USD | 28 July 2026 |
| World Foundation Added · · Weekly update #143 | 52,500,000 USD | 27 July 2026 | |
| LemonEdge Added · · Weekly update #143 | Series A | 21,000,000 USD | 29 July 2026 |
| SiloReal Added · · Weekly update #143 | 2,500,000 USD | 29 July 2026 | |
| Olomon Added · · Weekly update #143 | Pre-seed | 2,600,000 USD | 28 July 2026 |
| Harvey Added · · Weekly update #143 | Strategic | 28 July 2026 | |
| InvestiFi Added · · Weekly update #143 | 20,000,000 USD | 29 July 2026 |