Weekly update #142
The latest news from the fintech and VC ecosystems
Welcome to this edition of the weekly newsletter. The idea behind this is to gather all the information in the startup ecosystem in one place, with a special focus on the fintech market and the VC industry.
The latest episode of Builders was released last week! In this episode, I sit down with Eridian Alpha, product strategy lead at ETHGas . You can watch the full episode here on YouTube, or listen to it here on Spotify or here on Apple Podcast.
Eridian is the product strategy lead at ETHGas and an Ethereum builder focused on blockspace infrastructure, validator economics and the development of a real-time Ethereum network. At ETHGas, Eridian works on technology designed to transform Ethereum blockspace into a predictable and tradable commodity, supporting instant transaction settlement and applications that can shield users from volatile gas costs.
A long-standing participant in the Ethereum staking ecosystem, Eridian has operated solo validators and contributed educational resources for node operators, developers and community stakers. Eridian co-created the EthStaker Knowledge Base and maintains an extensive collection of open-source documentation covering Ethereum infrastructure, Solidity development, smart-contract security, MEV and decentralised finance.
Eridian has also built projects including High Signal, an engagement and reputation platform for Ethereum communities, and Pool Playground, an interactive tool for understanding decentralised exchange mechanics. Through technical development, education and ecosystem participation, Eridian works to make Ethereum faster, more accessible and easier to operate.
With him, we will talk about the current infrastructure behind many popular crypto projects, but about the future of the industry and the main trend in blockchain today.
Coming back to us, this week I’ve been reading a very interesting report, the “Venture Capital report - Italy Q2 and H1 2026” by Growth Capital and Italian Tech Alliance. The report is an overview on VC investments in the Italian startup ecosystem, divided by stage, amount and sector, shining a light on one of the most interesting emerging ecosystems in Europe. Here my main takeaways:
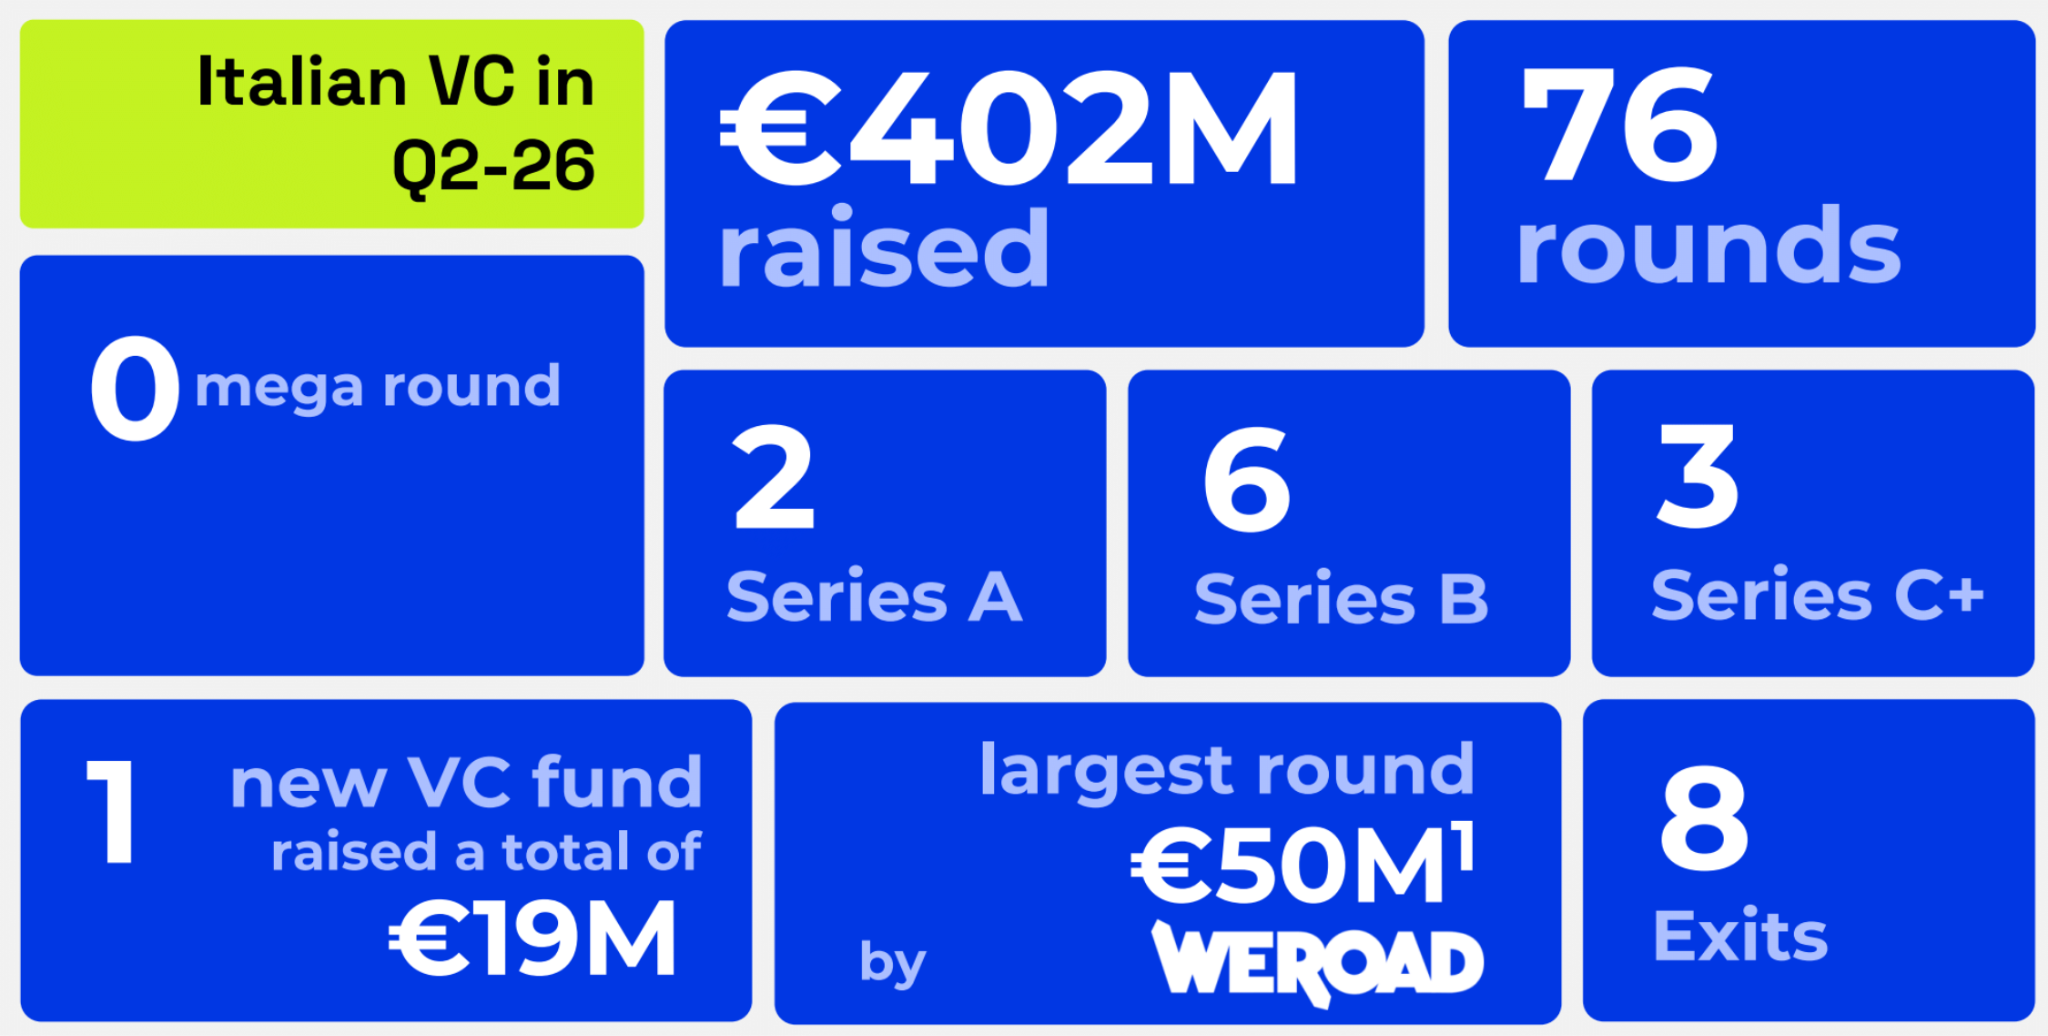
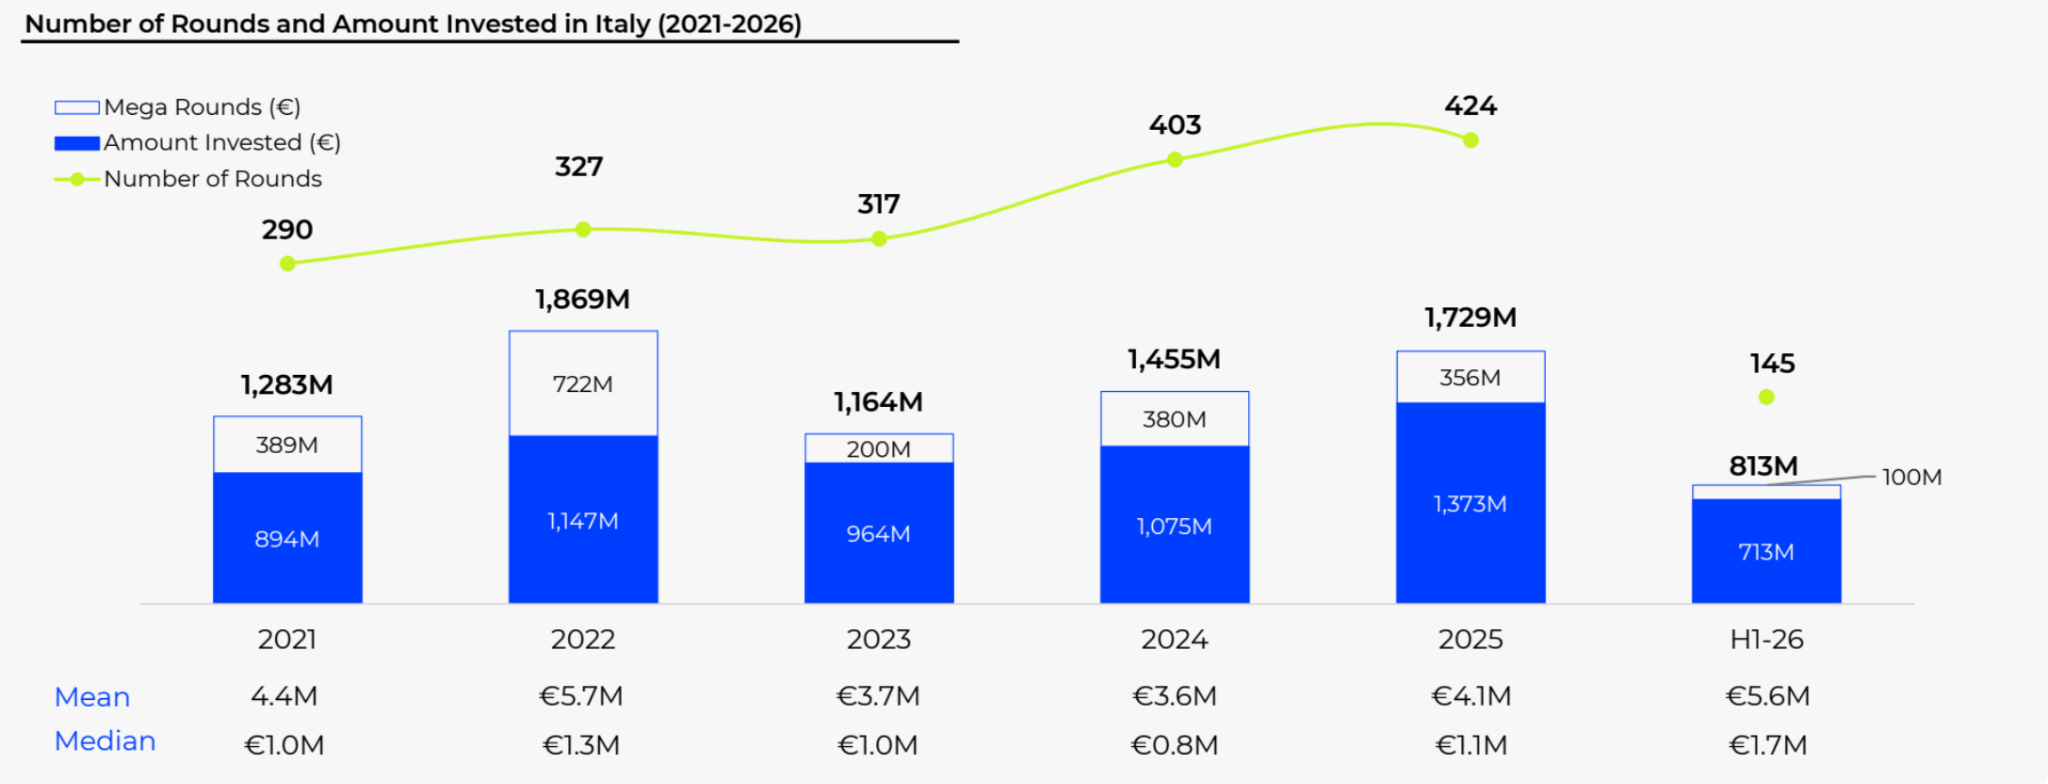
Q2 closed at €402M across 76 rounds, against €411M and 69 rounds in Q1. Strip out the mega rounds and Q2 2026 becomes the second best quarter ever recorded in Italy, with both average and median round size jumping.
That is the part I care about. A market that deploys the same capital over fewer, larger deals is not shrinking, it is repricing. Three new funds also closed in the semester for a combined €104M. Modest, but it keeps domestic dry powder topped up.
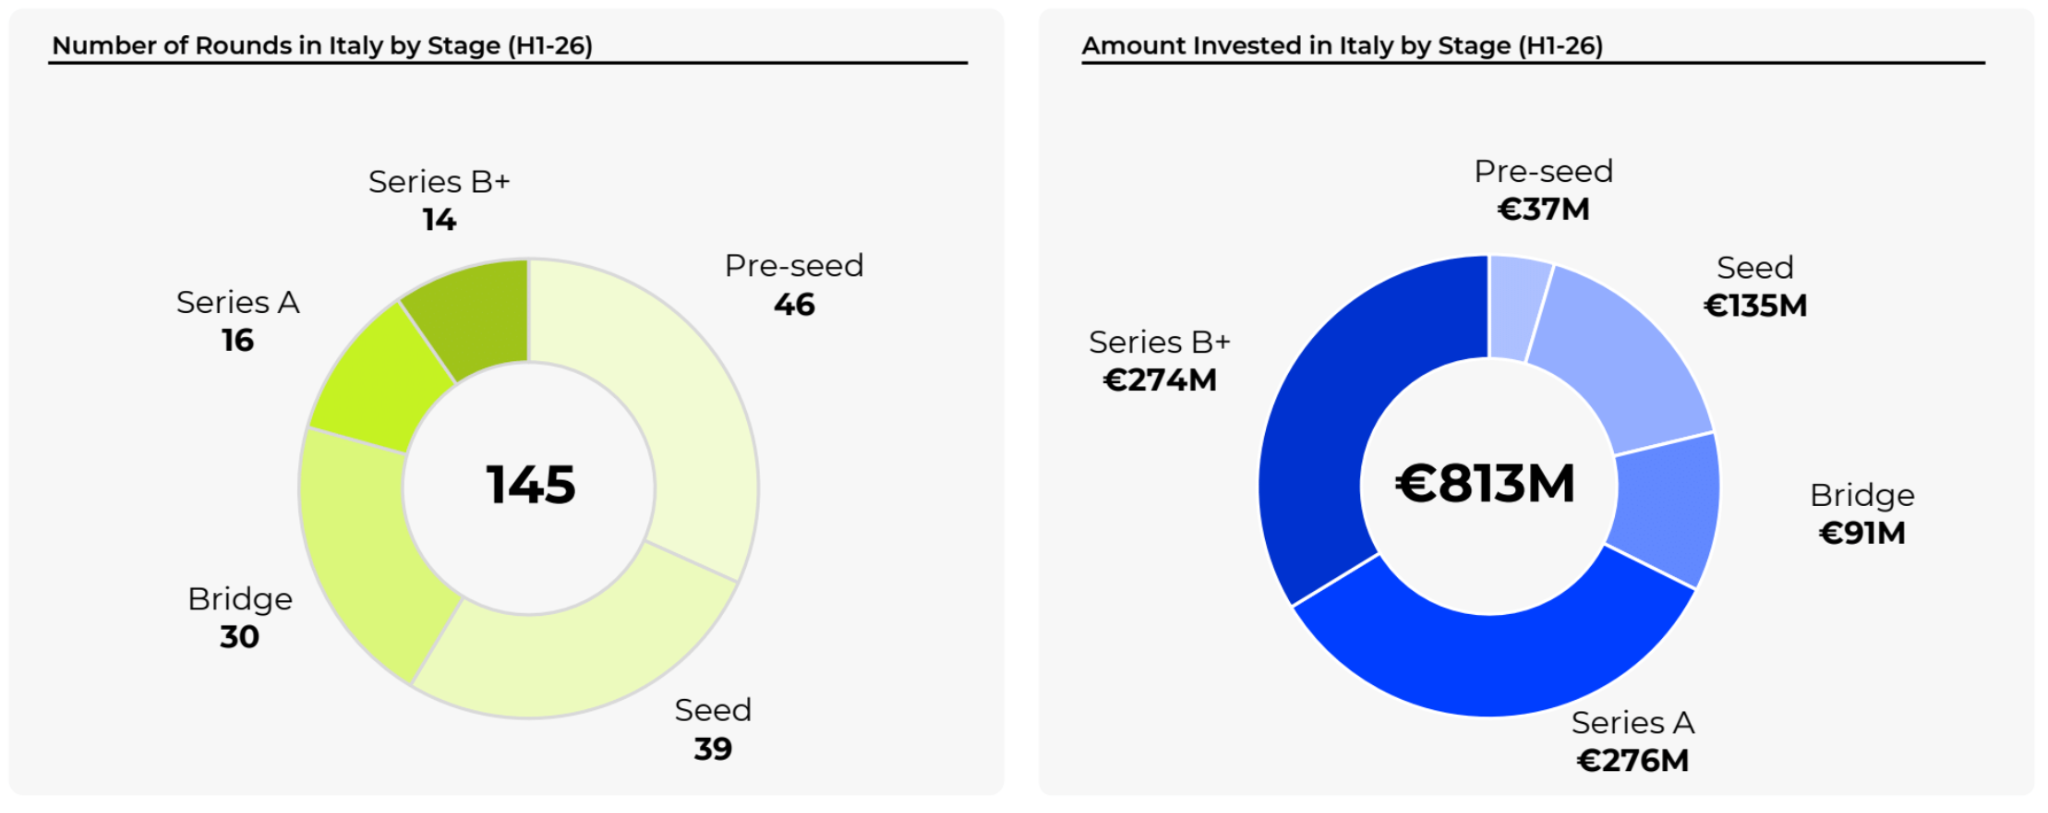
Pre-seed and seed still account for 59% of all rounds, but only €172M of capital (€37M and €135M respectively). Series A (€276M) and Series B+ (€274M) together take 68% of the money from just 21% of the transactions.
This is the barbell Italy has been missing for years, and it is finally showing up. The uncomfortable side is the other end. Pre-seed and seed deal counts have been contracting for several quarters now. We are fixing the late stage while the top of the funnel gets thinner, and you cannot run a Series A market in 2029 without a seed market in 2026.
By sector, software (which includes AI and machine learning) is the most active vertical, with 25% of all rounds and €214M raised. Smart city follows at €165M and fintech at €156M. Together they absorb close to two thirds of everything invested, with deeptech (€97M) and lifescience (€57M) completing the top five.
The fintech number deserves an asterisk. It leads on capital almost entirely thanks to Rent2Cash and its €100M+ round, a rental advance business that sits closer to structured finance than to classic venture-backed software. Take that out and Italian fintech had a quiet semester. AI and ML led on deal count instead, with 15 rounds, which is the healthier kind of leadership.
The largest Q2 deals were WeRoad (€50M Series C), Smartness (€47M Series B), Lexroom (€43M Series B), Niulinx (€38M seed) and MDOTM (€24M growth). A €38M seed round for autonomous driving would have been unthinkable in Italy three years ago.
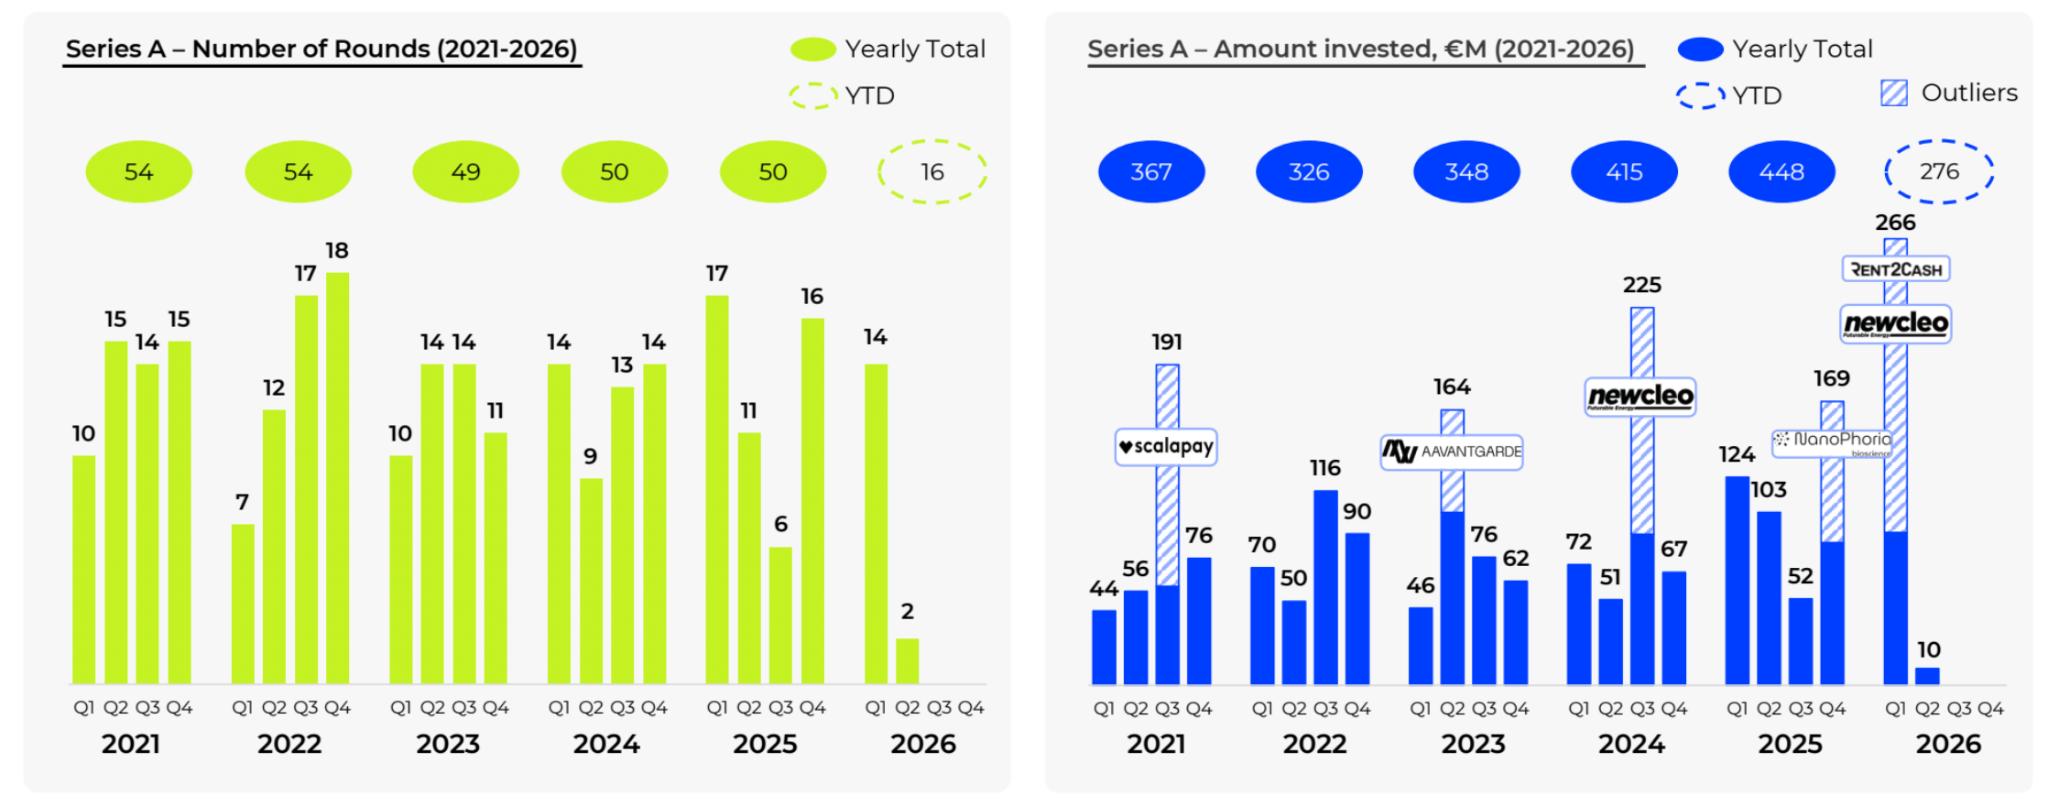
Zooming out to Europe, the picture is one of extreme concentration. €44B raised across 5,330 rounds, the strongest half by value since 2022, with AI taking 60% of all capital deployed. Mega rounds were just 1.3% of transactions but captured 64% of the money. The UK alone raised €20B, 46% of the European total, more than France, Germany, Sweden and Switzerland combined.
Italy sits at roughly 1.8% of European capital. That gap is the benchmark that matters, and it is not closing quickly. France is mobilising €13B of institutional money through the third phase of the Tibi initiative, aiming at €15B by 2030, explicitly to back scaleups and IPOs.
But let’s take a closer look at the main news of the last seven days. Revolut expanded Polish operations with a Varsaw office and get a banking license in Australia, Mollie commits $100M to Italian expansion, Apple partners with Klarna for device lease to own program and Stripe explores $10B acquisition of OpenRouter. But also, OpenAI adds Nubank founder David Vélez and BNY CEO Robin Vince to its advisory board, PayPal rejects Stripe acquisition offer, Viva.com integrates Wero as payment method and Ramp releases stablecoin accounts and payments to all customers. In the VC market, British Business Bank committed $100M to a new aerospace fund, Resist.UA launched a $50M defence tech fund and DIMENSION Capital closed a $800M third fund. And finally, some very interesting funding rounds from fintech startups like Ant International, Cashea, Cordant, Natural, Augustus, Zeom and many others.
Let’s take a closer look:
Rounds
- Pinbank Brasil raises $19.6M to expand acquiring operations
- Zalando joins Sereact’s $116M Series B
- CuspAI raises €393.2M at €2.2B valuation
- Natural raises $30M to build payment infrastructure for AI agents
- Augustus raises $180M at $1B valuation to build a global dollar bank
- Ant International raises $1.2B series A to expand global payments
- Cashea secures $100M to expand credit access in Venezuela
- Djamo targets $40M Series C to accelerate West African expansion
- Veriqus Partners raises $40.2M to build an AI enabled wealth management platform
- Fina secures $75M Shariah compliant facility from Fasanara Capital
- Fawry secures $10.8M to expand digital SMEs lending in Egypt
- Zeom raises $2.7M to bring global investing to Brazil’s mass market
- Cordant raises $8M to build a command center for financial infrastructure
VC funds
- British Business Bank plans £100M Aerospace fund
- Resist.UA launches €50M European fund for Ukrainian defence technology
- DIMENSION Capital raises $800M third fund to invest on intersection of science and computing
News on the market
- Revolut expands Polish operations with new Warsaw office and 300 jobs
- Contents acquires Spanish fintech Balio in sixth European deal
- Mollie commits €100M to expand in Italy
- OpenAI adds BLIK as recurring payments method inside ChatGPT
- France blocks Polymarket over illegal gambling concerns
- Chime launches integrated investing for millions of US members
- Revolut secures full Australian banking licence
- Samsung Electronics launches its first US credit card with Barclays and Visa
- Nubank is getting its own banking license in Brazil
- MoonPay acquires Glide to expand crypto deposit infrastructure
- Affirm brings B2B installment payments to Amazon business
- LemFi and BVNK move cross border payments onto stablecoin rails
- Apple reportedly partners with Klarna for device lease to own program
- Revolut just confirmed $115B valuation in secondary share sale
- PayPal rejects $53.4B offer from Stripe and Advent
- India and Spain are talking about UPI-Bizum payment interoperability
- Talos integrates Kalshi Markets into institutional trading infrastructure
- Sifted acquires startup and venture platform Onstage
- Viva.com joins EPI Company and adds Wero across European markets
- Ripple invests in Notabene to scale compliant stablecoin payments
- Ramp makes stablecoin accounts and payments available to all customers
- Expensify and Marqeta partner to expand corporate card offering across EU
- OpenAI adds Nubank founder David Vélez and BNY CEO Robin Vince to its boards
- Al Etihad Payments and Mastercard launch UAE’s first co-badged credit card
- zerohash and Marqeta partner to bring stablecoin spending to global card networks
- Stripe explores $10B acquisition of OpenRouter
And here some useful resources for everyone involved in the ecosystem:
Events you don’t want to miss
- Money 20/20 Middle East | Riyadh | 14-16 September (link here)
- European blockchain week | Barcelona | 16-17 September (link here)
- Nordic fintech week | Copenhagen | 23-24 September (link here)
- Money 20/20 USA | Las Vegas | 18-21 October (link here)
- Hong Kong fintech week | Hong Kong | 02-06 November (link here)
- Fintech Nerdcon | San Diego | 19-20 November (link here)
You have a cool event you want to mention or to sponsor? Feel free to send me a DM.
Founders to watch in fintech
I also wanted to start shining a light on the most interesting fintech founders out there, so I thought to start sharing how I look for ideas to invest on. Every week, I will start sharing the most interesting founders in fintech, divided per area.
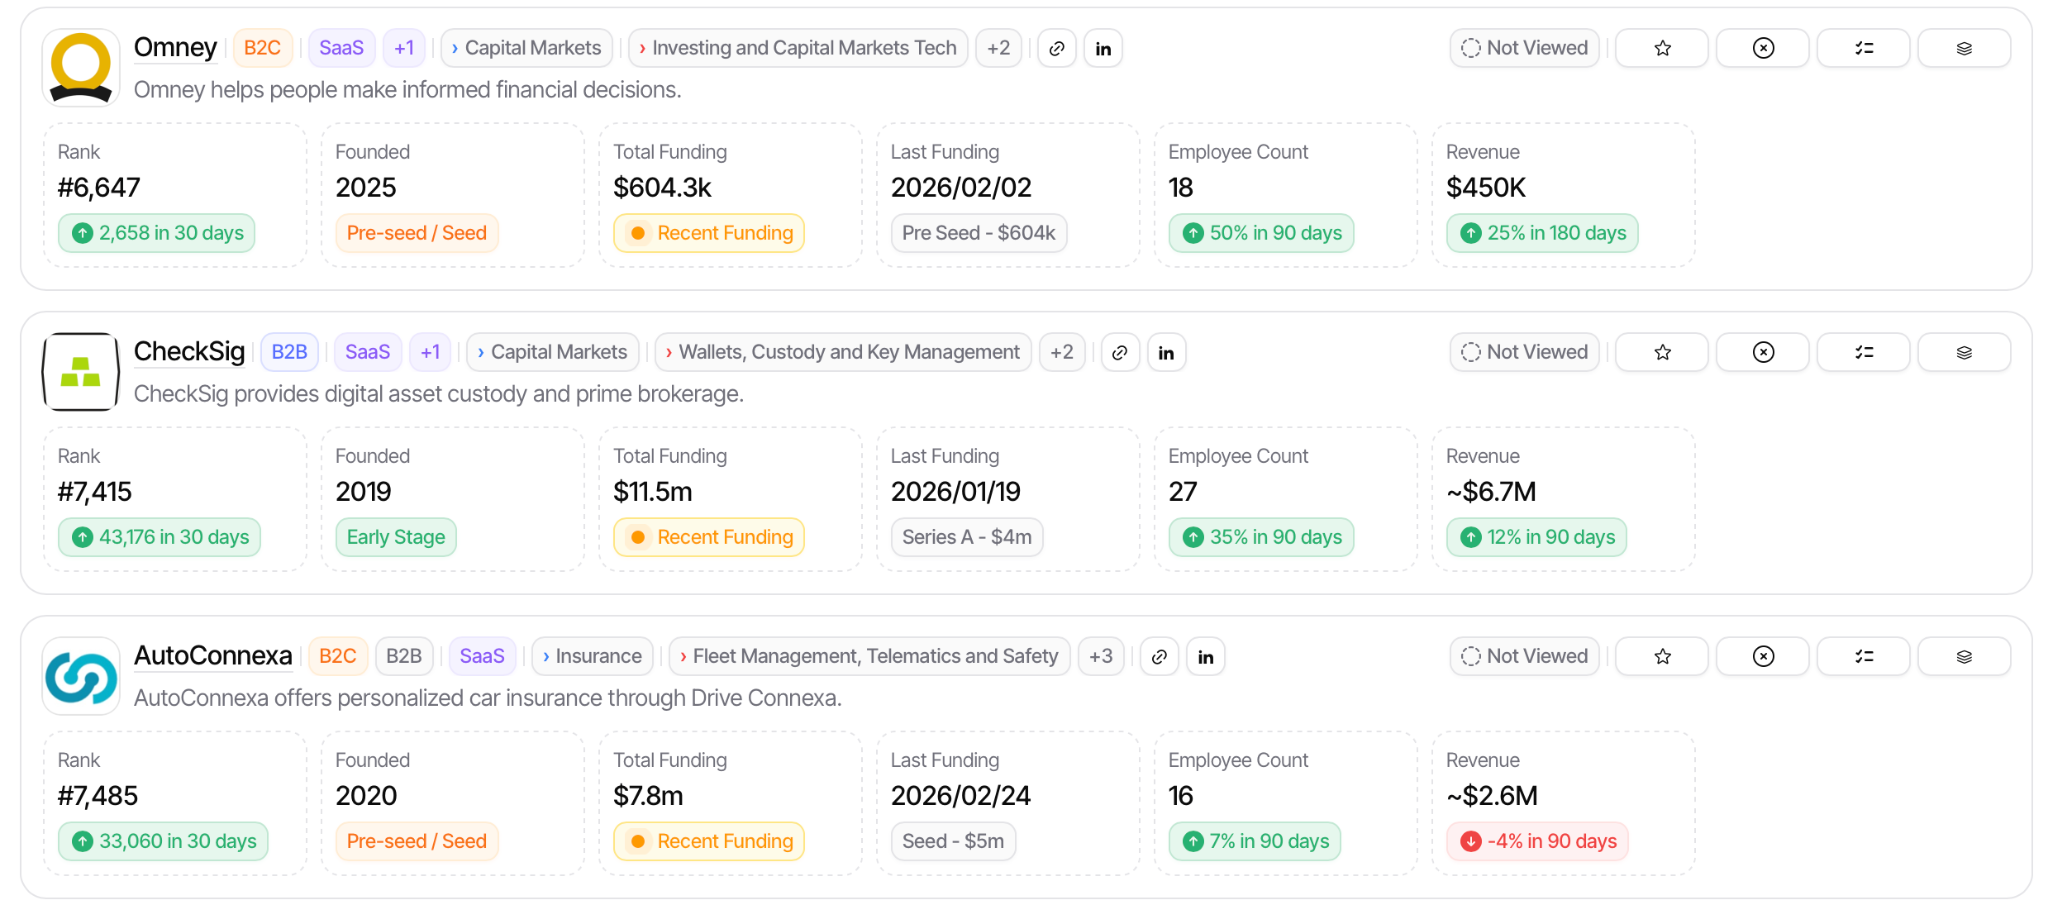
This week I took a look at the most interesting fintech startups in Italy, focusing on companies bootstrapped in the early stage.
I usually use Spectre to scout for new ideas, the team is great and they also give me a free account once they learned I was a fan of the product. So if you wanna take a look at it, you can find it here.
VCs and PEs raising new funds now
I would like to leave this part of the newsletter as space for VC and solo GP that are launching new funds right now. I frequently speak with GPs and LPs, and I like the idea of giving them a showcase where to announce what they are doing. Here the new funds raising right now that I have been talking with:
- Parallax Ventures, a fintech VC fund focused on Latam. They closed Fund I with a strong +50% IRR and 0.7x DPI, and are now raising Fund II. Take a look here if you want to know more or reach out directly to the GP at gennari@parallax.vc for details.
- Founder Factor, VC focused on YC companies, that just closed investments on the latest YC W26. They are expanding the current vehicle to double down on the current batch. You can take a look here if you are interested.
- RedFish Capital Partners, a private equity investor focused on Italian SMEs in growth and mature capital phases, with a track record exceeding 40% IRR and with over €200M in Assets. Currently raising its brand new AIF, which has already secured a soft commitment from the European Investment Fund (EIF). You can check them out at redfish.capital or contact the team at investor.relations@redfish.capital.
Overall, very interesting to see where the VC ecosystem is heading recently, between new emerging managers, solo GP and micro funds.
Always happy to support if I can! If you are raising a fund and you want to be listed here send me a message on Linkedin.
And finally, take also a look at the last edition of the newsletter, Weekly update #141
Topics
Related funding
| Company | Round | Amount | Date |
|---|---|---|---|
| Augustus Added · · Weekly update #142 | Series B | 180,000,000 USD | 21 July 2026 |
| Pinbank Brasil Added · · Weekly update #142 | Credit fund | 100,000,000 BRL | 2 July 2026 |
| CuspAI Added · · Weekly update #142 | 393,200,000 EUR | 20 July 2026 | |
| Veriqus Group Added · · Weekly update #142 | 40,200,000 USD | 23 July 2026 | |
| Ant International Added · · Weekly update #142 | Series A | 1,200,000,000 USD | 21 July 2026 |
| Fina Added · · Weekly update #142 | Debt facility | 75,000,000 USD | 22 July 2026 |
| Cordant Added · · Weekly update #142 | Seed | 8,000,000 USD | 21 July 2026 |
| Natural Added · · Weekly update #142 | 30,000,000 USD | 21 July 2026 | |
| Sereact Added · · Weekly update #142 | Series B | 116,000,000 USD | 20 July 2026 |
| Zeom Added · · Weekly update #142 | Pre-seed | 2,700,000 USD | 22 July 2026 |
| Cashea Added · · Weekly update #142 | Series B | 60,000,000 USD | 21 July 2026 |