Weekly update #139
The latest news from the fintech and VC ecosystem
Welcome to this edition of the weekly newsletter. The idea behind this is to gather all the information in the startup ecosystem in one place, with a special focus on the fintech market and the VC industry.
The latest episode of Builders has been released last week! In this episode, I sit down with Martina Weimert, CEO and founder of EPI Company ( Wero ). You can watch the full episode here on YouTube, or listen to it here on Spotify or here on Apple Podcast. But take a look at a quick clip first:
Martina has been supporting and guiding European banks and acquirers to build the foundation of the EPI company since the initiative was established in 2020, aiming to build an independent European solution and connect Europe’s payment industry.
With 20 years of experience in international payment consulting, she has in-depth experience in payments and payment solution set up, fintech, blockchain and retail banking in Europe, the Americas and Middle East. Prior to joining EPI company, she was a partner in financial services at Oliver Wyman in Paris, leading the European payment practice, and previously holding the position of Senior VP at Capgemini consulting and sales director for Deutsche Bank in France.
With her, we will talk about the importance of having an European independent and sovereign payment infrastructure, the resilience of new payment methods and the future of payments in the EU.
Coming back to us, I’ve been reading a very interesting report this week, the “B2B embedded finance landscape” by Apideck. The study is an embedded finance stack analysis of 1,200 companies, and a practitioner survey of 50 operators conducted between March and May 2026, highlighting major trends and figures in this vertical. Here my main takeaways:
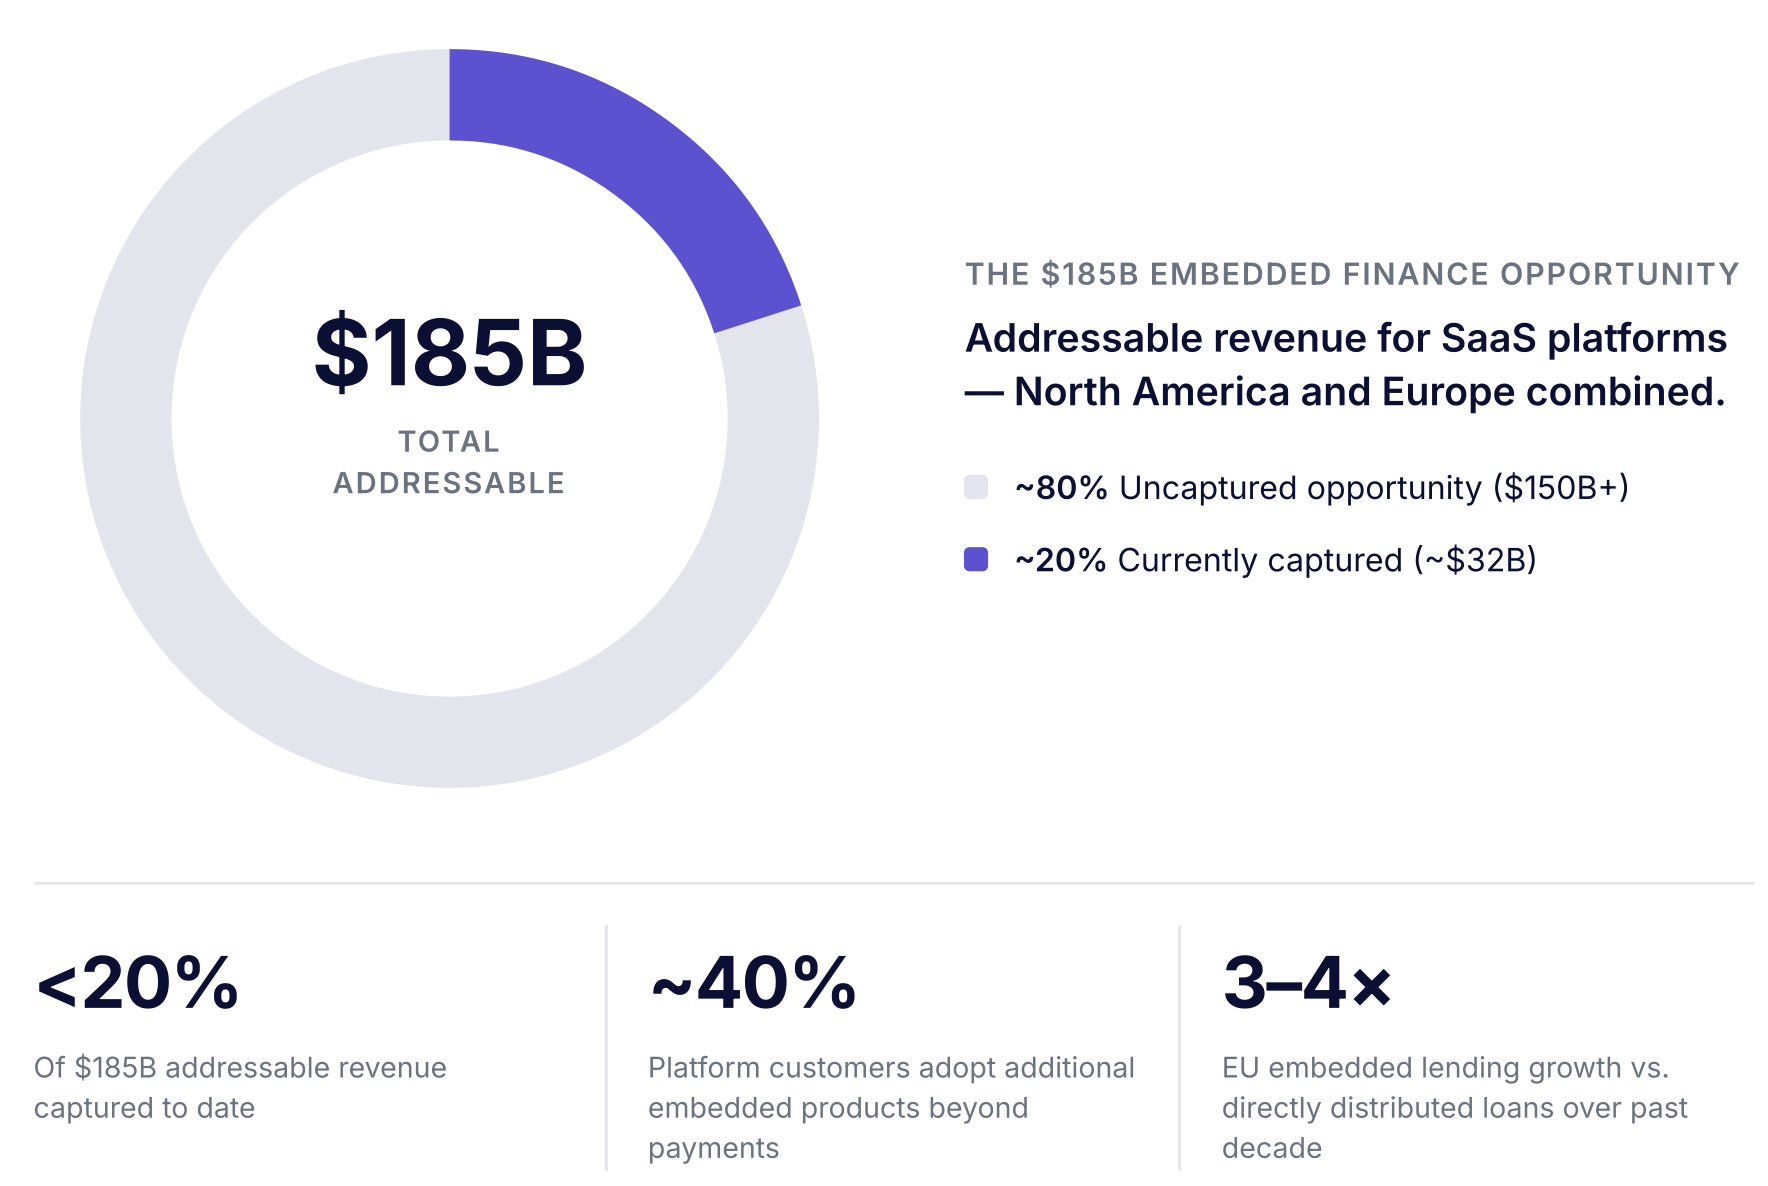
BCG and Adyen estimate that SaaS platforms in North America and Europe face a $185 billion embedded finance revenue opportunity, with less than 20% currently captured. Based on research involving about 30 leading platforms and 2,000 SMBs across eight industries, current penetration is roughly $32 billion, leaving more than $150 billion available.
Around 40% of platform customers adopt financial products beyond payments. Supporting estimates from Bain & Company and McKinsey & Company point to strong expansion, including a 19% CAGR in the US and a European market exceeding $116 billion by 2030. Across regions, B2B and non-payment services remain the strongest future growth drivers.
Payments remain the primary entry point for embedded finance, offered by over 60% of North American ISVs. SaaS platforms captured 36% of SME acquiring revenue in 2024, potentially reaching 45% by 2028. North America leads in revenue, while Europe could exceed $116 billion by 2030, supported by PSD2 and open banking.
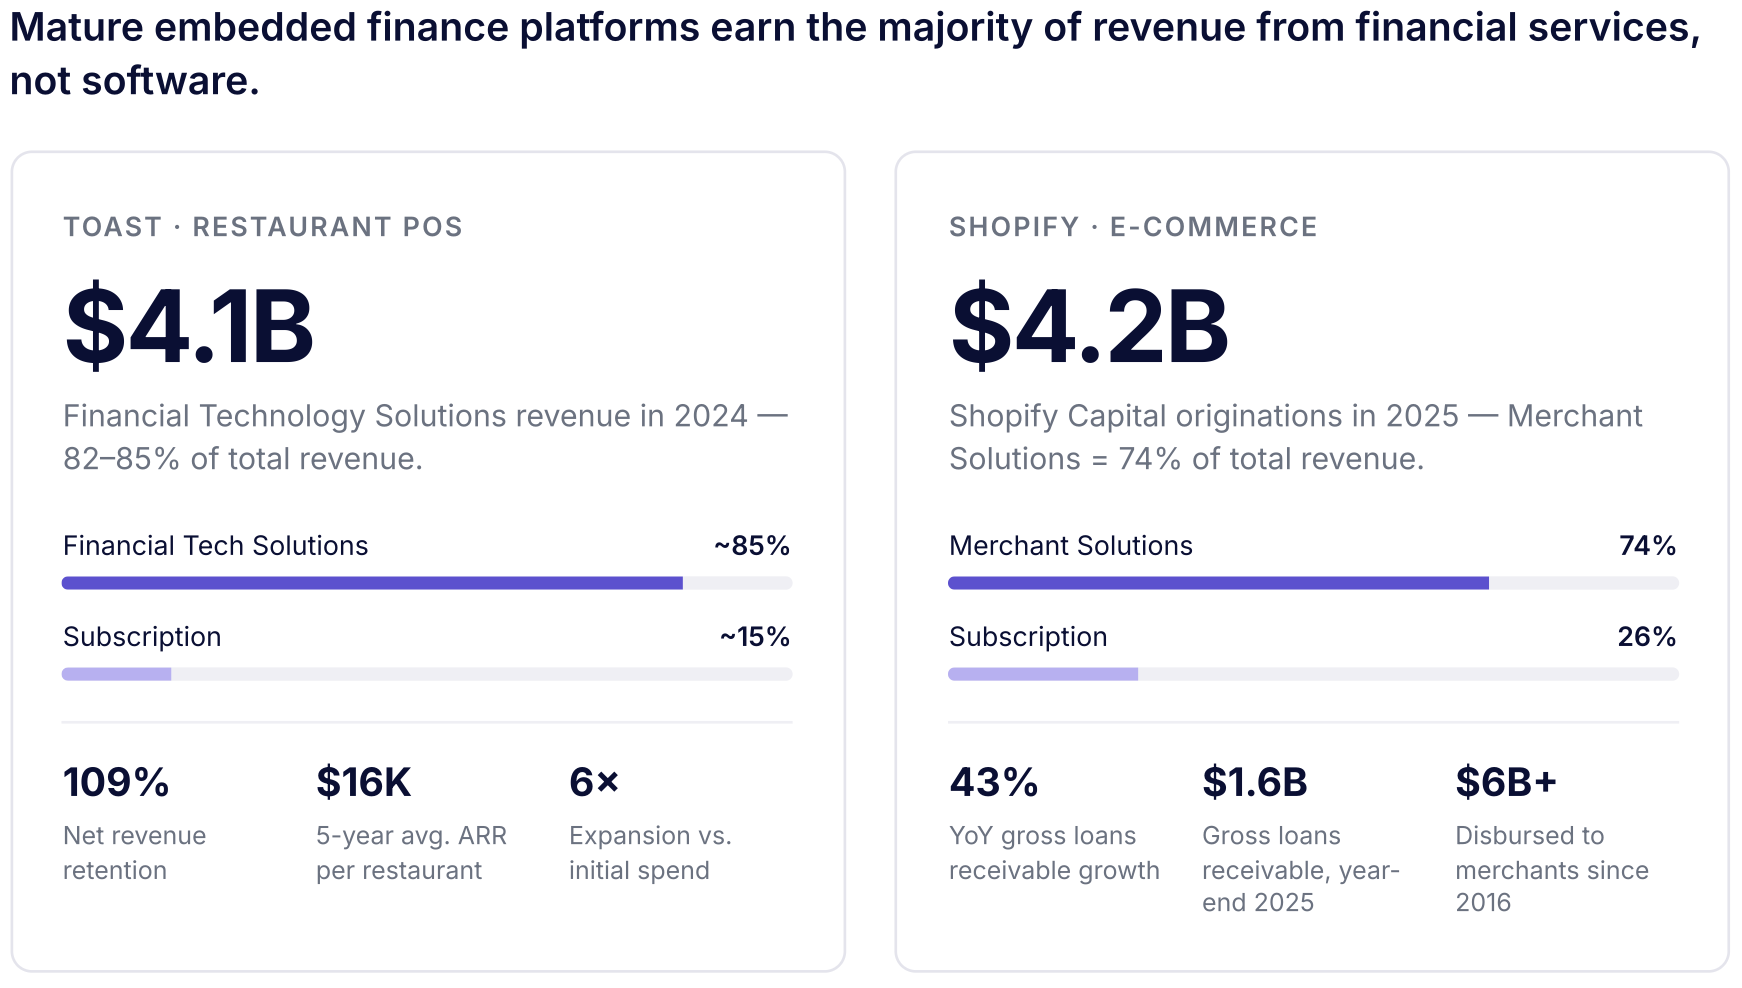
Asia Pacific is growing fastest, with India recording an estimated 45% CAGR. Public companies demonstrate the model’s value: financial services generate up to 85% of Toast’s revenue and 74% of Shopify’s. ServiceTitan also uses embedded payments, payroll and financing to strengthen retention and revenue growth.
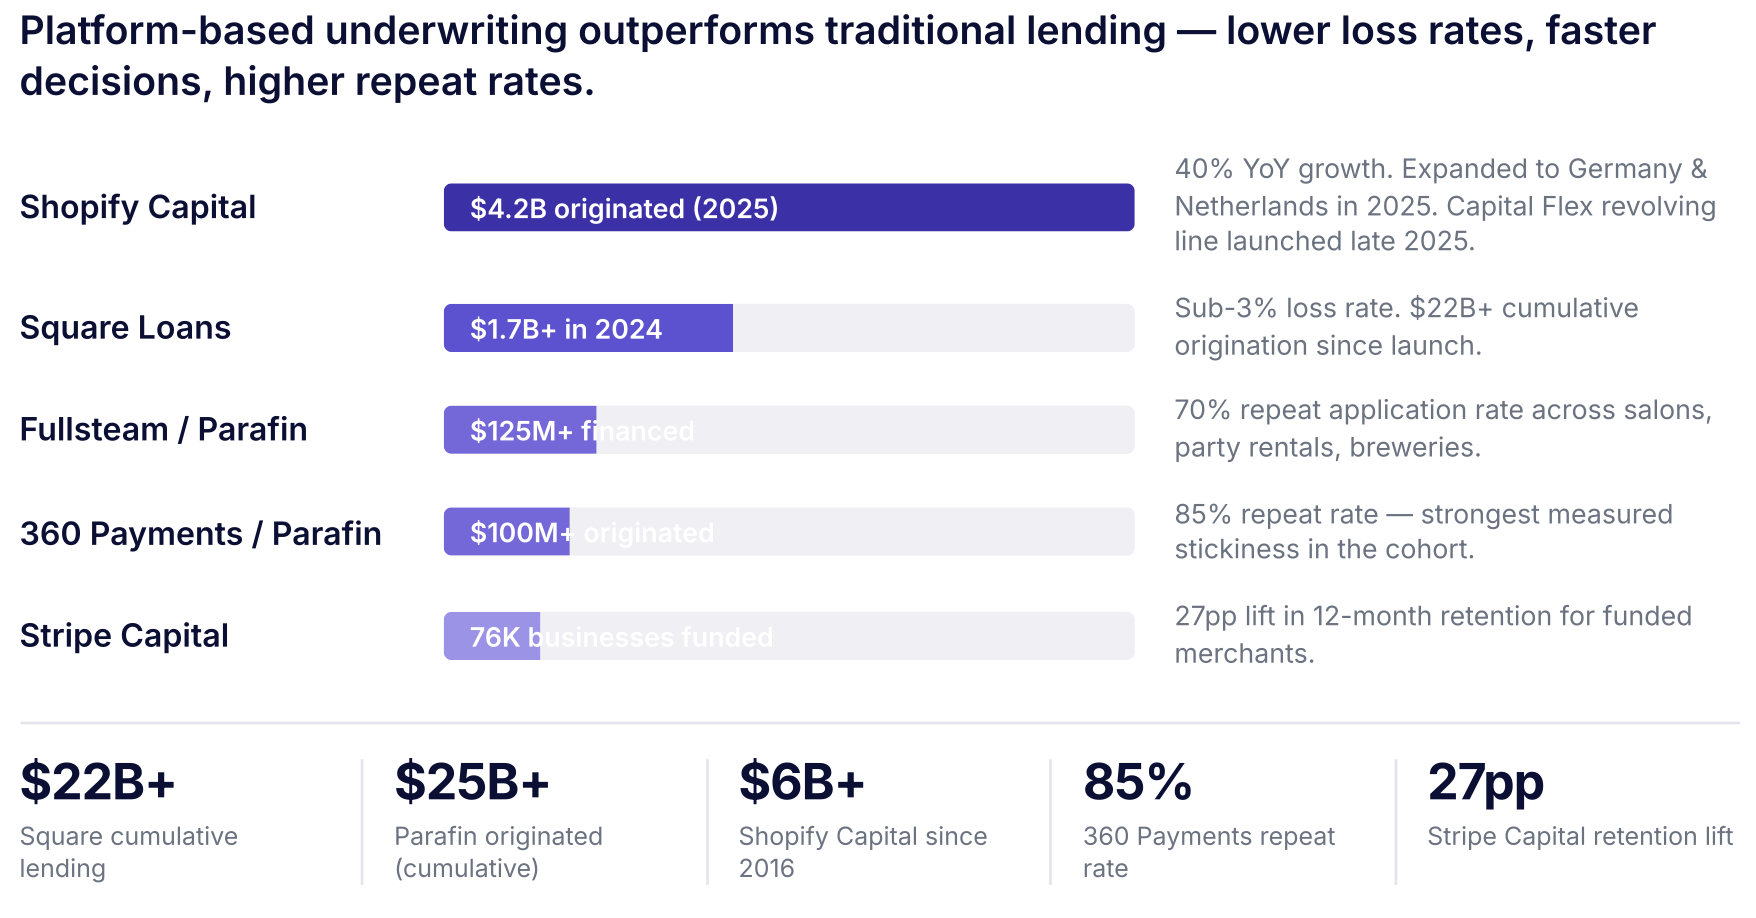
Embedded lending allows non-financial platforms to monetize proprietary transaction, invoice and order data that traditional banks cannot access. Their advantage lies in faster decisions, broader access and revenue-linked repayments rather than lower interest rates. Lending is increasingly becoming the main revenue engine for vertical SaaS providers after payments.
Shopify Capital originated $4.2 billion in 2025, while Square exceeded $22 billion cumulatively with loss rates below 3%. Platform models also show repeat usage and retention gains. Partnerships with providers such as Parafin and finmid enable SaaS platforms to offer credit without assuming balance-sheet risk, accelerating adoption across the US and Europe.
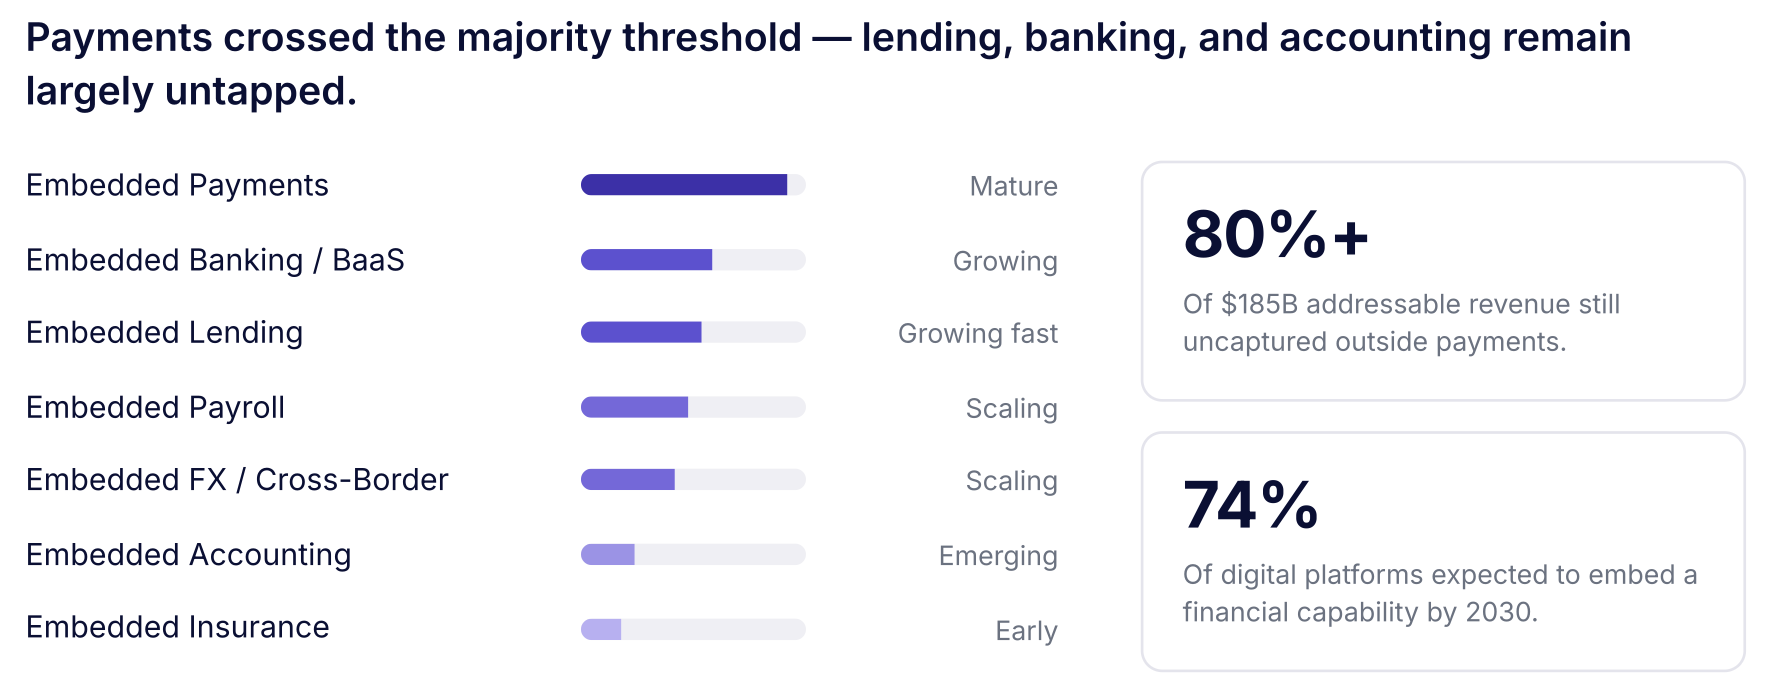
Embedded payments have reached mainstream adoption, with over 50% of relevant North American ISVs offering them and some estimates exceeding 60%. Adoption beyond payments remains limited, as only 40% of platform customers use additional financial products. By 2030, 74% of digital platforms are expected to integrate financial capabilities.
Investment is accelerating, with global fintech funding reaching $51.8 billion in 2025, up 27%, while embedded finance startup funding rose 22% in Q2. More than 80% of the $185 billion opportunity remains uncaptured, primarily across lending, banking, payroll, accounting, insurance, foreign exchange and cross border services for B2B platforms.
But let’s take a closer look at the main news of the last seven days, Bending Spoons goes public on Nasdaq, Open Standard launches Open USD, X begins roll out of X Money to premium users in the US and Revolut ends remote working for interns. But also, Qonto acquires Acasi, Payward acquires Reap, Mynt targets a $1.5B IPO and Adyen secures UAE payment license. In the VC ecosystem, P101 integrates Prana Ventures in first Italian VC aggregation, Osney Capital launches a $60M fund, Daybreak a $100M fund to back AI ideas, Tapestry VC a $80M fund for repeat founders. But also Vicus Ventures, Ruya Ventures, Orbit Capital and Valor Equity Partners with new funds. And finally, some very interesting funding rounds from fintech startups like Addi, MDOTM Ltd, Ultra, Nomerra, Nebex, BR-DGE, Jota and many others.
Let’s take a closer look:
Rounds
- Addi raises $85M to accelerate Colombia’s digital finance expansion
- Arca emerges from stealth with $64M for AI native wealth management
- Techdollar raises $3M to unlock liquidity for pre IPO employees
- Nomerra raises $2M to automate private market operations
- GV (Google Ventures) leads $30M seed round for space fintech Nebex
- Stabyl raises $2.7M to modernise Africa’s FX infrastructure
- Wultra raises €6.8M to scale post quantum digital identity
- MDOTM Ltd raises $27M to scale AI investment platform Sphere
- InSoil secures €120M facility for sustainable agriculture financial backing
- Januar secures MiCA license and raises €1M
- AXON secures $1M to expand cross border payments infrastructure
- BR-DGE raises £10M to accelerate global payments expansion
- Jota raises R$150M and launches proactive AI financial assistant
- Qashier raises $6.12M after reaching sustained profitability
- Offa secures £6.5M to expand islamic property finance across the UK
- LinqAlpha raises $22M to build AI intelligence for public markets
- Taxwire raises $25M to automate global sales tax compliance
VC funds
- Omnea and firedrop launch $250,000 future founders fund
- Orbit Capital raises €107M for second growth debt fund
- P101 integrates PranaVentures to build a €700M VC champion in Italy
- Osney Capital closes £60M fund for UK cybersecurity startups
- Daybreak raises $100M fund to back AI native founders
- Valor Equity Partners targets at least $2.5B for fund VII
- Tapestry VC raises $80M third fund to back repeat founders
- Vicus Ventures closes $55M debut fund around a “Network as a Service” model
- Ruya Ventures launches $50M fund for European deeptech startups
News on the market
- Revolut ends remote working for 2027 graduates and interns
- X Money begun roll out to premium users with up to $10M in FDIC coverage
- Atom bank’s £600M sale nears collapse after weak bid interest
- Kraken explores 15% stake in Aave Labs at $385M valuation
- Mynt targets record $1.5B Philippine IPO for GCash
- Kalshi seeks $40B valuation as prediction market competition intensifies
- Revolut opens Philippines waitlist ahead of potential market launch
- Beobank NV/SA launches Beobank Pay with Wero integration
- Coinbase enables stablecoin access to Spiko’s UCITS funds
- Tencent tests TenPayGo app for overseas visitors in China
- Santander backed Ebury considers £100M Lumon acquisition
- Bending Spoons goes public on Nasdaq at $29 per share, $18.4B valuation
- Coinbase and OKX target Binance users ahead of MiCA deadline
- Adyen secures UAE payments license to expand local operations
- Payward completes Reap acquisition to expand stablecoin payments infrastructure
- Qonto acquires Acasi to add certified online accounting
- Open Standard launches Open USD with more than 140 global partners
And here some useful resources for everyone involved in the ecosystem:
Events you don’t want to miss
- Money 20/20 Middle East | Riyadh | 14-16 September (link here)
- European blockchain week | Barcelona | 16-17 September (link here)
- Nordic fintech week | Copenhagen | 23-24 September (link here)
- Money 20/20 USA | Las Vegas | 18-21 October (link here)
- Hong Kong fintech week | Hong Kong | 02-06 November (link here)
- Fintech Nerdcon | San Diego | 19-20 November (link here)
You have a cool event you want to mention or to sponsor? Feel free to send me a DM.
Founders to watch in fintech
I also wanted to start shining a light on the most interesting fintech founders out there, so I thought to start sharing how I look for ideas to invest on. Every week, I will start sharing the most interesting founders in fintech, divided per area.
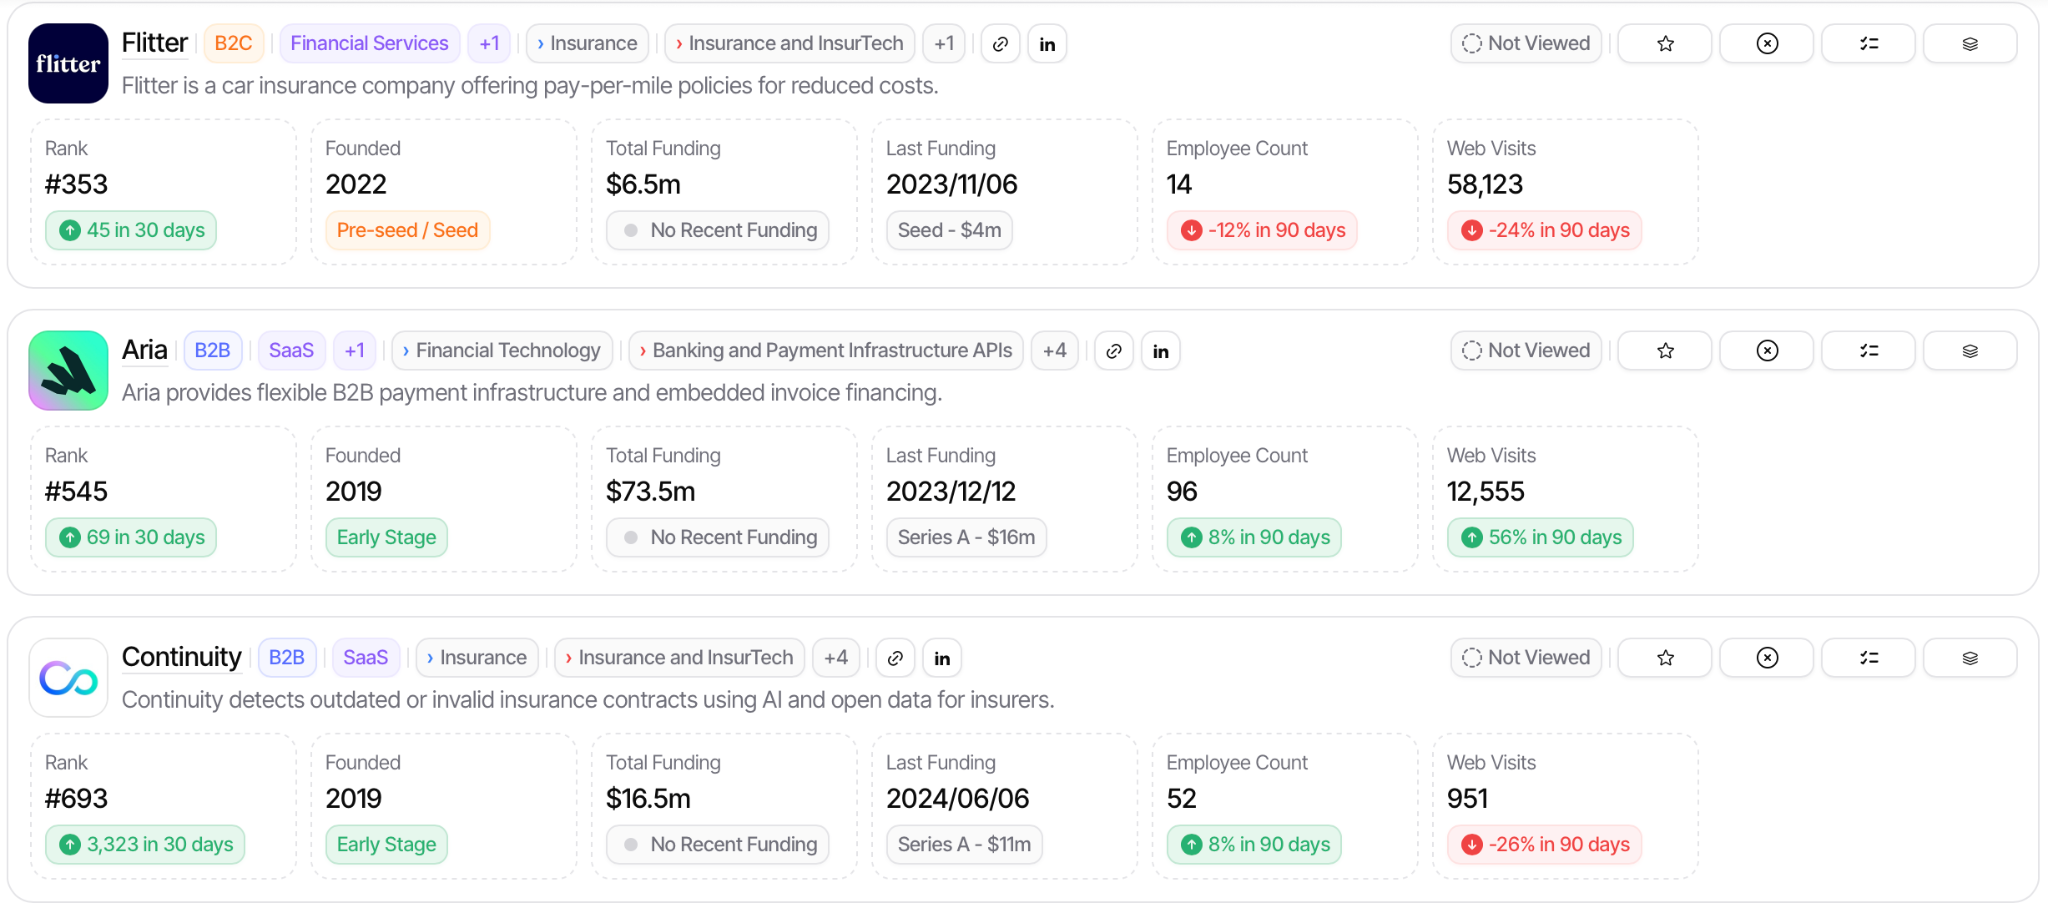
This week I am taking a look at the most interesting fintech companies in France! And you can already see a couple of interesting founders in stealth!
I usually use Spectre to scout for new ideas, the team is great and they also give me a free account once they learned I was a fan of the product. So if you wanna take a look at it, you can find it here.
VCs and PEs raising new funds now
I would like to leave this part of the newsletter as space for VC and solo GP that are launching new funds right now. I frequently speak with GPs and LPs, and I like the idea of giving them a showcase where to announce what they are doing. Here the new funds raising right now that I have been talking with:
- Parallax Ventures, a fintech VC fund focused on Latam. They closed Fund I with a strong +50% IRR and 0.7x DPI, and are now raising Fund II. Take a look here if you want to know more or reach out directly to the GP at gennari@parallax.vc for details.
- Founder Factor, VC focused on YC companies, that just closed investments on the latest YC W26. They are expanding the current vehicle to double down on the current batch. You can take a look here if you are interested.
- RedFish Capital Partners, a private equity investor focused on Italian SMEs in growth and mature capital phases, with a track record exceeding 40% IRR and with over €200M in Assets. Currently raising its brand new AIF, which has already secured a soft commitment from the European Investment Fund (EIF). You can check them out at redfish.capital or contact the team at investor.relations@redfish.capital.
Overall, very interesting to see where the VC ecosystem is heading recently, between new emerging managers, solo GP and micro funds.
Always happy to support if I can! If you are raising a fund and you want to be listed here send me a message on Linkedin.
And finally, take also a look at the last edition of the newsletter, Weekly update #138
Topics
Related funding
| Company | Round | Amount | Date |
|---|---|---|---|
| Januar Added · · Weekly update #139 | 1,000,000 EUR | 29 June 2026 | |
| Stabyl Added · · Weekly update #139 | Pre-seed | 2,700,000 USD | 29 June 2026 |
| Qashier Added · · Weekly update #139 | Series A+ | 6,125,000 USD | 30 June 2026 |
| Nebex Added · · Weekly update #139 | Seed | 30,000,000 USD | 30 June 2026 |
| InSoil Added · · Weekly update #139 | Debt facility | 120,000,000 EUR | 1 July 2026 |
| Techdollar Added · · Weekly update #139 | 3,000,000 USD | 29 June 2026 | |
| MDOTM Ltd Added · · Weekly update #139 | Growth | 27,000,000 USD | 30 June 2026 |
| Taxwire Added · · Weekly update #139 | Seed + Series A | 25,000,000 USD | 1 July 2026 |
| Wultra Added · · Weekly update #139 | Series A | 6,800,000 EUR | 29 June 2026 |
| Jota Added · · Weekly update #139 | 150,000,000 BRL | 2 July 2026 | |
| BR-DGE Added · · Weekly update #139 | 10,000,000 GBP | 30 June 2026 | |
| AXON Added · · Weekly update #139 | Seed | 1,000,000 USD | 28 June 2026 |
| Offa Added · · Weekly update #139 | Sukuk | 6,500,000 GBP | 2 July 2026 |
| Nomerra Added · · Weekly update #139 | Pre-seed | 2,000,000 USD | 30 June 2026 |
| LinqAlpha Added · · Weekly update #139 | Series A | 22,000,000 USD | 2 July 2026 |