Weekly update #137
The latest news from the fintech and VC ecosystems
Welcome to this edition of the weekly newsletter. The idea behind this is to gather all the information in the startup ecosystem in one place, with a special focus on the fintech market and the VC industry.
The latest episode of Builders has been released this week! In this episode, I sit down with Deniz Güven 顧海, CEO of wamo. You can watch the full episode here on YouTube, or listen to it here on Spotify or here on Apple Podcast. But take a look at a quick clip first:
Deniz is a senior fintech and digital banking executive with extensive experience building financial services across Europe, the Middle East, and Asia. He is currently Group CEO and Chair of the Board at wamo, and has held leadership and board roles at AKTech, Platform XIT, Colendi, Trust Bank Singapore, and Beşiktaş JK.
Previously, Deniz served as CEO of Mox Bank in Hong Kong, the virtual bank backed by Standard Chartered, and held senior digital leadership roles at Standard Chartered and Garanti BBVA. His career spans digital banking, fintech ventures, product innovation, and alternative revenue streams. Deniz has also mentored fintech start ups through Garanti Partners and brings a global perspective on how digital platforms are reshaping financial services.
With him, we will talk about SMEs banking in Europe, but also about his incredible careers in banking across APAC and MENA, and the future of banking.
Coming back to us, I’ve been reading a very interesting report this week, the “Tech Nation report 2026 - Next wave of UK AI” by Dealroom.co and Founders Forum Group. The study is a complete overview of the UK AI market, including major trends, investments, but also talent pool and growth projections. Here my main takeaway:
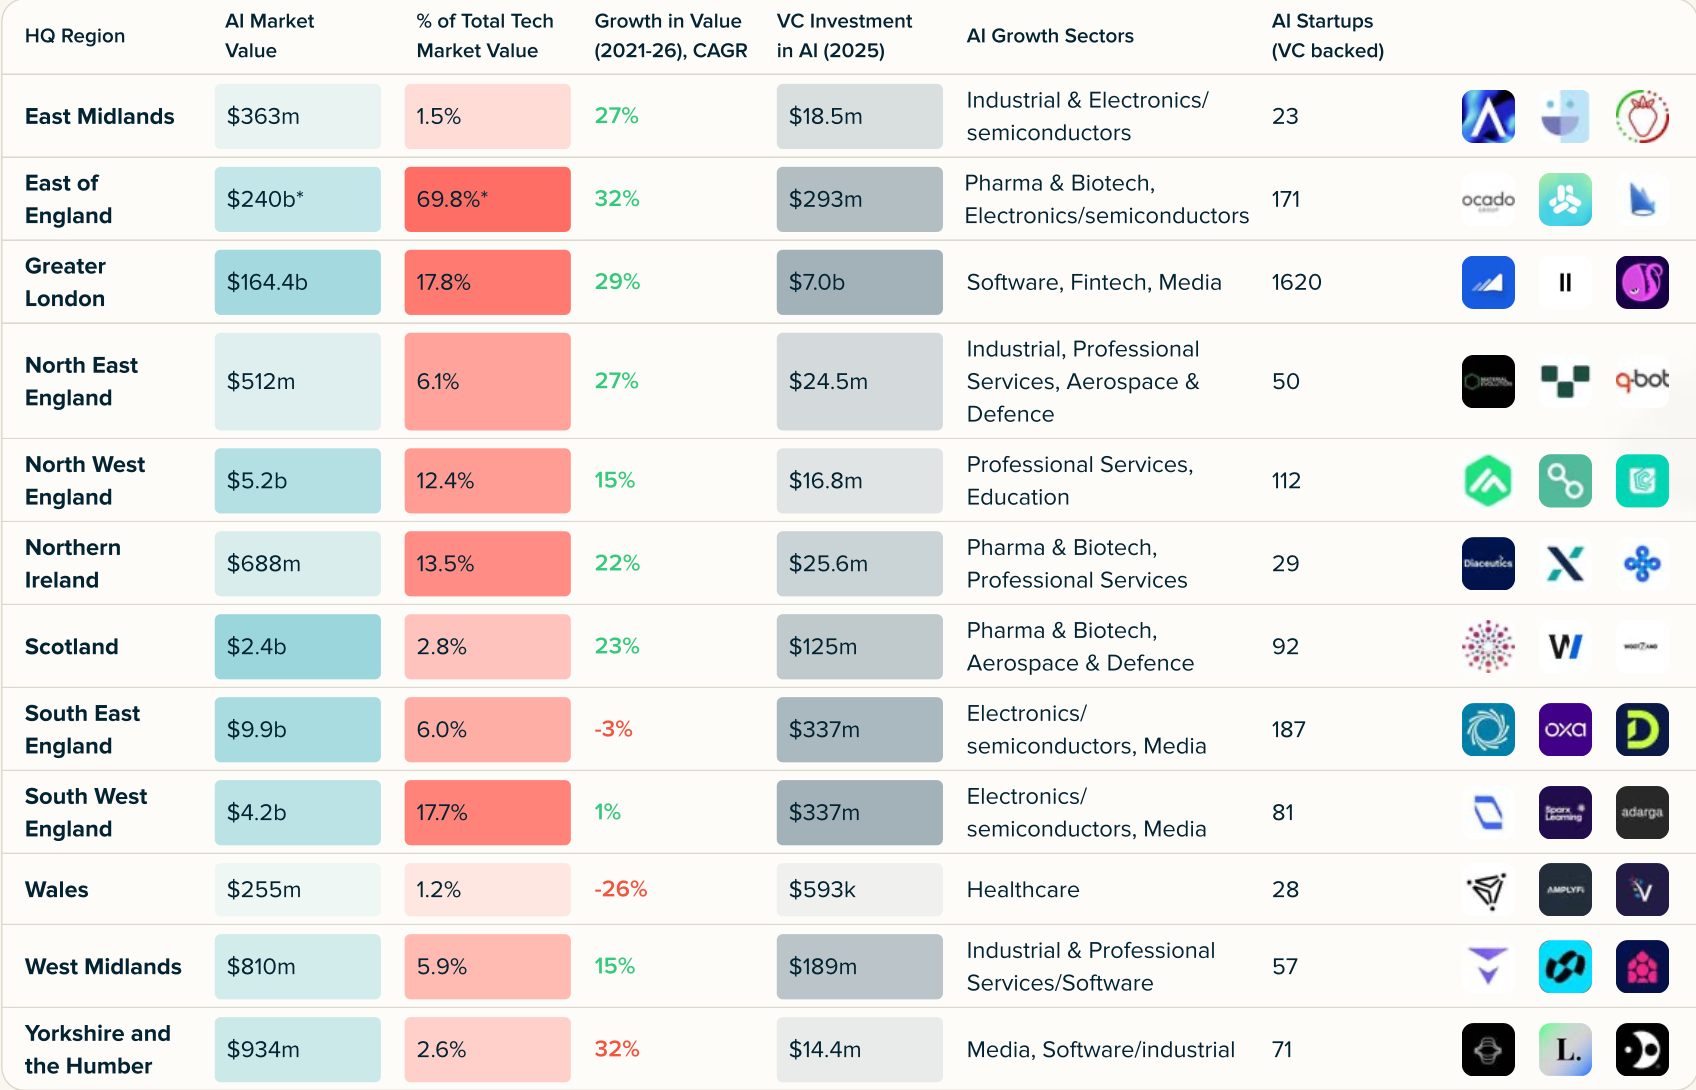
The UK AI market shows strong regional concentration, led by the East of England with an estimated value of $240 billion and Greater London at $164.4 billion. London remains the main investment and startup hub, attracting $7 billion in AI venture capital and hosting 1,620 VC backed companies.
The East of England records the fastest projected growth at 32%, alongside Yorkshire and the Humber, while London is expected to grow by 29%. Other regions show smaller but expanding ecosystems, including Scotland, the South East and West Midlands. However, Wales and the South East face weaker growth, demonstrating persistent regional disparities across the UK AI economy.
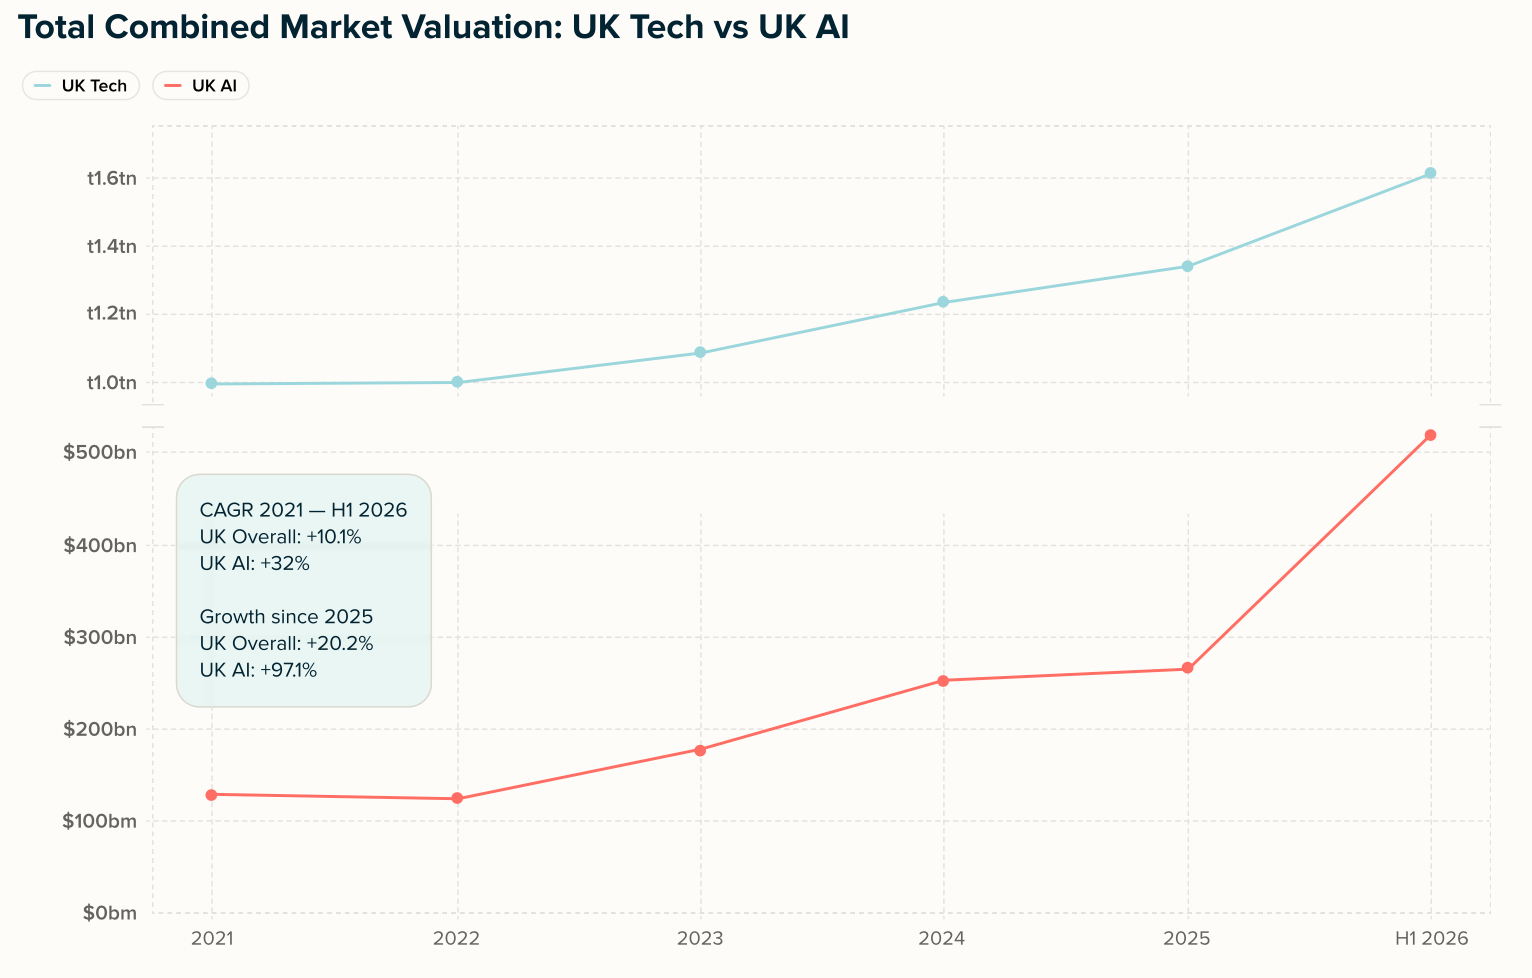
AI is becoming a central driver of the UK technology sector, which is now valued at $1.6 trillion. In H1 2026, the combined valuation of UK AI companies exceeded $518 billion, representing 32.2% of the country’s total tech market value. Over the previous year, the sector grew by more than $255 billion, an increase of 97.1%. Major contributors include Arm, valued at $220 billion, Nscale at $14.6 billion, ElevenLabs at $11 billion, Wayve at $8.6 billion, Isomorphic Labs at up to $12.6 billion, and Darktrace at $5.3 billion.
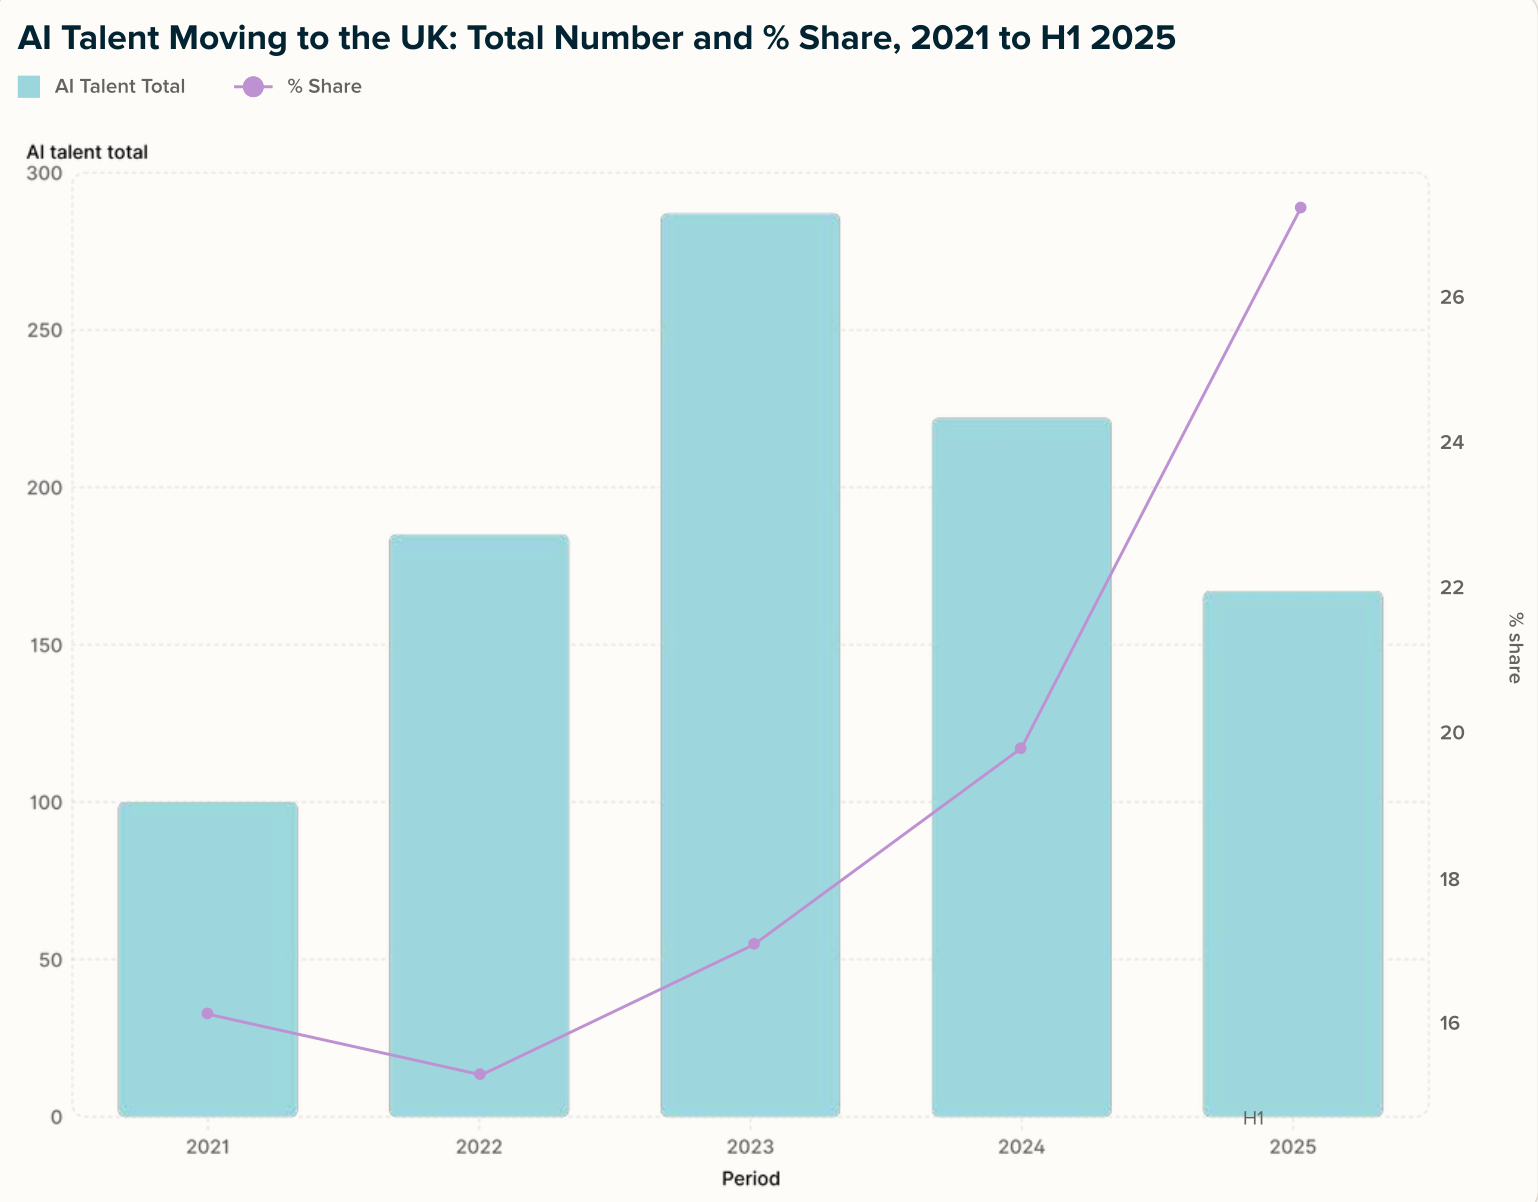
The UK is the world’s third largest AI talent hub, behind the US and India, with more than 56,000 AI professionals and 10,650 frontier researchers. It ranks fourth globally for researcher numbers, third for researcher density and tenth for overall AI talent density. International professionals represent 52% of the workforce, while women account for 21%. The UK is also attracting a growing share of global expertise: in 2025, AI and machine learning specialists represented 27% of skilled technology talent entering the country, compared with 16% in 2021, strengthening its position as a leading AI ecosystem.
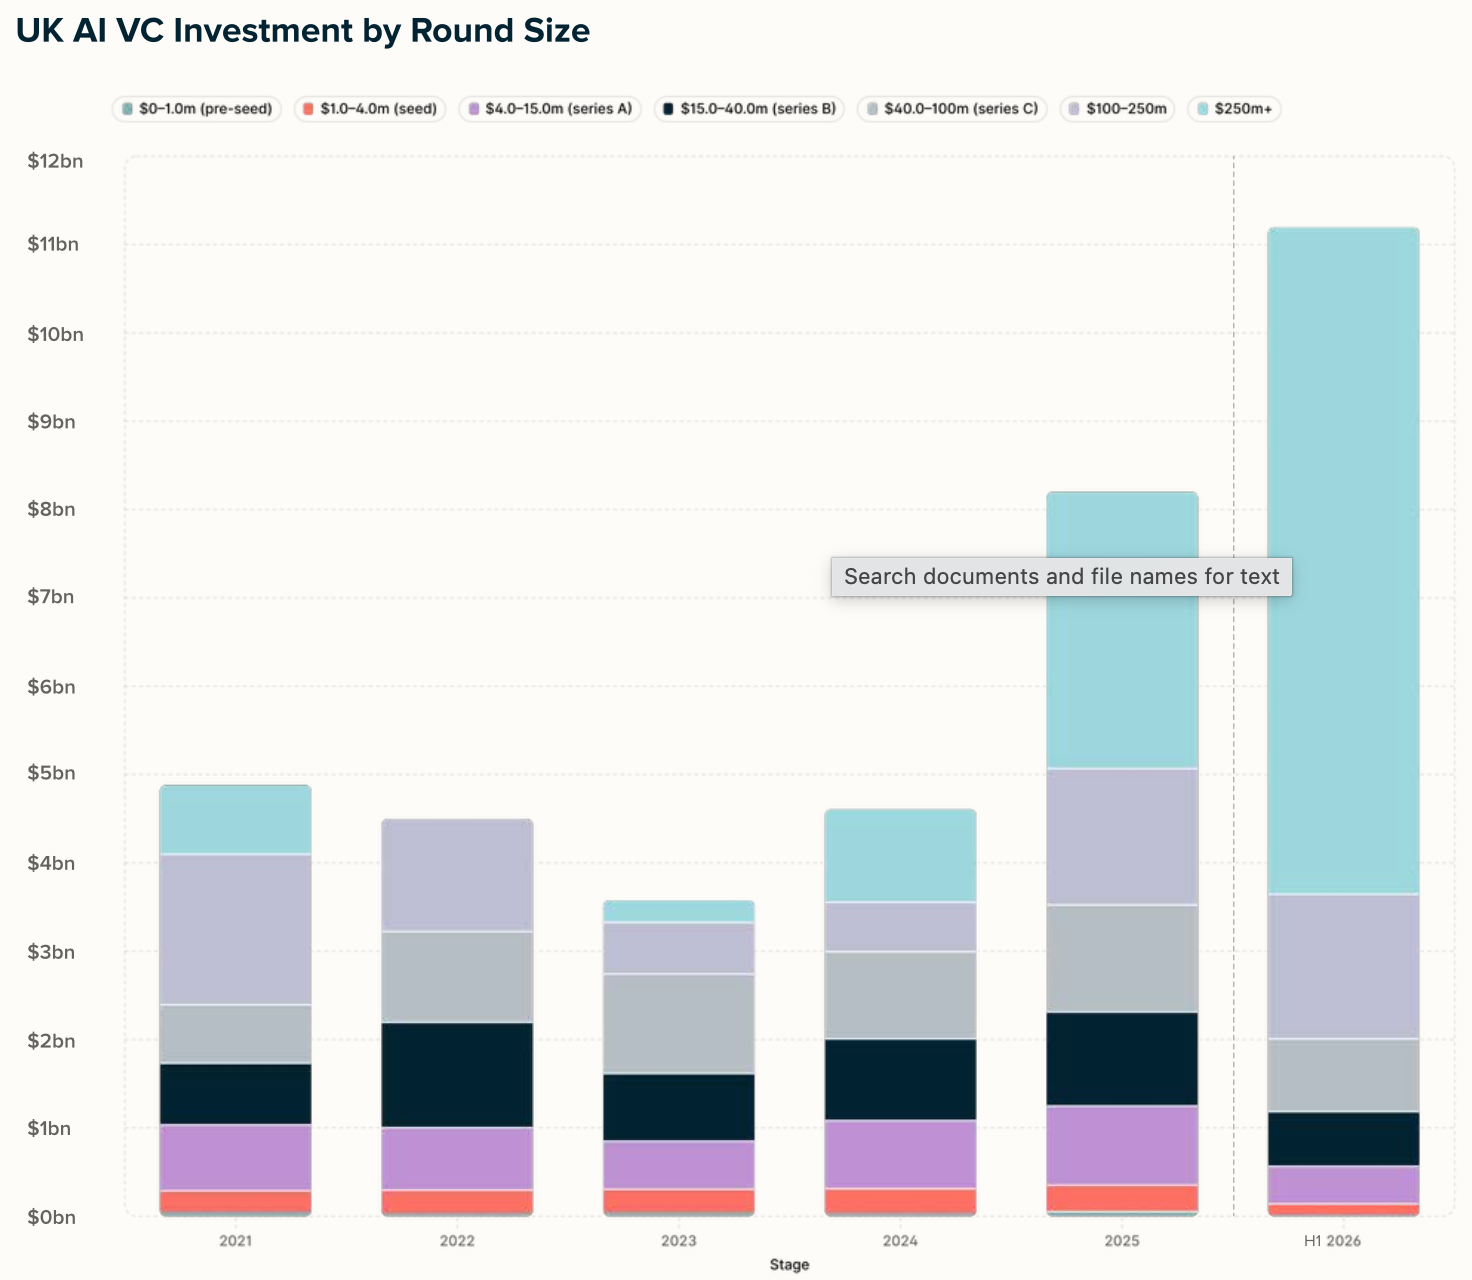
UK AI startups raised more than $11 billion in venture capital during H1 2026, exceeding the previous annual record in six months. AI companies attracted 77% of the UK’s total $14.5 billion VC investment, compared with 13% in 2021 and 34% in 2025. The sector has raised more capital in the past 18 months than during the previous four years, becoming the primary driver of the UK technology investment recovery.
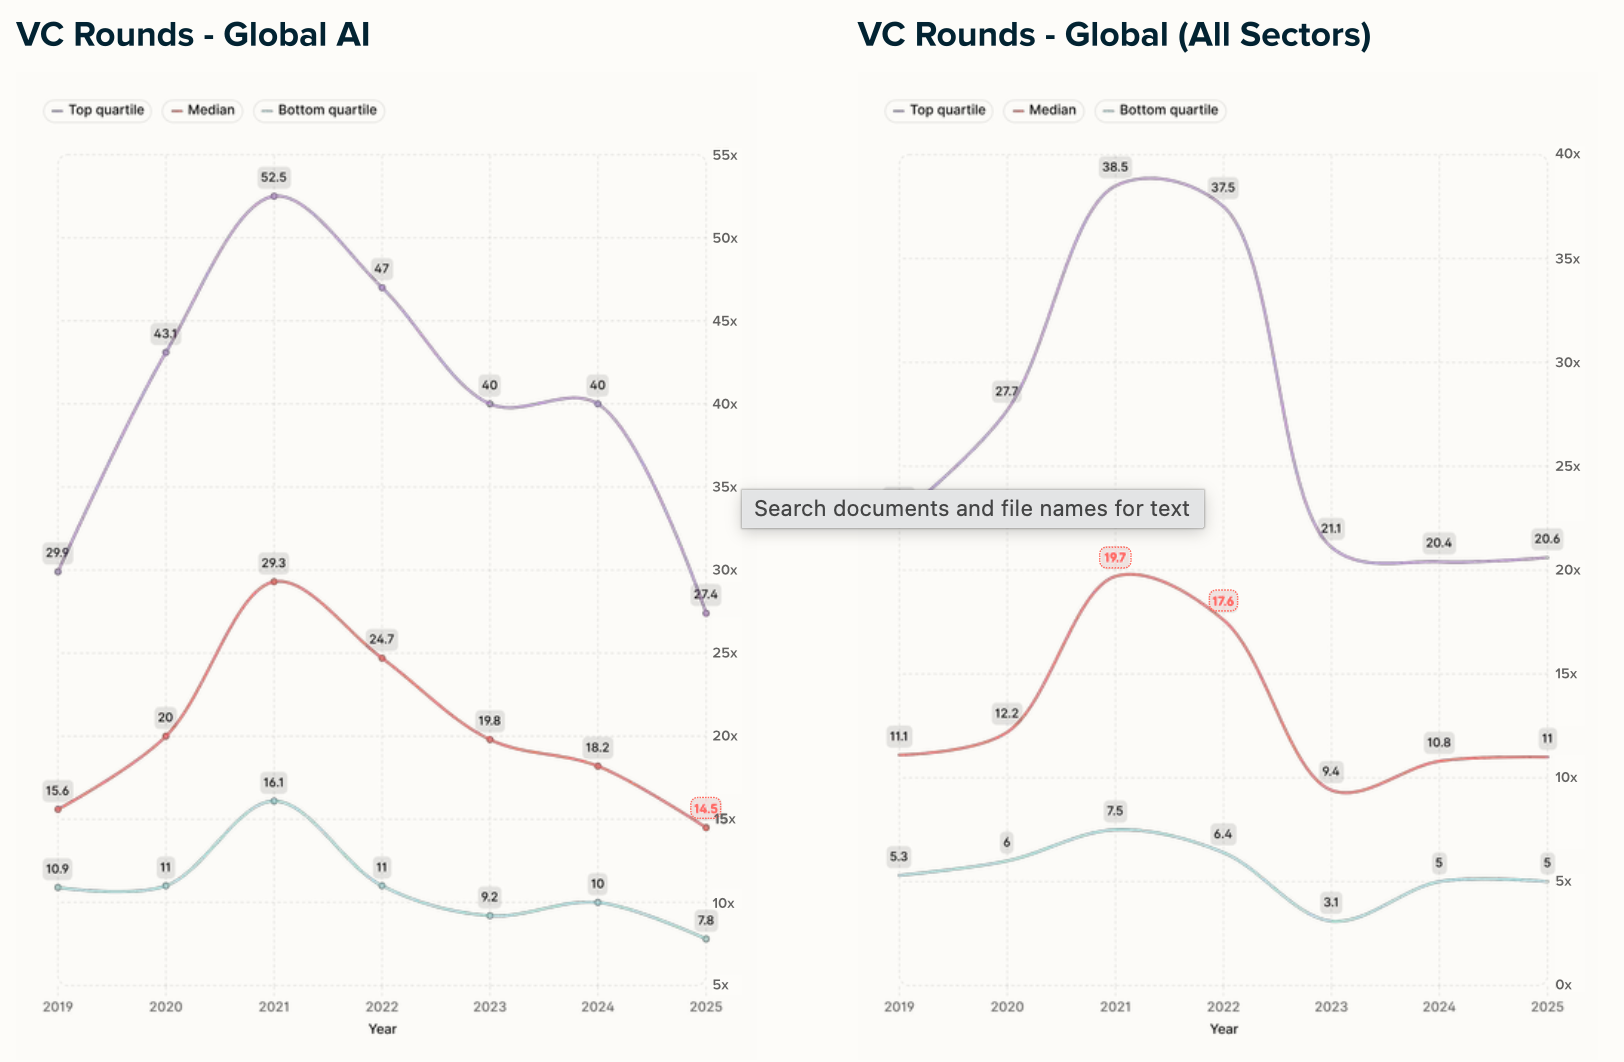
UK technology leaders remain broadly confident in the sustainability of the AI market despite concerns about excessive valuations. Around 30% of founders and 22% of investors consider AI to be in a bubble, yet only 9% in either group expect it to burst. More than 80% believe the market will remain durable, while 65% view the investment surge as a long term platform shift comparable to the internet.
Although leading AI startups command valuation to revenue multiples of up to 27 times, these levels remain broadly aligned with the wider venture market. Median AI multiples in 2025 were below the global VC levels recorded during the overheated investment environment of 2021 and 2022, supported by continued revenue growth across AI companies.
But let’s take a closer look at the main news of the last seven days, Nuvei acquired Payoneer for $2.75B, Revolut and Visa scale click to pay across Europe, Robinhood cuts 10% of the workforce, Mollie commits $350M to expand across Europe. But also, Revolut got a payment license in the UAE, Wise acquired Expatica, ACI Worldwide and Nopan joined EPI Company (Wero) and Microsoft selected Checkout.com to power digital payments. Lot of new funds this week! Anterra Capital closed a $100M fund III, Wave Ventures a $10M first fund, Earlybird Venture Capital and AVP launched a $500M defence tech dual fund. But also new vehicles from Anti Fund, Varangians, BAE Systems, monday.com, FPE. And finally, some very interesting funding rounds from fintech startups like WARREN, Monument, El Dorado, Causa Prima, Waniwani, Range and many others.
Let’s take a closer look:
Rounds
- Fraudio raises new funding to scale AI fraud detection for real time payments
- Waniwani raises $8M to build AI distribution infrastructure for financial services
- Causa Prima raises $10M, Spain’s largest pre seed, to build AI native B2B payments
- Paradigm leads $9M series A for LatAm payments app El Dorado
- Interchecks raises $50M series C to expand real time payments infrastructure
- Clip raises $500M to expand from merchant payments into consumer wallets
- Cortea raises €12M seed round to build AI quality layer for audit firms
- Flagright raises $12.5M to expand explainable AI compliance platform
- Receipts Depositary Corporation (RDC) raises $7M to modernise access to digital assets
- SyntheticFi raises over $13M and surpasses $2B in regulatory AUM
- Monument raises £18M to scale its “Bank in a Box” platform
- Trace Finance raises $32M to scale regulated stablecoin infrastructure
- WARREN raises €10M to reinvent Belgium’s workplace pension market
- Sovra raises $2M+ to build self custodial global dollar accounts
- Green-Got raises €8M in 52 minutes to build sustainable banking infrastructure
- Range raises $8.3M to scale stablecoin compliance infrastructure
- Festina Finance secures over €25M to modernise European pension infrastructure
- Karta secures $140M to expand US credit access for global travelers
- Flyweel raises $2.41M to build the financial infrastructure for AI advertising
VC funds
- Varangians closes €10M fund to back Ukraine’s DefenceTech ecosystem
- Anterra Capital reaches $100M first close for fund III
- Wave Ventures closes €10M fund III to back early nordic founders
- BAE Systems commits €50M to scale European defence technology startups
- monday.com launches $200M venture arm for workplace AI
- AGI House Ventures alumni launch $25M MoE Capital fund for frontier AI
- Earlybird Venture Capital and AVP launch €500M European defence and dual use fund
- FPE Capital secures €46M cornerstone commitment for Fund IV
- Anti Fund closes $100M growth fund for frontier technology investments
News on the market
- ACI Worldwide joins EPI Company to bring Wero instant payments to more European merchants
- Now it’s official: Nuvei acquires Payoneer for $2.75B to build global commerce infrastructure
- eToro eyes acquisitions as it expands beyond trading into banking services
- Square launches 3.50% APY savings tier for sellers
- Rain adds native loyalty to stablecoin card programmes
- Ripple takes equity stake in Flutterwave to expand stablecoin payments in Africa
- Visa and Revolut scale Click to Pay across Europe and global markets
- Robinhood cuts 10% of workforce in organisational restructuring
- Revolut secures UAE payments licences ahead of market launch
- Nopan joins EPI Company to accelerate Wero adoption among enterprise merchants
- Helvo launches integrated banking platform for Swiss SMEs
- Mollie commits €350M to build pan-European financial infrastructure
- Microsoft selects Checkout.com to power EMEA digital payments
- Wise acquires Expatica to reach more global citizens
- Conio secures MiCAR licence to expand regulated digital asset services
And here some useful resources for everyone involved in the ecosystem:
Events you don’t want to miss
- Swiss fintech week | Zurich | 19-25 June (link here)
- We make future | Bologna | 24-26 June (link here)
- Dutch blockchain week | Amsterdam | 22-28 June (link here)
You have a cool event you want to mention or to sponsor? Feel free to send me a DM.
Founders to watch in fintech
I also wanted to start shining a light on the most interesting fintech founders out there, so I thought to start sharing how I look for ideas to invest on. Every week, I will start sharing the most interesting founders in fintech, divided per area.
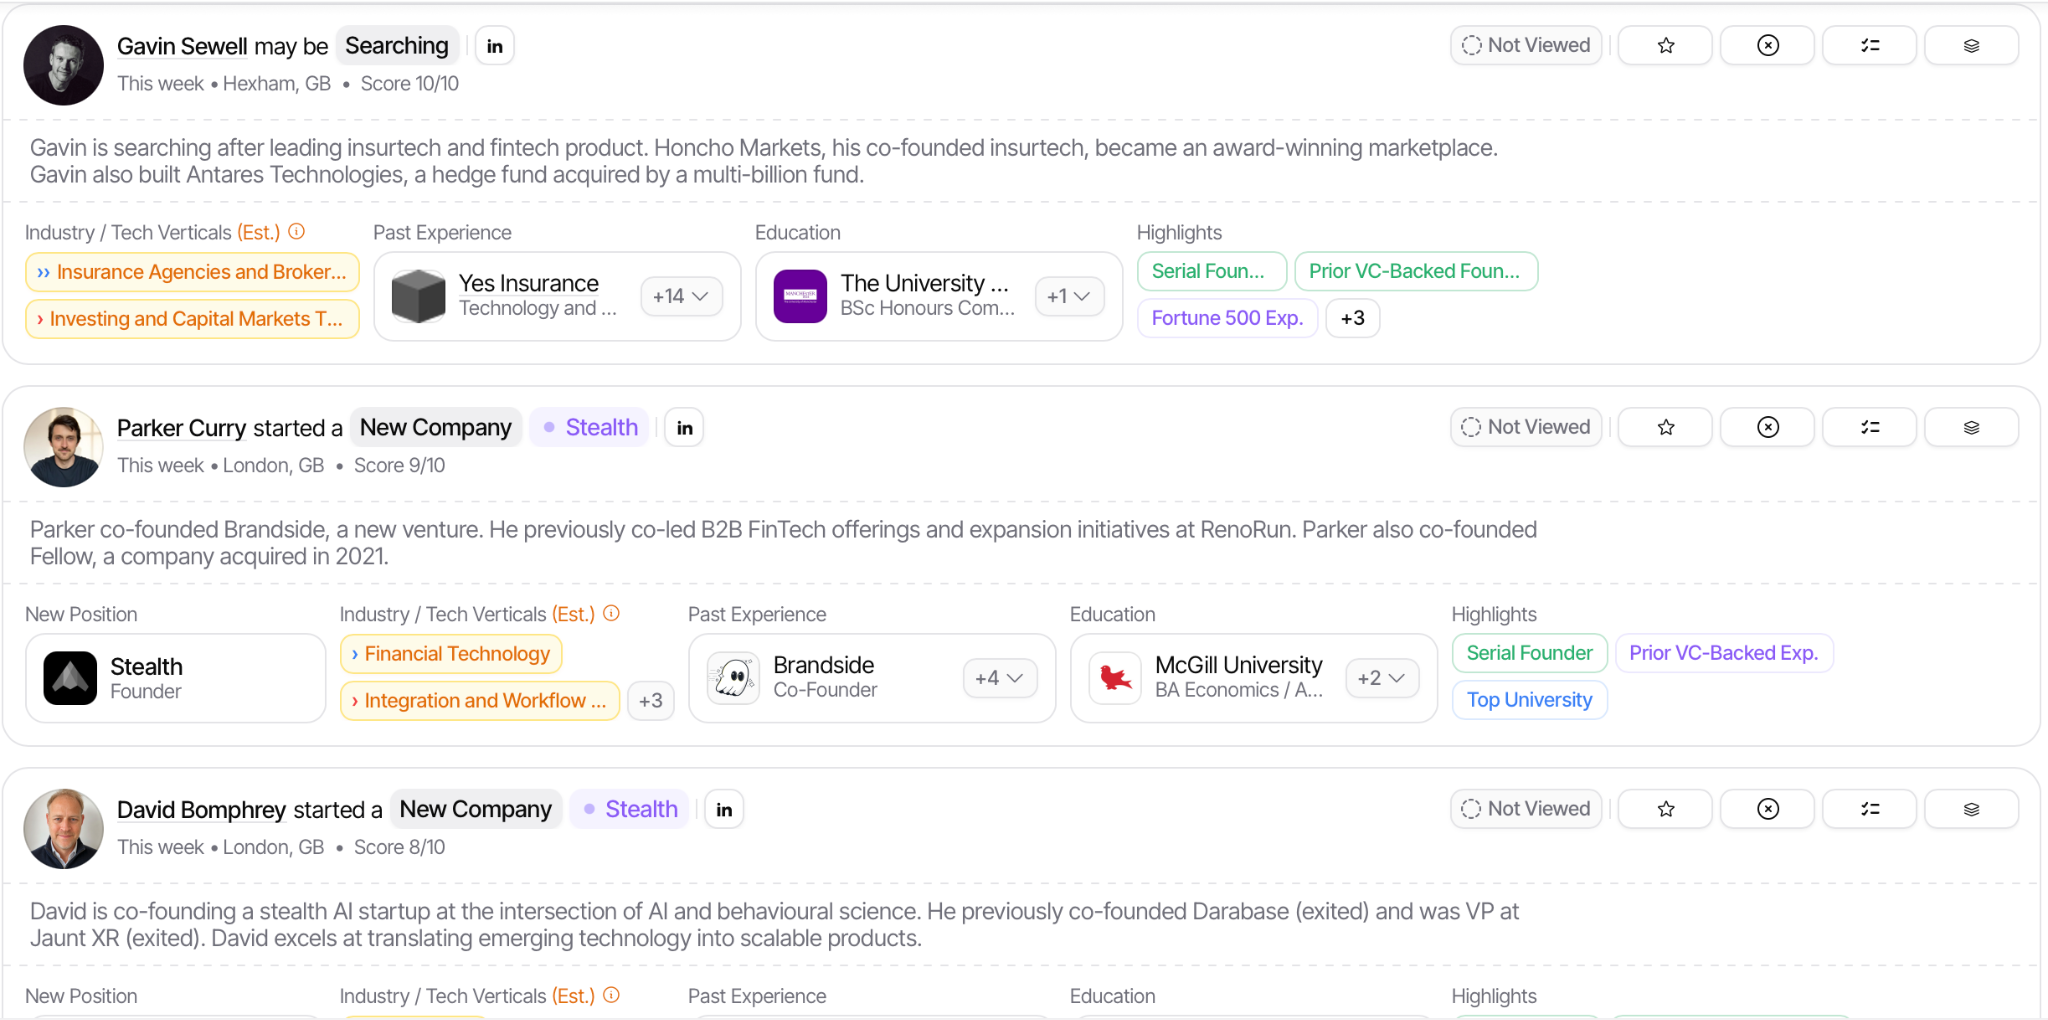
This week I am taking a look at the most interesting fintech founders in the UK! And you can already see a couple of interesting founders in stealth!
I usually use Spectre to scout for new ideas, the team is great and they also give me a free account once they learned I was a fan of the product. So if you wanna take a look at it, you can find it here.
VCs and PEs raising new funds now
I would like to leave this part of the newsletter as space for VC and solo GP that are launching new funds right now. I frequently speak with GPs and LPs, and I like the idea of giving them a showcase where to announce what they are doing. Here the new funds raising right now that I have been talking with:
- Parallax Ventures, a fintech VC fund focused on Latam. They closed Fund I with a strong +50% IRR and 0.7x DPI, and are now raising Fund II. Take a look here if you want to know more or reach out directly to the GP at gennari@parallax.vc for details.
- Founder Factor, VC focused on YC companies, that just closed investments on the latest YC W26. They are expanding the current vehicle to double down on the current batch. You can take a look here if you are interested.
- RedFish Capital Partners, a private equity investor focused on Italian SMEs in growth and mature capital phases, with a track record exceeding 40% IRR and with over €200M in Assets. Currently raising its brand new AIF, which has already secured a soft commitment from the European Investment Fund (EIF). You can check them out at redfish.capital or contact the team at investor.relations@redfish.capital.
Overall, very interesting to see where the VC ecosystem is heading recently, between new emerging managers, solo GP and micro funds.
Always happy to support if I can! If you are raising a fund and you want to be listed here send me a message on Linkedin.
And finally, take also a look at the last edition of the newsletter, Weekly update #136
Topics
Related funding
| Company | Round | Amount | Date |
|---|---|---|---|
| Flyweel Added · · Weekly update #137 | Pre-seed | 2,410,000 AUD | 18 June 2026 |
| Cortea Added · · Weekly update #137 | Seed | 12,000,000 EUR | 17 June 2026 |
| Festina Finance Added · · Weekly update #137 | Growth | 25,000,000 EUR | 17 June 2026 |
| El Dorado Added · · Weekly update #137 | Series A | 9,000,000 USD | 16 June 2026 |
| Green-Got Added · · Weekly update #137 | Equity crowdfunding | 8,000,000 EUR | 17 June 2026 |
| Clip Added · · Weekly update #137 | 500,000,000 USD | 9 June 2026 | |
| Range (stablecoin compliance) Added · · Weekly update #137 | Series A | 8,300,000 USD | 18 June 2026 |
| Causa Prima Added · · Weekly update #137 | Pre-seed | 10,000,000 USD | 16 June 2026 |
| Interchecks Added · · Weekly update #137 | Series C | 50,000,000 USD | 16 June 2026 |
| Waniwani Added · · Weekly update #137 | 8,000,000 USD | 15 June 2026 | |
| Receipts Depositary Corporation (RDC) Added · · Weekly update #137 | 7,000,000 USD | 16 June 2026 | |
| Flagright Added · · Weekly update #137 | Series A | 12,500,000 USD | 17 June 2026 |
| Trace Finance Added · · Weekly update #137 | Series A | 32,000,000 USD | 17 June 2026 |
| Karta Added · · Weekly update #137 | Series A | 15,000,000 USD | 17 June 2026 |
| Fraudio Added · · Weekly update #137 | 15 June 2026 | ||
| SyntheticFi Added · · Weekly update #137 | 13,000,000 USD | 9 June 2026 | |
| Sovra Added · · Weekly update #137 | Pre-seed | 2,000,000 USD | 16 June 2026 |
| WARREN (Belgium) Added · · Weekly update #137 | Seed | 10,000,000 EUR | 18 June 2026 |