Weekly update #132
The latest news from the fintech and VC ecosystems
Welcome to this edition of the weekly newsletter. The idea behind this is to gather all the information in the startup ecosystem in one place, with a special focus on the fintech market and the VC industry.
No episode of Builders has been released this week, but you can always recover the last one where I sit down with Rabea Bader, co-founder and CTO of Quidkey. You can watch the full episode here on YouTube, or listen to it here on Spotify or here on Apple Podcast.
Rabea is a fintech entrepreneur and CTO with a strong focus on payments infrastructure and account-to-account solutions. He is the Co-Founder and CTO of Quidkey, where he is building a secure, bank-integrated checkout experience that enables seamless domestic and cross-border A2A transactions while helping merchants reduce costs and banks unlock new revenue streams.
Prior to Quidkey, he served as CTO at REQPay Inc., where he co-invented a patented payments technology. His career also includes leadership roles as General Manager of Le Wagon in Israel and founding CEO of IZMUS. He began his professional journey as a backend developer at UBS, building a strong technical foundation in financial systems.
Rabea holds a degree in Computer Science and Economics from Tel Aviv University and brings a global perspective, with experience across the US, Israel, and Europe, and fluency in Arabic, English, and Hebrew.
With him, we will talk about cross border payments, how to validate your product when launching a new company, and also stablecoins and everything going on in fintech right now.
Keep your eyes open, next week my guest is Bhavin Shah, CEO and founder of Sherlocq, which launched this week in the UAE!
Coming back to us, I’ve been reading a very interesting report this week, the “Italy market snapshot - Q1 2026” from PitchBook. The report is a quantitative overview of the investment market in Italy, with a specific focus on Venture Capital and the startup ecosystem. Here my main takeaways:
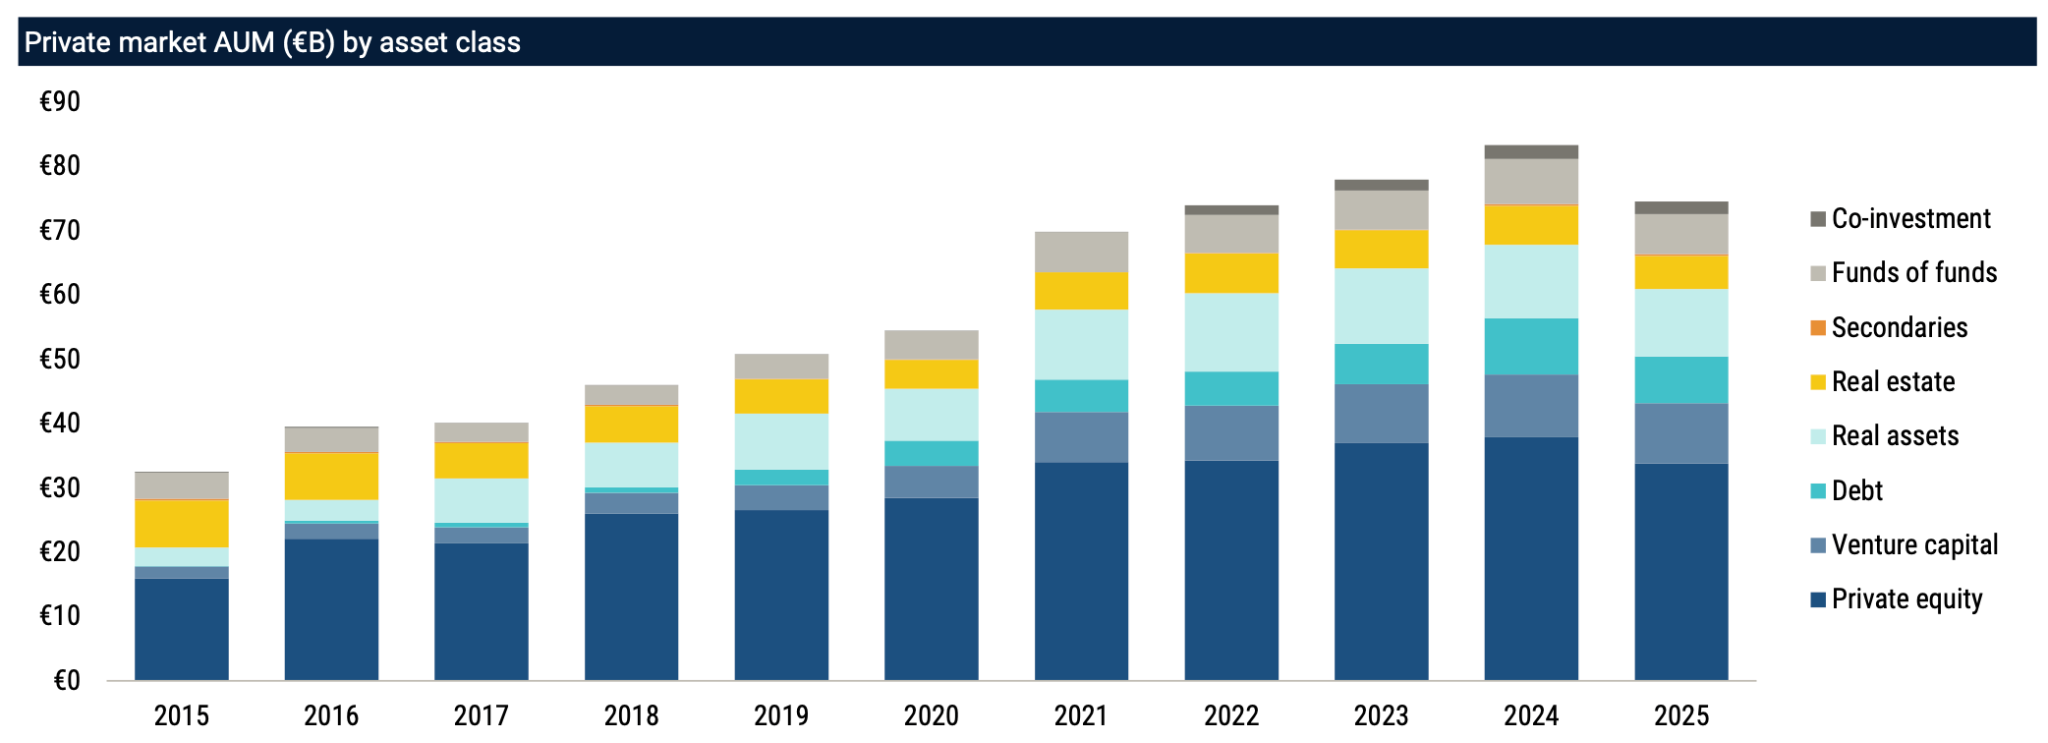
Italy’s private markets have expanded significantly over the past decade, with total assets under management rising from approximately €32 billion in 2015 to more than €74 billion in 2025, despite a slight decline from the 2024 peak. Private equity remains the dominant asset class, accounting for nearly half of total AUM and driving most of the market’s long term growth.
Venture capital and private debt have also gained momentum, particularly after 2020, reflecting stronger investor appetite for innovation financing and alternative lending strategies. Real assets and real estate continue to represent a meaningful share of the market, while funds of funds and co investments have maintained a stable presence. The data suggests Italy’s private capital ecosystem has become broader and more diversified, supported by increasing institutional participation and growing interest in alternative investments across sectors including infrastructure, technology, and mid market businesses.
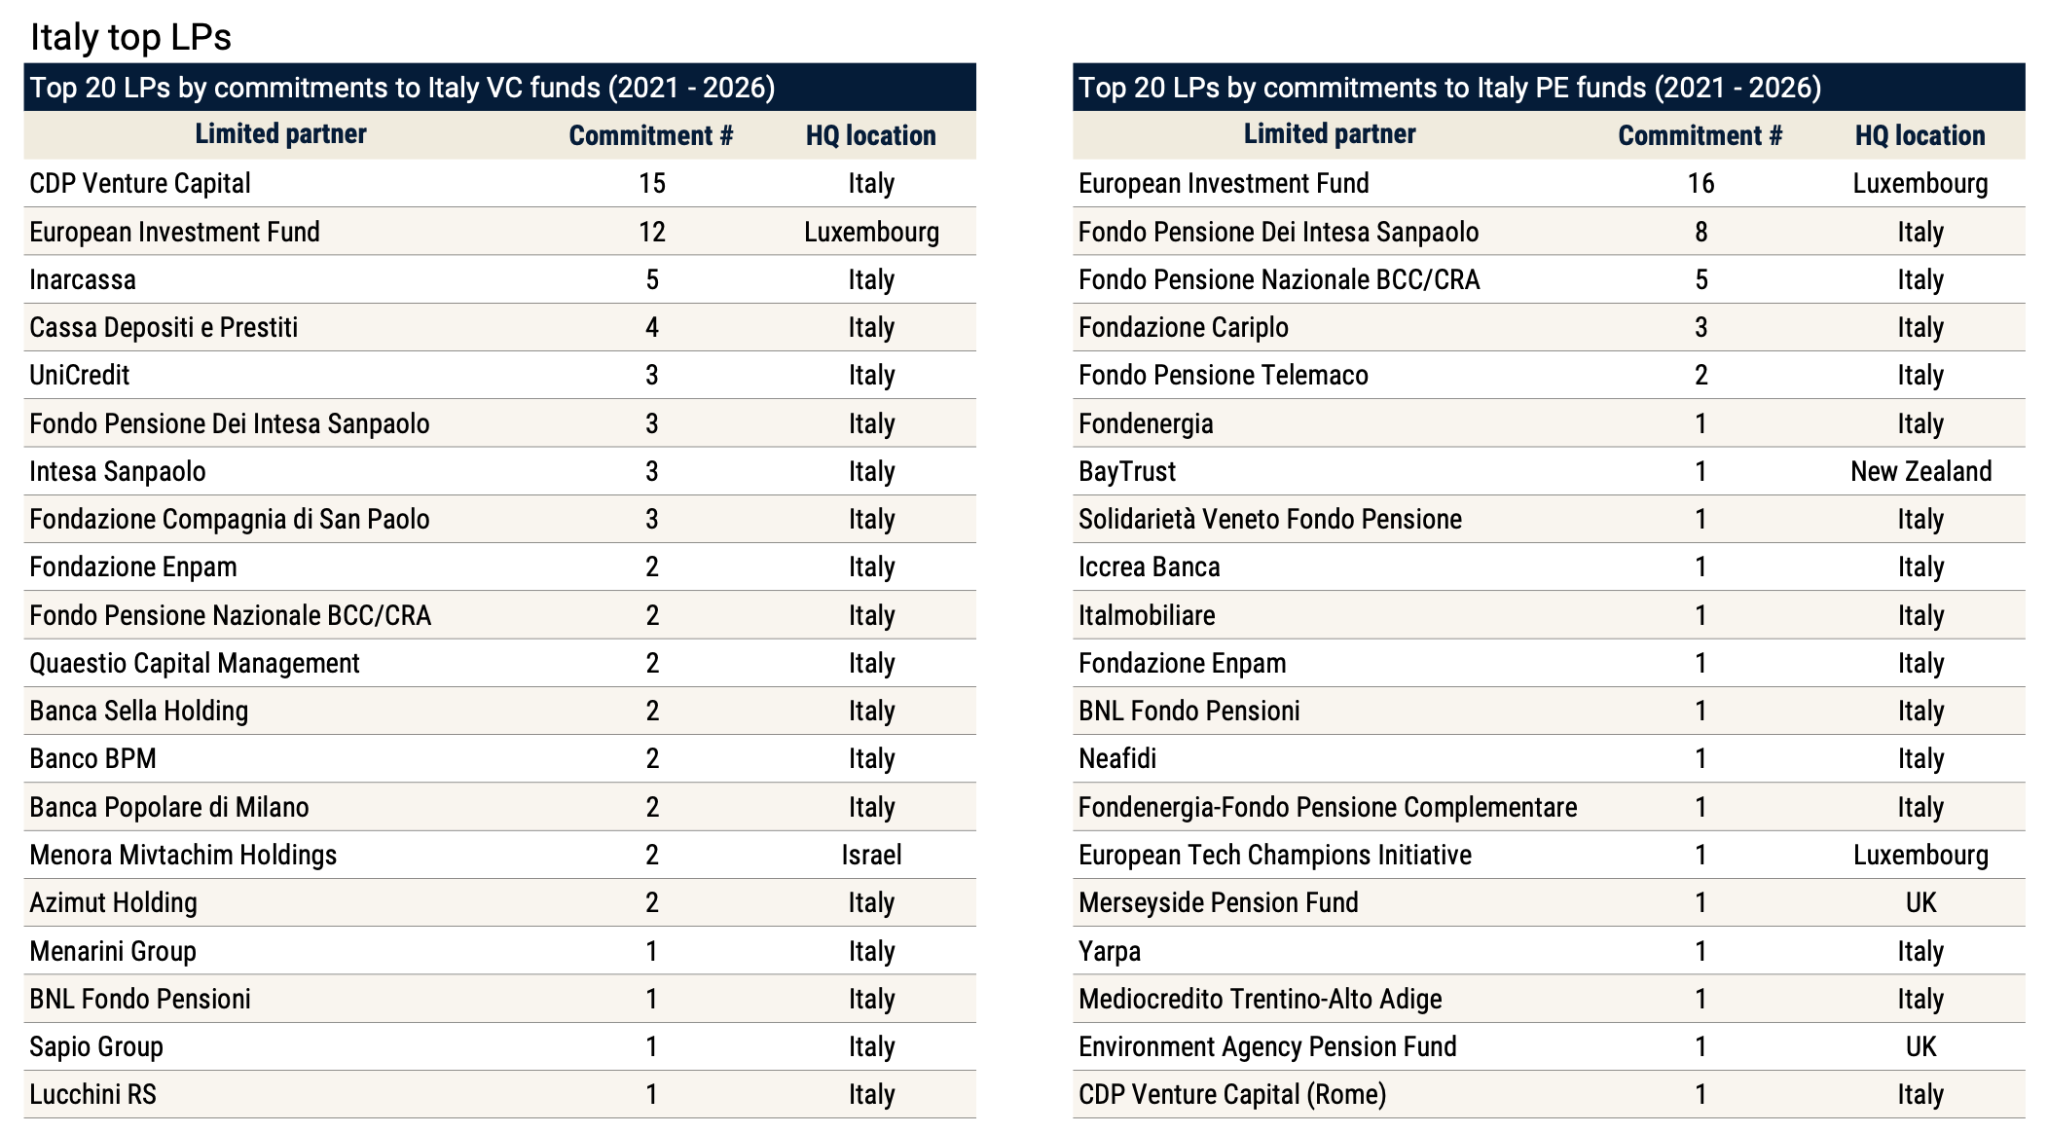
Funds are increasingly supported by a strong domestic institutional investor base, with pension funds, banks, foundations, and public entities playing a central role in both venture capital and private equity fundraising. Between 2021 and 2026, CDP Venture Capital led commitments to Italian VC funds with 15 commitments, followed by the European Investment Fund with 12, reinforcing the importance of public backed capital in the ecosystem.
Major Italian financial institutions including Intesa Sanpaolo, UniCredit, Banco BPM, Banca Sella, and Azimut Italia also emerged as active LPs. In private equity, the European Investment Fund ranked first with 16 commitments, while Italian pension funds such as Fondo Pensione Dei Intesa Sanpaolo and Fondo Pensione Nazionale BCC/CRA were among the most active domestic allocators.
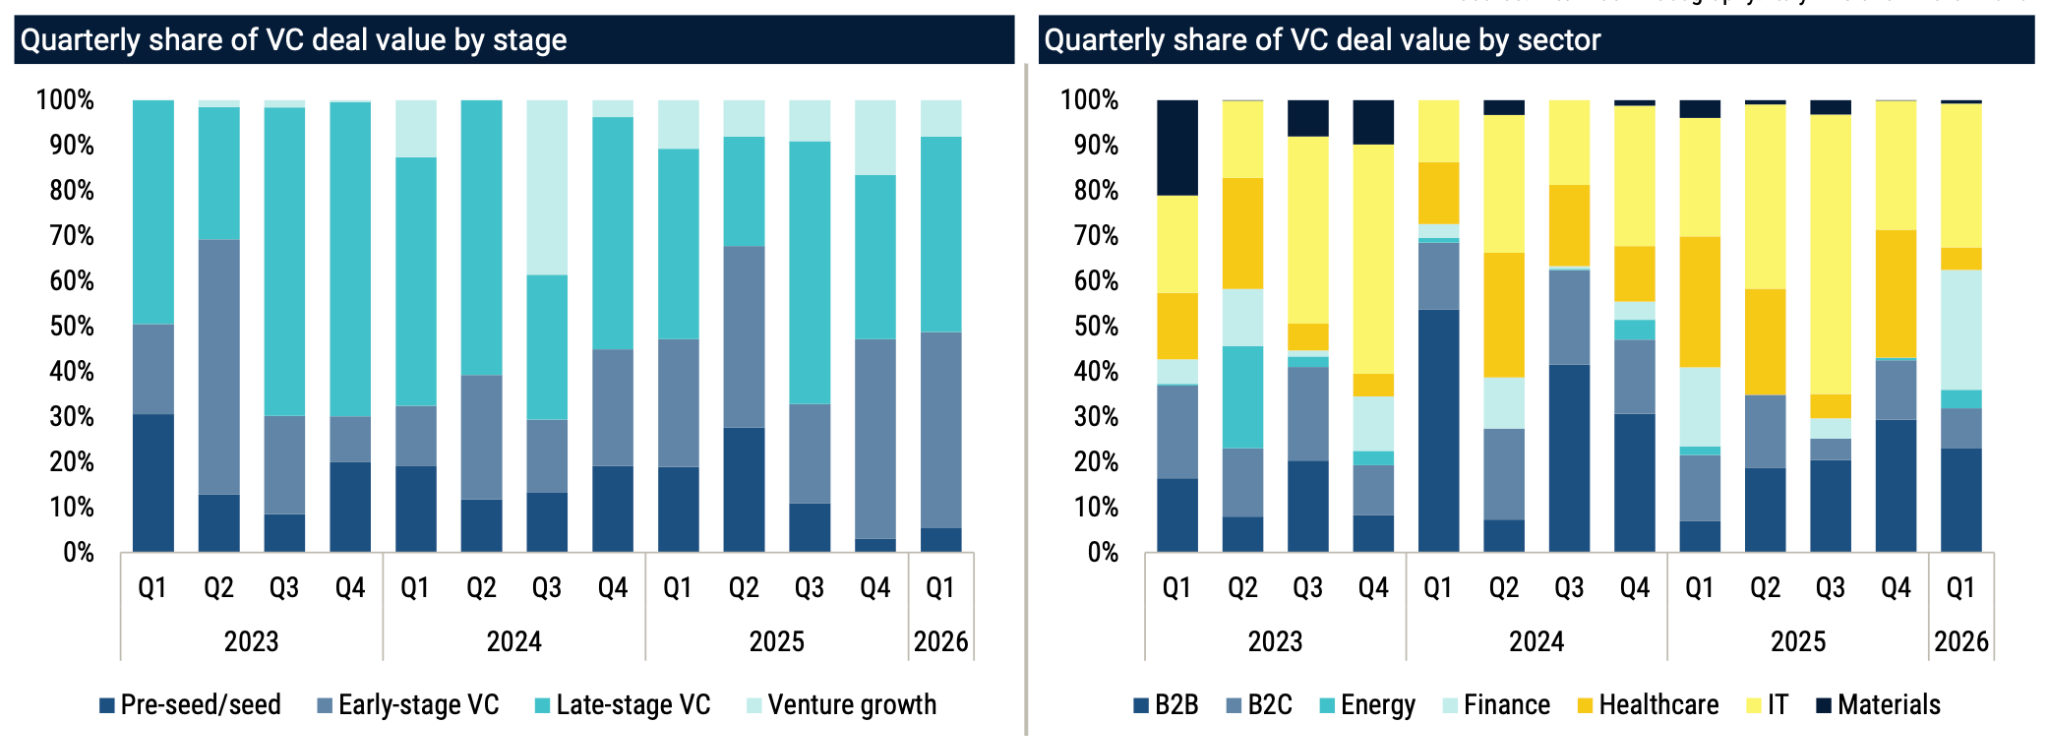
Italy’s venture capital market has shown significant shifts in both funding stages and sector allocation between 2023 and Q1 2026. Late stage VC consistently represented the largest share of deal value across most quarters, although early stage and seed activity gained momentum during 2025, pointing to renewed investor interest in emerging startups. Venture growth transactions remained relatively limited but became more visible in selected quarters, particularly during 2024.
From a sector perspective, IT and healthcare dominated deal value throughout the period, confirming continued investor focus on digital infrastructure, software, and health innovation. B2B investments also captured a meaningful share in several quarters, while finance and energy displayed more cyclical activity. The data suggests Italy’s VC ecosystem is becoming more diversified, with capital increasingly distributed across multiple growth sectors and company stages, reflecting a gradual maturation of the country’s broader private markets landscape.
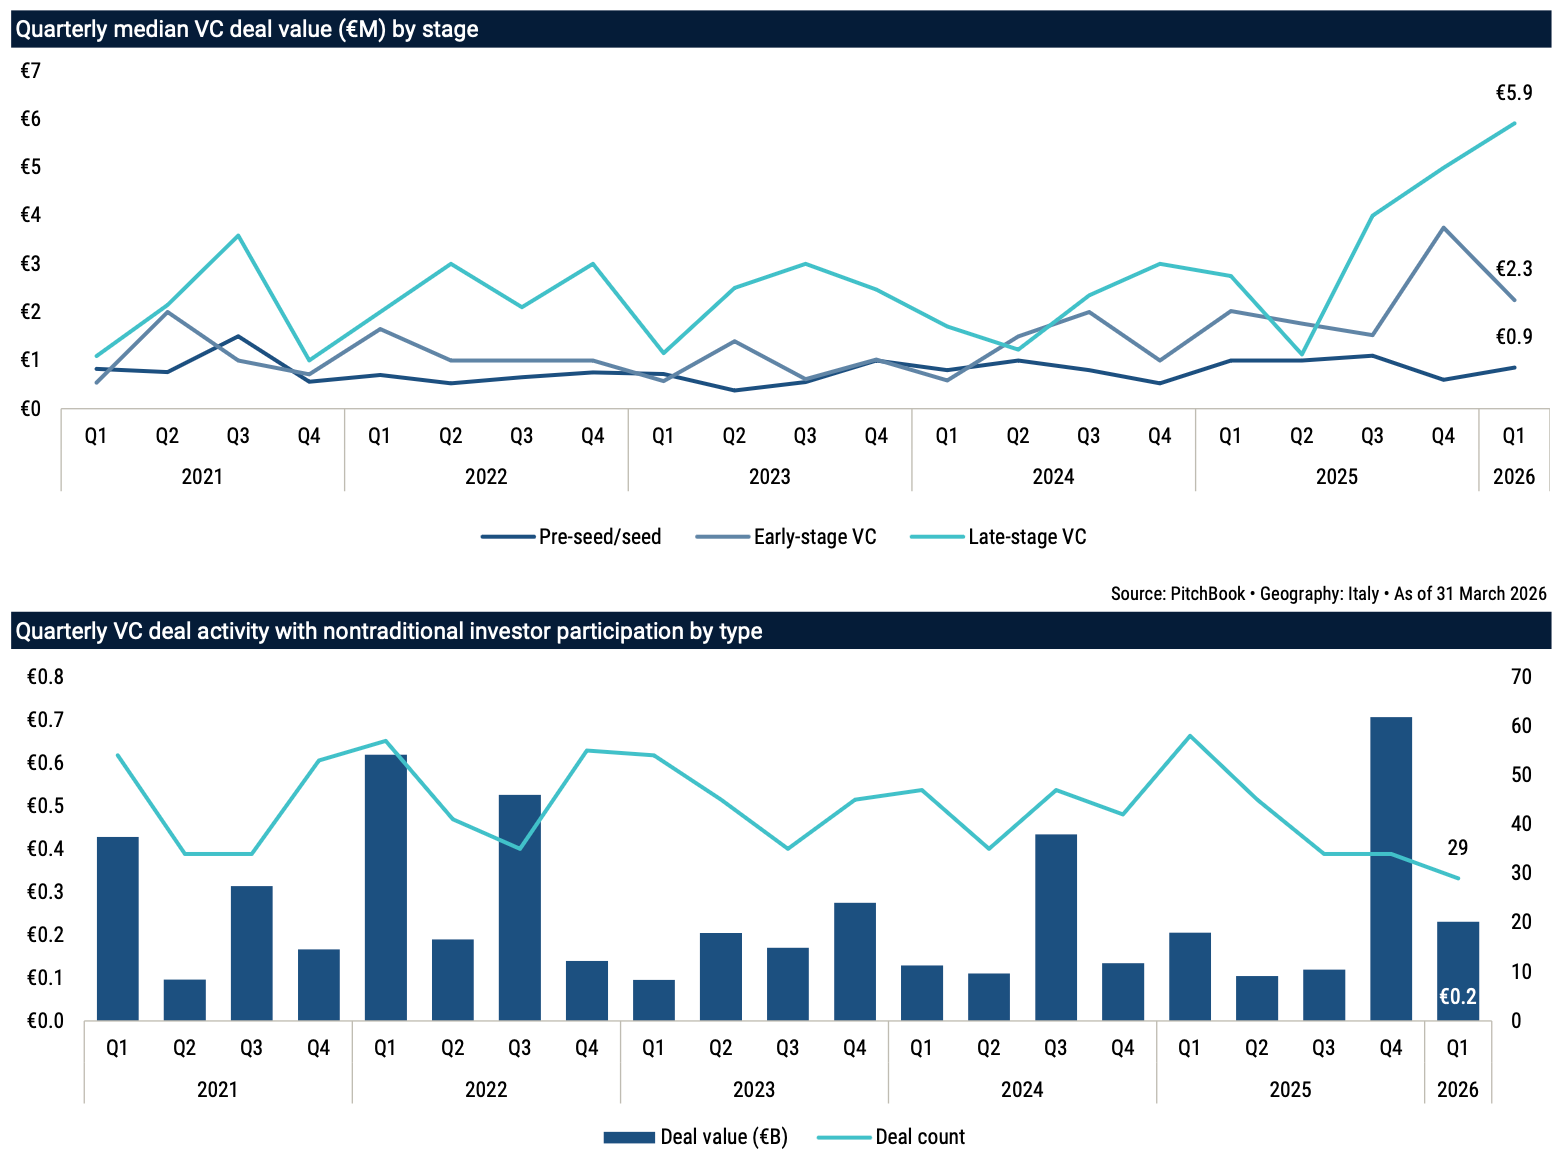
In terms of deal sizes, particularly in late stage financing rounds. By Q1 2026, median late stage VC deal value reached €5.9 million, significantly above early stage (€2.3 million) and pre seed or seed (€0.9 million) transactions, reflecting stronger capital concentration in more mature startups. Early stage activity also accelerated during 2025, suggesting improved investor confidence across the funding pipeline. At the same time, nontraditional investors continued to play an important role in the ecosystem.
VC deals involving corporates, asset managers, and other alternative investors showed fluctuating activity between 2021 and 2026, with notable peaks in both deal value and deal count during 2025. However, Q1 2026 recorded a decline in participation levels, with deal value falling to approximately €0.2 billion and deal count easing to 29 transactions. Overall, the data points to a maturing but still selective Italian VC environment.
But let’s take a closer look at the main news of the last seven days. bunq applied for a banking license in Mexico, Revolut received approval from UK regulators to expand in wealth management, ElevenLabs partners with Stripe in payments, Deel becomes Arsenal Football Club ’s sleeve sponsor and Adyen partners with SAP on embedded payments. But also, Corpay partners with BVNK on stablecoins, MoonPay acquires Dawn Labs to expand on trading infrastructure, Sherlocq launches in the UAE and Keel emerges from stealth. In the VC industry, lot of new funds this week, A\* closed a $450M fund, Mother Ventures closed a $10M inaugural fund, but also Ugly Duckling Ventures, Wisdom Ventures, Top Down, Kalos Ventures. And finally, some very interesting funding rounds from fintech startups like Fazeshift, Circle, Paymentology, Pillar, Embat, Elliptic, Guzco, Fasset and many others.
Let’s take a closer look:
Rounds
- Fazeshift raises $17M to build AI infrastructure for finance operations
- Circle raises $222M for Arc blockchain at $3B network valuation
- Ripple Prime secures $200M debt facility to expand institutional brokerage services
- Paymentology raises £129M to expand global issuer processing platform
- Italian startup Pillar raises €12M to digitize payments in construction operations
- Embat raises €30M Series B to expand AI driven treasury platform across Europe
- Adfin raises $18M to scale AI powered cashflow and payments platform
- Elliptic raises $120M Series D to expand AI powered digital asset compliance
- n8n reaches $5.2B valuation after strategic SAP investment
- Stream secures $5.2M extension to scale billing infrastructure across MENA
- Dutch fintech Guzco raises €1M to tackle chargebacks and first party fraud
- Osero raises $13.5M to expand stablecoin yield infrastructure for Sky Ecosystem
- LemFi reportedly preparing €30M series B extension following rapid growth
- Saudi fintech Stitch raises $25M series A led by Andreessen Horowitz
- Brazilian fintech Franq raises $12.4M series B to scale independent banking platform
- Boundary Labs raises $2M to launch institutional stablecoin protocol USBD
- DDD Invoices - One API, global invoicing compliance raises €1.31M to simplify global eInvoicing compliance
- Fasset raises $51M to scale stablecoin banking across emerging markets
- equipifi raises $34M series B to expand bank embedded BNPL network
- Ouinex reaches $9M in community funding and launches token platform
- Turnkey secures $12.5M strategic investment to expand crypto wallet and verifiable cloud infrastructure
- Secludy AI raises $4M seed round to bring privacy infrastructure to financial services AI
VC funds
- Mother Ventures raises $10M to back startups focused on the modern mother
- Wisdom Ventures launches $77.7M fund II focused on AI and human wellbeing
- Ugly Duckling Ventures The Nest fund II surpasses target with €35M raised for nordic B2B tech investments
- A\* Closes $450M third fund to back AI, fintech, and emerging founders
- S2G Investments closes $1B growth fund focused on food, energy and ocean innovation
- Top Down Ventures closes $28M fund I to back AI and software startups serving MSP
- Kalos Ventures closes $78.8M debut fund focused on workforce, care, and education infrastructure
- Skinos Ventures launches $26M fund to back AI driven cybersecurity startups
News on the market
- ElevenLabs expands Stripe partnership on payments as ARR surpasses $500M
- Commerzbank AG cuts 3,000 jobs amid UniCredit deal pressure
- Kraken parent Payward applies for U.S. national trust charter
- Keel emerges from stealth as profitable banking infrastructure provider
- Fintech startup Parker files for bankruptcy after raising over $200M
- Corpay integrates stablecoin infrastructure through BVNK partnership
- MoonPay acquires Dawn Labs to expand AI native trading infrastructure
- SoFi acquires PrimaryBid assets as UK retail investing platform winds down
- Sherlocq AI launches AI native regulatory intelligence platform for financial services
- Visa, Zilch and Thredd launch flexible card payment experience in the UK
- bunq expands global banking push with Mexican license application
- Revolut expands into wealth management after UK regulatory approval
- Deel expands Arsenal Football Club partnership with multi year sleeve sponsorship deal
- NAB acquires Banked : to expand real time A2A payments
- Adyen and SAP launch embedded payment infrastructure for SAP commerce cloud
And here some useful resources for everyone involved in the ecosystem:
Events you don’t want to miss
- Stablecon EMEA | Amsterdam - 19th-20th May (Link here)
- Money 20/20 | Amsterdam - 02-04 June (Link here)
- SuperReturns | Berlin - 08-10 June (Link here)
You have a cool event you want to mention or to sponsor? Feel free to send me a DM.
Founders to watch in fintech
I also wanted to start shining a light on the most interesting fintech founders out there, so I thought to start sharing how I look for ideas to invest on. Every week, I will start sharing the most interesting founders in fintech, divided per area.
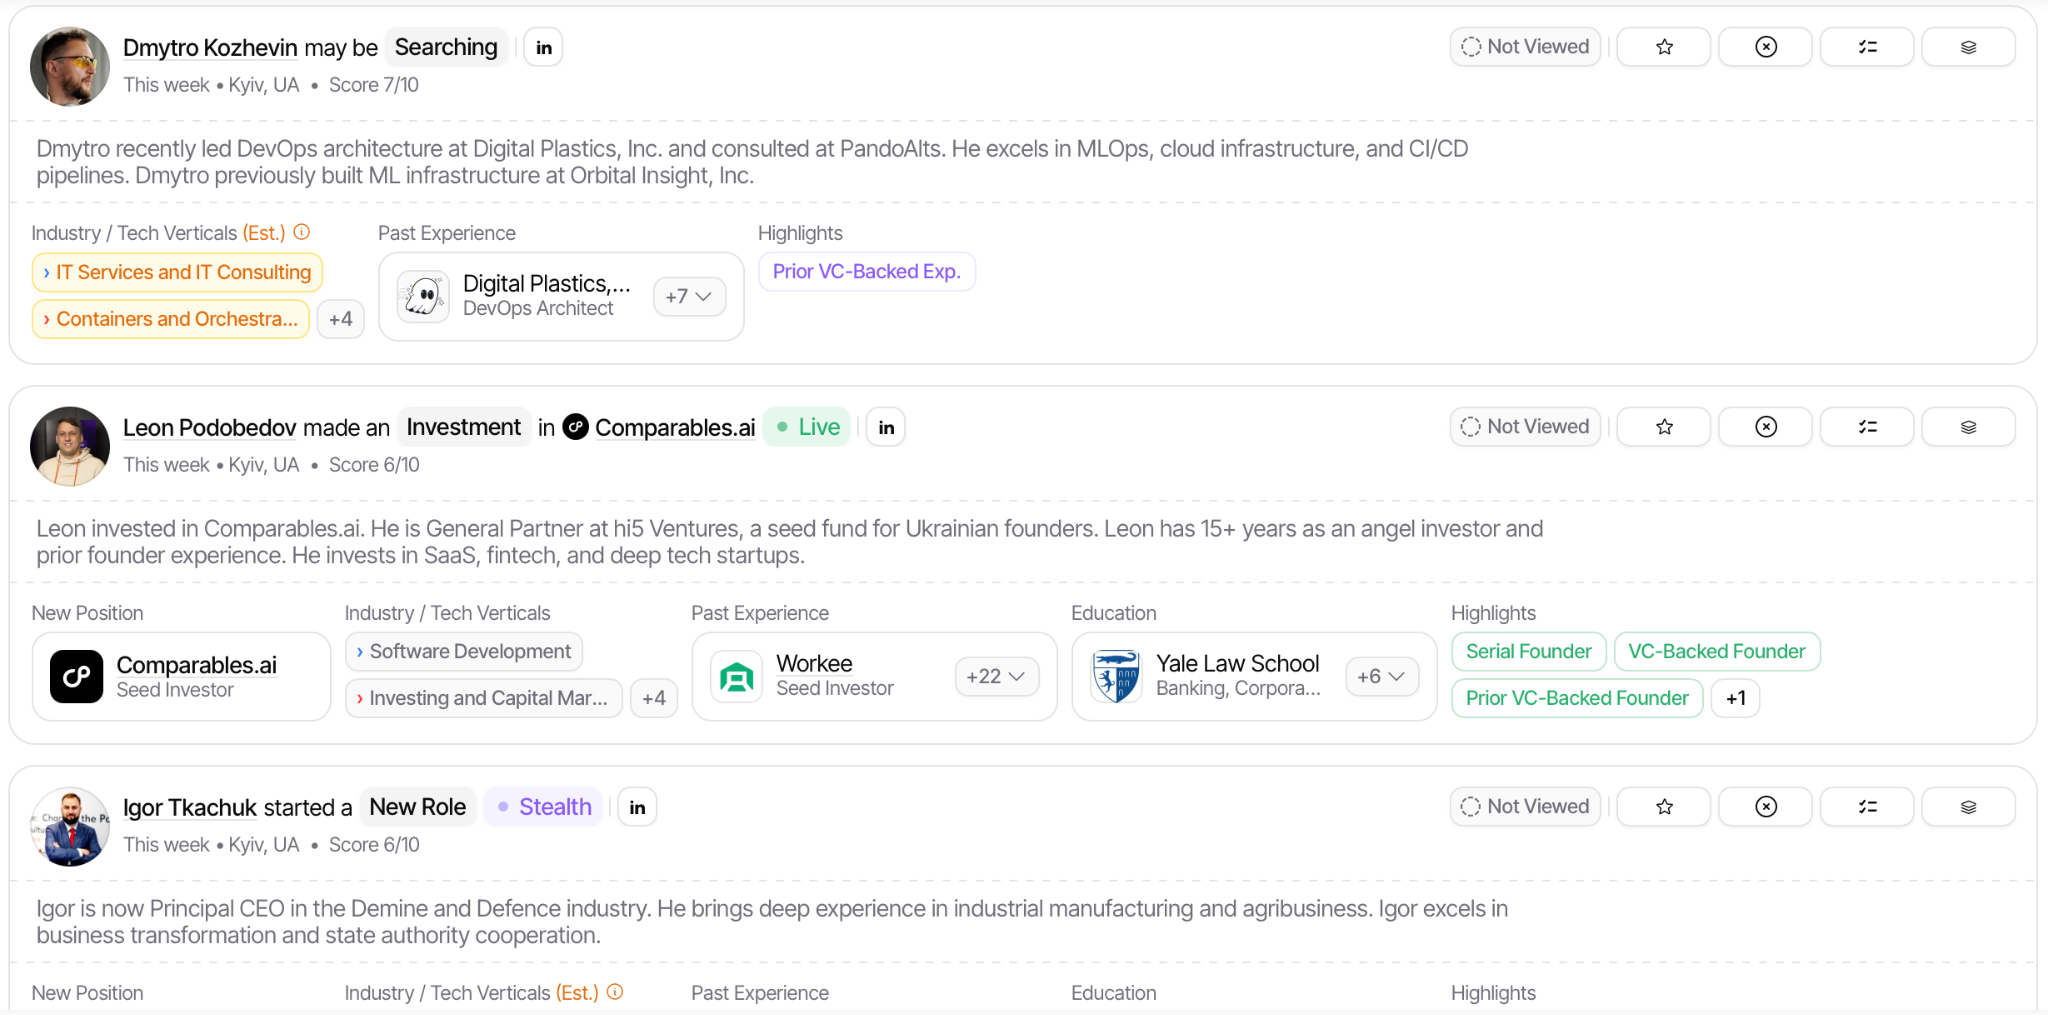
This week we take a look at the most interesting founders in fintech in Ukraine.
I usually use Spectre to scout for new ideas, the team is great and they also give me a free account once they learned I was a fan of the product. So if you wanna take a look at it, you can find it here.
VCs and PEs raising new funds now
I would like to leave this part of the newsletter as space for VC and solo GP that are launching new funds right now. I frequently speak with GPs and LPs, and I like the idea of giving them a showcase where to announce what they are doing. Here the new funds raising right now that I have been talking with:
- Parallax Ventures, a fintech VC fund focused on Latam. They closed Fund I with a strong +50% IRR and 0.7x DPI, and are now raising Fund II. Take a look here if you want to know more or reach out directly to the GP at gennari@parallax.vc for details.
- Founder Factor, VC focused on YC companies, that just closed investments on the latest YC W26. They are expanding the current vehicle to double down on the current batch. Partner is Marco Scotti, you can take a look here if you are interested.
- RedFish Capital Partners, a private equity investor focused on Italian SMEs in growth and mature capital phases, with a track record exceeding 40% IRR and with over €200M in Assets. Currently raising its brand new AIF, which has already secured a soft commitment from the European Investment Fund (EIF). You can check them out at redfish.capital or contact the team at investor.relations@redfish.capital.
Overall, very interesting to see where the VC ecosystem is heading recently, between new emerging managers, solo GP and micro funds.
Always happy to support if I can! If you are raising a fund and you want to be listed here send me a message on Linkedin.
And finally, take also a look at the last edition of the newsletter, Weekly update #131.
Topics
Related funding
| Company | Round | Amount | Date |
|---|---|---|---|
| Pillar (Italy) Added · · Weekly update #132 | Seed | 12,000,000 EUR | 12 May 2026 |
| Boundary Labs Added · · Weekly update #132 | Pre-seed | 2,000,000 USD | 11 May 2026 |
| Secludy AI Added · · Weekly update #132 | Seed | 4,000,000 USD | 13 May 2026 |
| Turnkey Added · · Weekly update #132 | Strategic | 12,500,000 USD | 14 May 2026 |
| Guzco Added · · Weekly update #132 | Pre-seed | 1,000,000 EUR | 13 May 2026 |
| Fazeshift Added · · Weekly update #132 | Series A | 17,000,000 USD | 7 May 2026 |
| Stream Added · · Weekly update #132 | Seed extension | 5,200,000 USD | 12 May 2026 |
| DDD Invoices Added · · Weekly update #132 | Seed | 1,310,000 EUR | 14 May 2026 |
| Ripple Prime Added · · Weekly update #132 | Debt facility | 200,000,000 USD | 12 May 2026 |
| Embat Added · · Weekly update #132 | Series B | 30,000,000 EUR | 12 May 2026 |
| n8n Added · · Weekly update #132 | Strategic | 13 May 2026 | |
| Fasset Added · · Weekly update #132 | Series B | 51,000,000 USD | 15 May 2026 |
| equipifi Added · · Weekly update #132 | Series B | 34,000,000 USD | 14 May 2026 |
| Stitch (Saudi Arabia) Added · · Weekly update #132 | Series A | 25,000,000 USD | 14 May 2026 |
| Paymentology Added · · Weekly update #132 | Growth | 175,000,000 USD | 12 May 2026 |
| Adfin Added · · Weekly update #132 | Series A | 18,000,000 USD | 12 May 2026 |
| Ouinex Added · · Weekly update #132 | 9,000,000 USD | 14 May 2026 | |
| Franq Added · · Weekly update #132 | Series B | 12,400,000 USD | 12 May 2026 |
| Elliptic Added · · Weekly update #132 | Series D | 120,000,000 USD | 12 May 2026 |
| Sky Ecosystem Added · · Weekly update #132 | 13,500,000 USD | 13 May 2026 |