Weekly update #124
The latest news from the fintech and VC ecosystem
Welcome to this edition of the weekly newsletter. The idea behind this is to gather all the information in the startup ecosystem in one place, with a special focus on the fintech market and the VC industry.
No episode of Builders has been released this week, but you can always recover the last episode, where I sit down with Sevan Marian, founder and CEO of Fleet. You can find the full episodes here on YouTube, or here on Spotify and here on Apple Podcast.
Sevan is a French technology entrepreneur and investor, currently serving as Co founder and Chief Executive Officer of Fleet, a Paris based company developing an operating system for workspace equipment management. Founded in 2019, Fleet provides an integrated platform that enables companies to lease, manage and renew IT equipment and office furniture through a subscription model. The platform combines hardware leasing, insurance, support services and device management tools, supporting more than 1,000 startups, scale ups and SMBs across Europe.
Before becoming CEO in 2025, Marian held the roles of Co founder and Chief Operating Officer and later Co CEO, leading Fleet’s operational growth and product development. Prior to Fleet, he served as Managing Director at GoMore, a European mobility platform with more than two million members across several markets, and earlier held leadership roles at Jumia Group in Morocco, where he oversaw the rapid expansion of the Jumia Market marketplace.
Alongside his entrepreneurial activity, Marian is an active technology investor with stakes in companies such as Stripe, OpenAI, Anthropic, SpaceX and Anduril Industries, as well as several early stage startups. He holds a Master in Management from EDHEC Business School.
Coming back to us, this week I’ve been reading a very interesting report, the “State of European Fintech 2026” from Finch Capital. The study is an overview of the current status of the European fintech market, with a strong comparison with other global fintech hubs like London and San Francisco, taking in consideration both funding trends and new companies. Here my main takeaways:
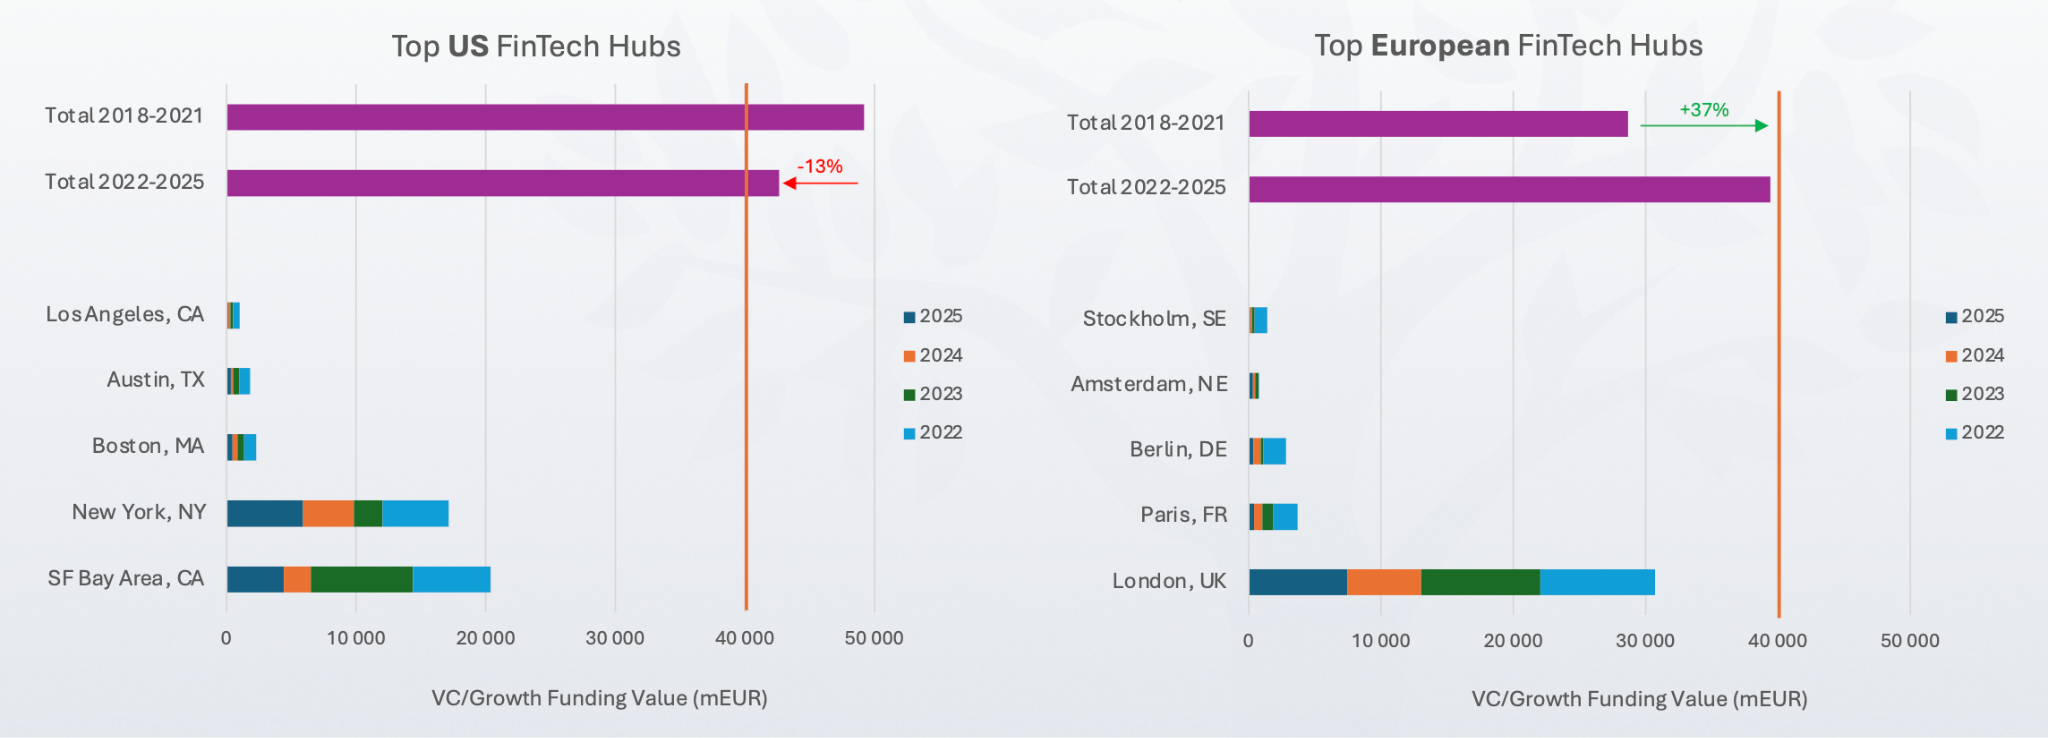
European fintech hubs are showing clear momentum relative to their US counterparts. Between 2022 and 2025, total VC and growth funding across leading European cities increased by approximately 37% compared to 2018–2021, reaching close to €40 billion. This contrasts with a 13% decline in US fintech funding over the same period. London remains the dominant hub, accounting for the majority of investment, followed by Paris and Berlin, while emerging centers such as Amsterdam and Stockholm continue to build traction.
The data suggests a rebalancing of global fintech capital allocation, driven by stronger growth dynamics in Europe and a more challenging funding environment in the United States. This trend reinforces Europe’s position as an increasingly competitive and scalable fintech ecosystem.
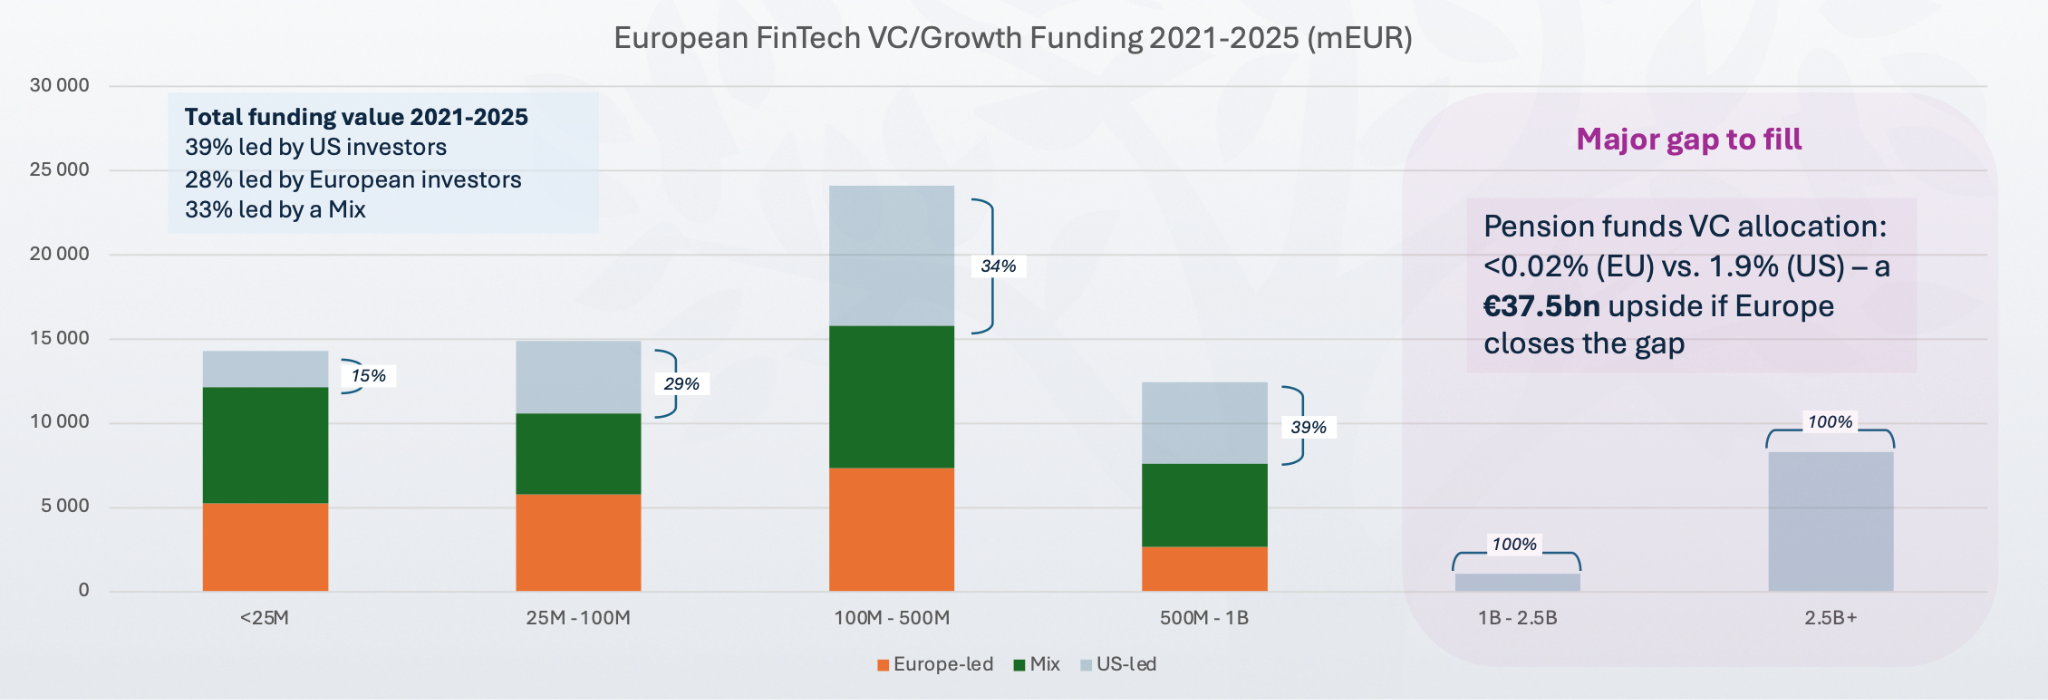
The real problem of the ecosystem is still the capital. European fintech funding between 2021 and 2025 shows a strong dependence on non-European capital, particularly in larger deal sizes. Overall, 39% of funding is led by US investors, compared to 28% led by European investors and 33% involving mixed participation. While European investors remain active in smaller rounds below €25 million, their presence declines as ticket sizes increase, with US-led participation reaching 39% in €500 million to €1 billion deals and dominating transactions above €1 billion.
This imbalance is further reflected in institutional allocation, as European pension funds invest less than 0.02% in venture capital versus 1.9% in the United States. Closing this gap could unlock an estimated €37.5 billion in additional capital, representing a significant opportunity to strengthen Europe’s late-stage fintech ecosystem.
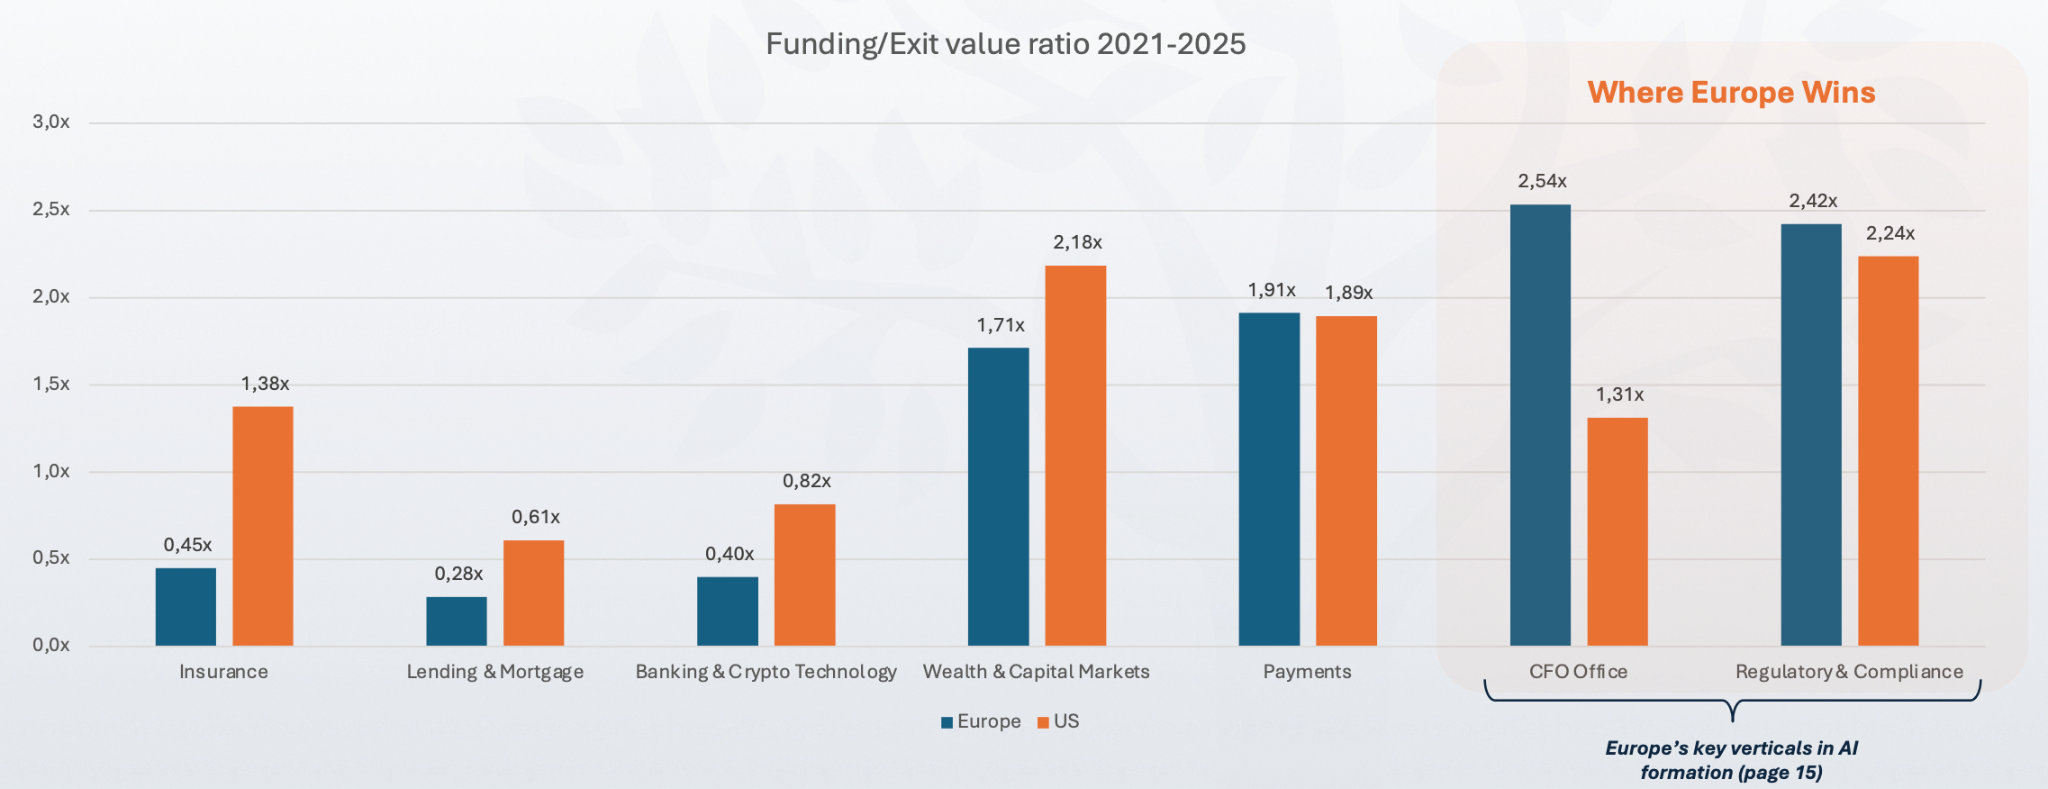
The funding to exit value ratio between 2021 and 2025 indicates a mixed but increasingly competitive performance for European fintech. While the US maintains stronger ratios in segments such as insurance at 1.38x versus 0.45x and lending at 0.61x versus 0.28x, Europe shows clear strength in more advanced and infrastructure driven verticals.
In CFO office solutions, Europe reaches 2.54x compared to 1.31x in the US, and in regulatory and compliance, 2.42x versus 2.24x. Payments remain broadly balanced at around 1.9x in both regions, while wealth and capital markets slightly favor the US at 2.18x against Europe’s 1.71x. Overall, the data suggests Europe is building stronger exit efficiency in AI driven and enterprise focused fintech segments, reinforcing its positioning in next generation financial infrastructure.
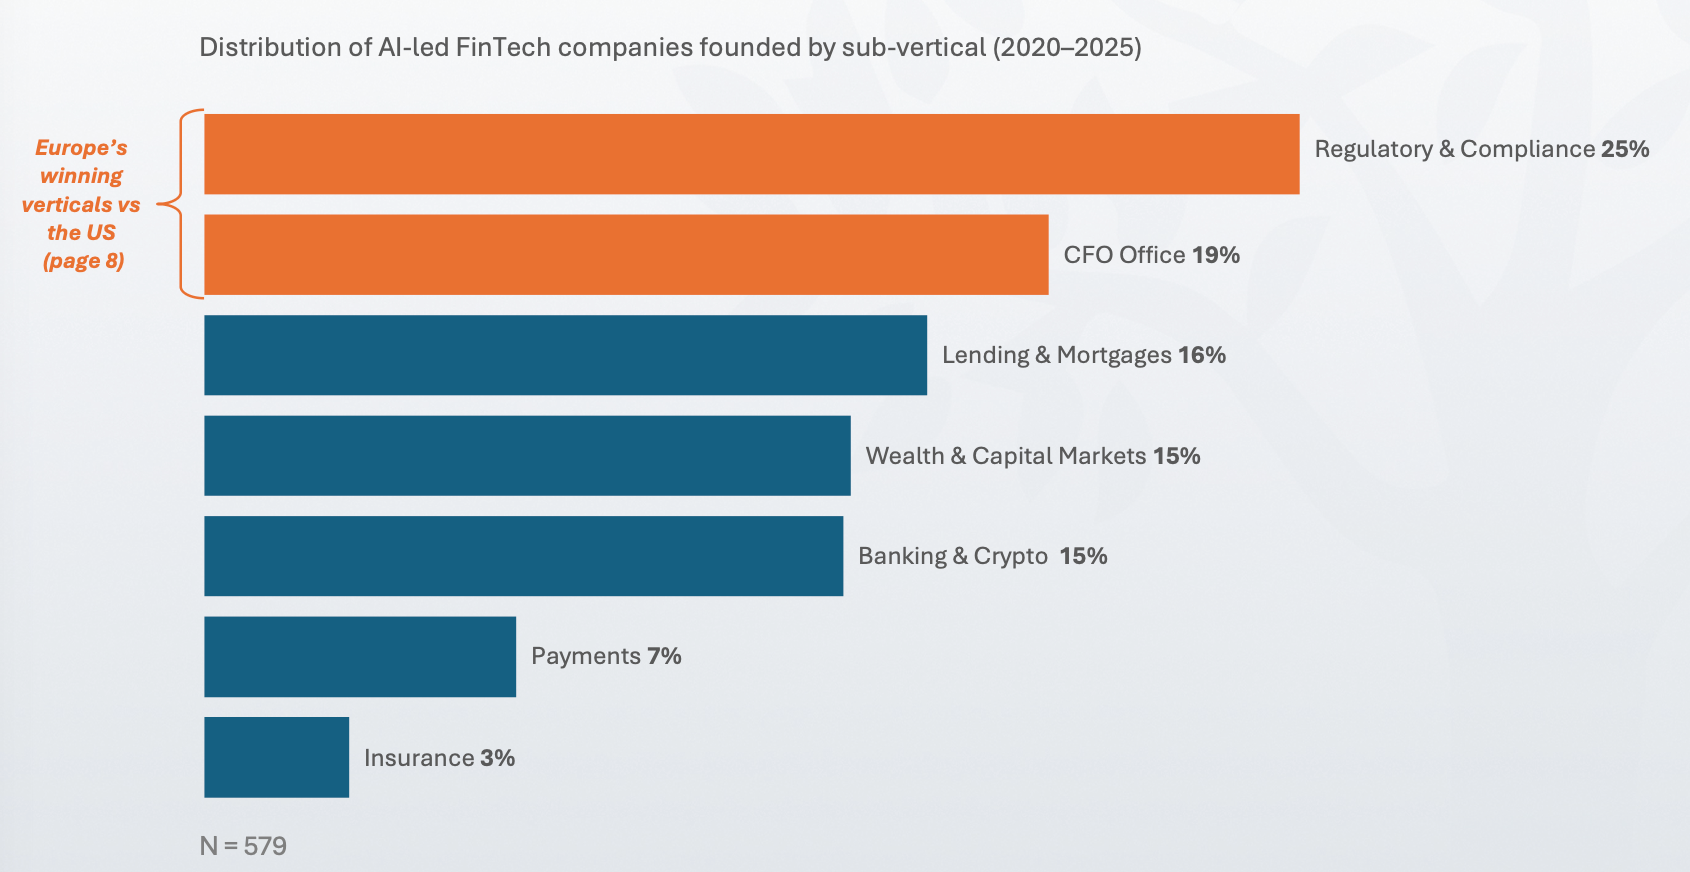
The distribution of AI-led fintech companies founded between 2020 and 2025 reflects a clear concentration in specific European strengths. Regulatory and compliance leads with 25% of companies, followed by CFO office solutions at 19%, reinforcing Europe’s focus on complex, enterprise-driven financial infrastructure. Lending and mortgages account for 16%, while wealth and capital markets and banking and crypto each represent 15%.
In contrast, more mature and commoditized segments such as payments and insurance remain relatively underrepresented at 7% and 3% respectively. Based on a sample of 579 companies, the data indicates that Europe is positioning itself at the forefront of AI adoption in regulation-heavy and operational finance domains, where technological differentiation and regulatory expertise create higher barriers to entry and stronger long-term competitive advantages.
But let’s take a closer look at the main news of the last seven days. European Union finally unveiled the long awaited EU inc, Revolut is trying to sponsor FC Barcelona, Mastercard acquires BVNK for $1.8B. But also, PayPal expands USDP to 70+ markets, Ramp acquires Juno, Isracard acquires esh, and the EU is asking Turkey to join SEPA. Lots of movements in the VC ecosystem! Main funds of the week were closed by Audeo Ventures, Boreal Ventures and Partech, but there were some new funds also from Speedinvest, Albion Capital Group LLP, SuperSeed and Gradient. And finally, some very interesting funding rounds from fintech startups like TransFi, Candex, Fuse, Upvest, VeryAI, dtcpay and many others.
Let’s take a closer look:
Rounds
- Teybridge Capital (Europe) Limited announces €5.2M UK expansion and €694.9M SME financing commitment
- VeryAI secures $10M seed round to build palm based identity verification on Solana
- MetaComp raises $44.45M to scale Web2.5 payments and stablecoin wealth infrastructure
- Onyx Security launches with $40M to build governance infrastructure for enterprise AI agents
- Valu invests $7M to enter Jordan as payments drive growth beyond BNPL
- German fintech Upvest secures $125M to accelerate European wealthtech infrastructure
- Steward Raises $5M to Automate Complex Investor Compliance With AI
- Alomana raises €4M to scale AI operating layer for enterprise workflows
- Fuse raises $25M to modernize loan origination systems for US credit unions
- Candex extends Series C beyond $40M with HSBC to simplify global vendor payments
- TransFi raises $19.2M to scale stablecoin powered payments across emerging markets
- Kudwa raises $1.1M to expand AI driven financial intelligence platform in the Gulf
- Ironlight Group, Inc raises $21M Series A to build infrastructure for tokenized securities
- Svasti Microfinance raises $5.7M to scale AI lending and target ₹1,400 Crore AUM
- dtcpay secures $10M Series A to expand regulated stablecoin payments into Europe
- Homaio raises €3.6M to open carbon markets to retail investors
- Theo launches thUSD with $100M gold backed yield strategy
- Noru secures €560K to build AI native “Agentic Compliance” platform
- Obin AI raises $7M to deploy agentic AI workforce for financial institutions
- Cleavr secures €1M to automate accounts receivable with AI
- Argentinian fintech Rexi raises $1.2M pre seed to automate transaction reconciliation
VC funds
- Audeo Ventures closes $65M fund II to back early stage fintech and consumer startups
- Boreal Ventures launches $60M fund II to back Canadian B2B tech startups
- European Investment Bank (EIB) commits €40M to Speedinvest’s Africa focused fund to back tech startups
- Partech closes €300M impact fund to scale Europe’s climate and industrial tech leaders
- Albion Capital Group LLP closes oversubscribed £90M fund to back UK deeptech and healthtech scale-ups
- British Business Bank commits up to £50M to SuperSeed’s AI focused fund III
- Gradient raises $220M fifth fund to double down on early stage AI investments
- Redbud VC closes $25M fund II to back pre seed founders across North America
News on the market
- After months of back and forth, N26 investors and founders have finally signed Investor Agreement
- PayPay Corporation debuts on Nasdaq at $12.7B valuation following strong IPO performance
- Mastercard to acquire stablecoin infrastructure provider BVNK in $1.8B deal
- Ramp acquires Juno to expand business travel infrastructure for non employee workflows
- Kalshi integrates Cash App Pay to expand access to regulated prediction markets
- StoneX Group Inc. proposes all cash acquisition of CAB Payments at 95p per share
- Travel fintech Scapia in talks to raise $50–60M to scale credit card and booking platform
- Isracard acquires digital bank esh in $130M deal
- PayPal expands PYUSD to 70 markets, scaling stablecoin powered global payments
- EU Commission finally unveils “EU Inc.”, the long awaited 28th corporate regime for startups
- Stripe backed Tempo launches Machine Payment Protocol, to let AI agents to pay using fiat and crypto
- European Union proposes Turkey’s entry into SEPA to reshape cross border payments
- Revolut and CaixaBank compete for FC Barcelona sponsorship deal
- Polymarket acquires Brahma to strengthen blockchain trading infrastructure
And here some useful resources for everyone involved in the ecosystem:
Events you don’t want to miss
- FIBE | Berlin - 15th-16th April 2026 (Link here)
- Stablecon EMEA | Amsterdam - 19th-20th May (Link here)
You have a cool event you want to mention or to sponsor? Feel free to send me a DM.
Founders to watch in fintech
I also wanted to start shining a light on the most interesting fintech founders out there, so I thought to start sharing how I look for ideas to invest on. Every week, I will start sharing the most interesting founders in fintech, divided per area.
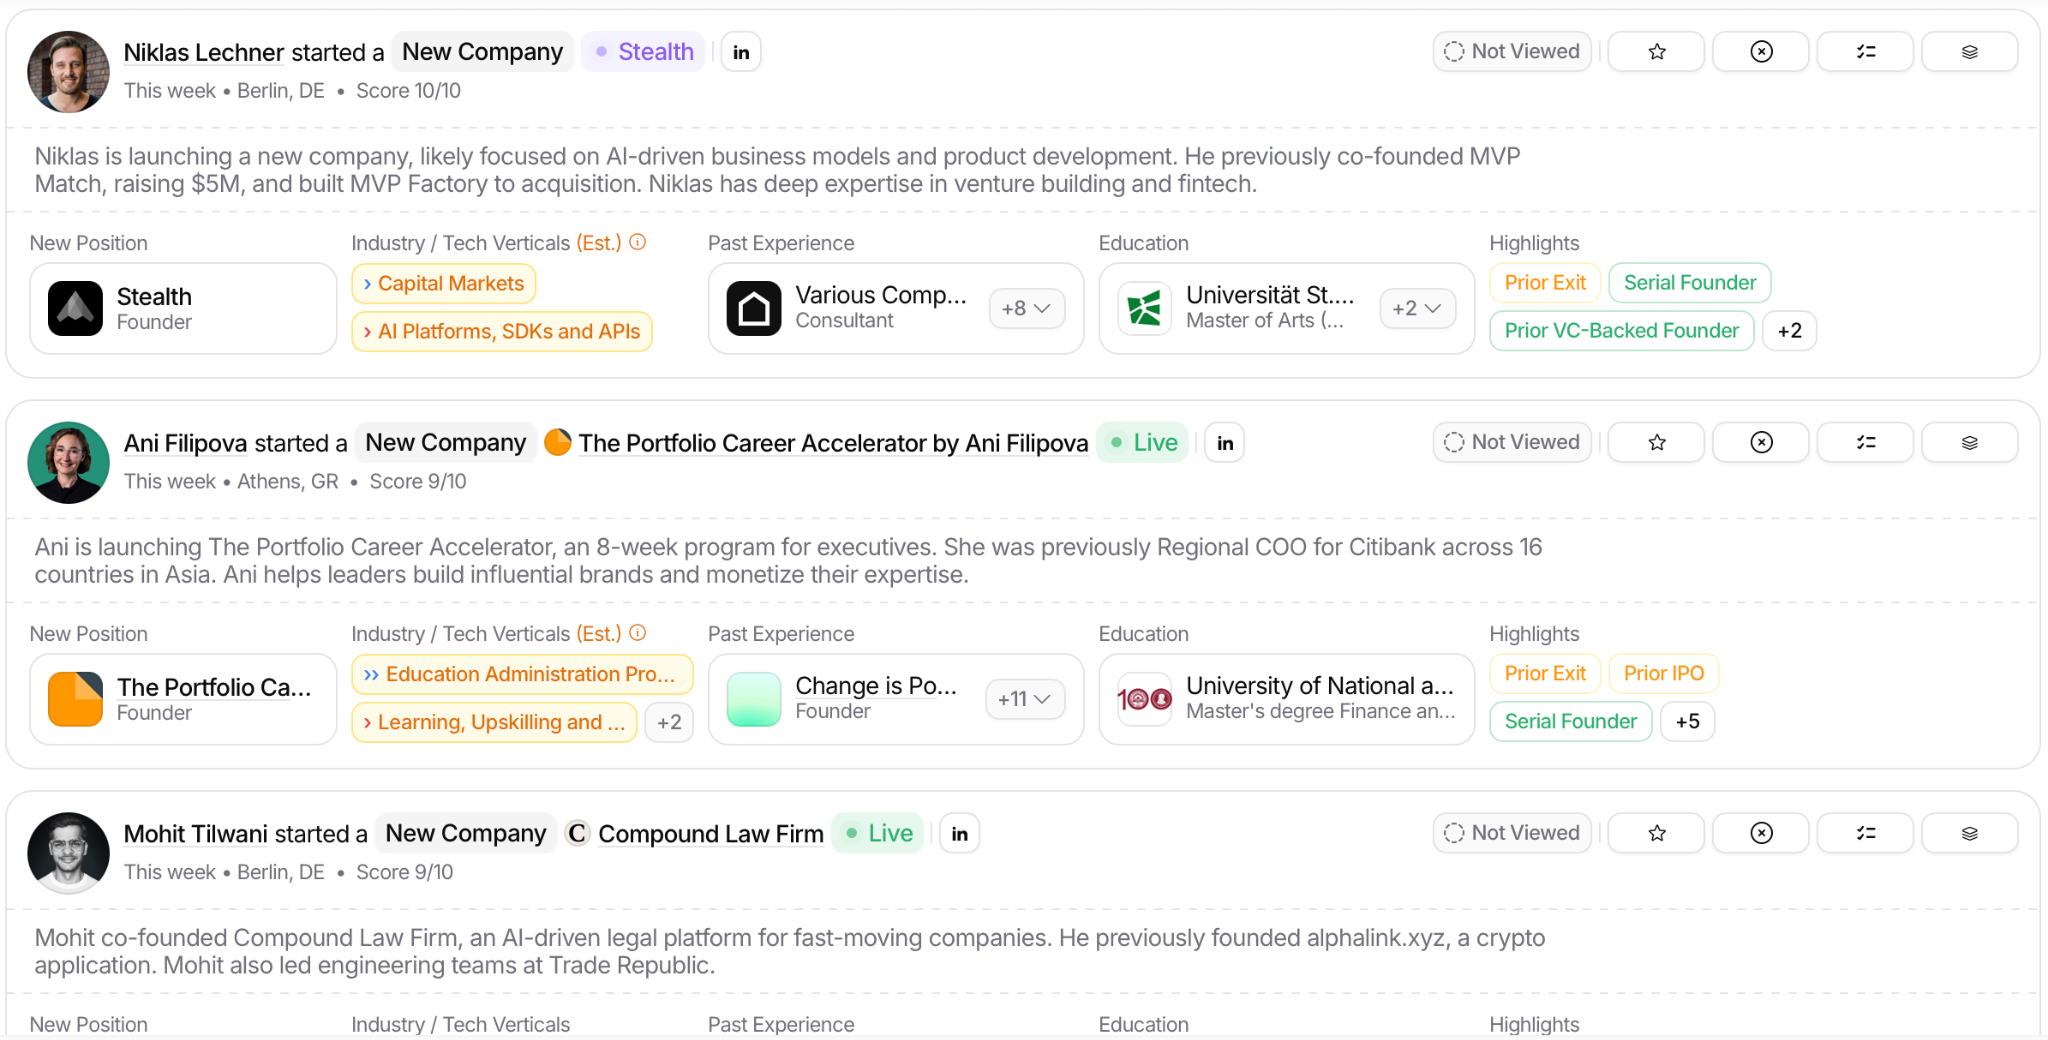
This week we take a look at the most interesting founders in fintech, in EU.
I usually use Spectre to scout for new ideas, the team is great and they also give me a free account once they learned I was a fan of the product. So if you wanna take a look at it, you can find it here.
New funds
I recently spoke with Marco Scotti from Raspberry Ventures. Thanks to their Y Combinator Alumni network, they unlock access to the top 10% of YC companies for Angel investors. Co-investing up to $3M across 15 - 25 companies in each YC batch, 4 batches a year, before Demo Day; and before the Silicon Valley VCs come in and take allocations in the best companies.
Their next batch YC W26m is closing in the upcoming weeks. You can take a look here if you are interested!
Take also a look at the last edition of the newsletter, Weekly update #123.
Topics
Related funding
| Company | Round | Amount | Date |
|---|---|---|---|
| TransFi Added · · Weekly update #124 | Series A | 14,200,000 USD | 17 March 2026 |
| dtcpay Added · · Weekly update #124 | Series A | 10,000,000 USD | 17 March 2026 |
| Ironlight Group, Inc Added · · Weekly update #124 | Series A | 21,000,000 USD | 16 March 2026 |
| Obin AI Added · · Weekly update #124 | Seed | 7,000,000 USD | 18 March 2026 |
| VeryAI Added · · Weekly update #124 | Seed | 10,000,000 USD | 16 March 2026 |
| Noru Added · · Weekly update #124 | Pre-seed | 560,000 EUR | 18 March 2026 |
| Upvest Added · · Weekly update #124 | 90,000,000 USD | 17 March 2026 | |
| Kudwa Added · · Weekly update #124 | Seed | 1,100,000 USD | 18 March 2026 |
| Alomana Added · · Weekly update #124 | Seed | 4,000,000 EUR | 17 March 2026 |
| Cleavr Added · · Weekly update #124 | Pre-seed | 1,000,000 EUR | 19 March 2026 |
| Rexi Added · · Weekly update #124 | Pre-seed | 1,200,000 USD | 24 March 2026 |
| MetaComp Added · · Weekly update #124 | Pre-A+ | 13,000,000 USD | 13 March 2026 |
| Steward Added · · Weekly update #124 | 5,000,000 USD | 17 March 2026 | |
| Homaio Added · · Weekly update #124 | Seed | 3,600,000 EUR | 18 March 2026 |
| Valu Added · · Weekly update #124 | 7,000,000 USD | 17 March 2026 | |
| Fuse Added · · Weekly update #124 | Series A | 25,000,000 USD | 16 March 2026 |
| Candex Added · · Weekly update #124 | Series C | 40,000,000 USD | 18 March 2026 |