Weekly update #109
The latest news from the fintech and VC ecosystem
Welcome to this edition of the weekly newsletter. The idea behind this is to gather all the information in the startup ecosystem in one place, with a special focus on the fintech market and the VC industry.
Builders is back with Season 3! In this episode, I sit down with Giorgio Seveso , founder and CEO of Tundr. You can find the full episode here on YouTube, or here on Spotify and here on Apple Podcast.
Giorgio is the CEO and founder of Tundr, the first Italian fintech platform active exclusively on corporate welfare with a dedicated account and payment card, able to handle everything for the company and the final user, from HR to payments.
Prior to Tundr, Giorgio started his career in consulting, at JAKALA first and Deloitte later, doing M&A and strategy for financial institutions. He launched Tundr in 2022 exactly because of those experiences, as he saw first hand how difficult it was to handle welfare in Italy for complex institutions.
With him, we will talk about the experience of a first time founder in Italy, the fintech ecosystem in the country, but also why not scaling globally from day 1 and how to be a champion in your niche.
Coming back to us, I’ve been reading a very interesting study this week, “The Brazil Stack: Brazil’s financial evolution” by Valor Equity Partners. Brazil has emerged as a global leader in digital finance through its integrated “Brazil Stack,” combining Pix instant payments, Open Finance, stablecoins, and AI-driven services. Pix processed approximately 63 billion transactions in 2024, while Open Finance now enables data sharing for over 42 million individuals across more than 800 institutions. The report analyzes the evolution of this model through its main milestones. Here my main take aways:
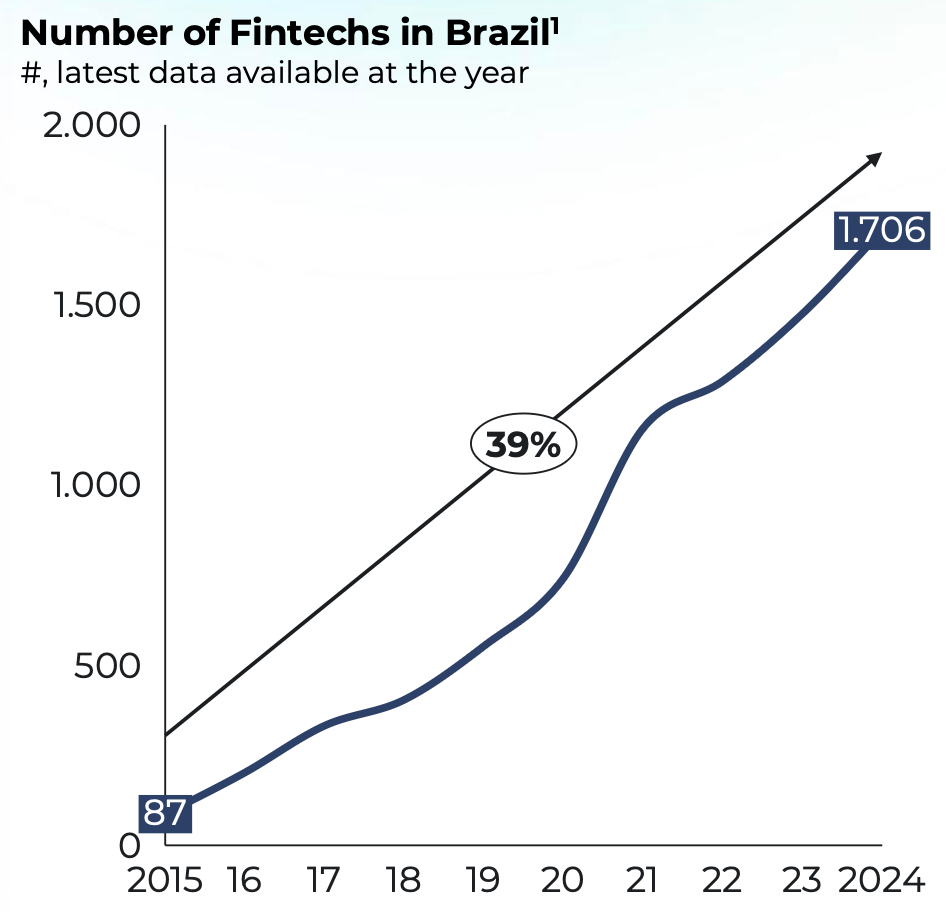
Let’s start from the basic. The data shows strong digitization of banking in Brazil, with digital banks reaching 55% share of current accounts in 2023 versus 45% for traditional banks. Brazil also leads Latin America in banking relationships, averaging 4.4 active relationships per customer in 2024, compared with Argentina and Mexico at 3.8, Colombia at 4.2, and Ecuador at 2.9. The fintech ecosystem expanded to 1,706 companies in 2024, with key segments including credit (304), back-office (256), payments (225), investments (125), crypto (113), and personal finance (73).
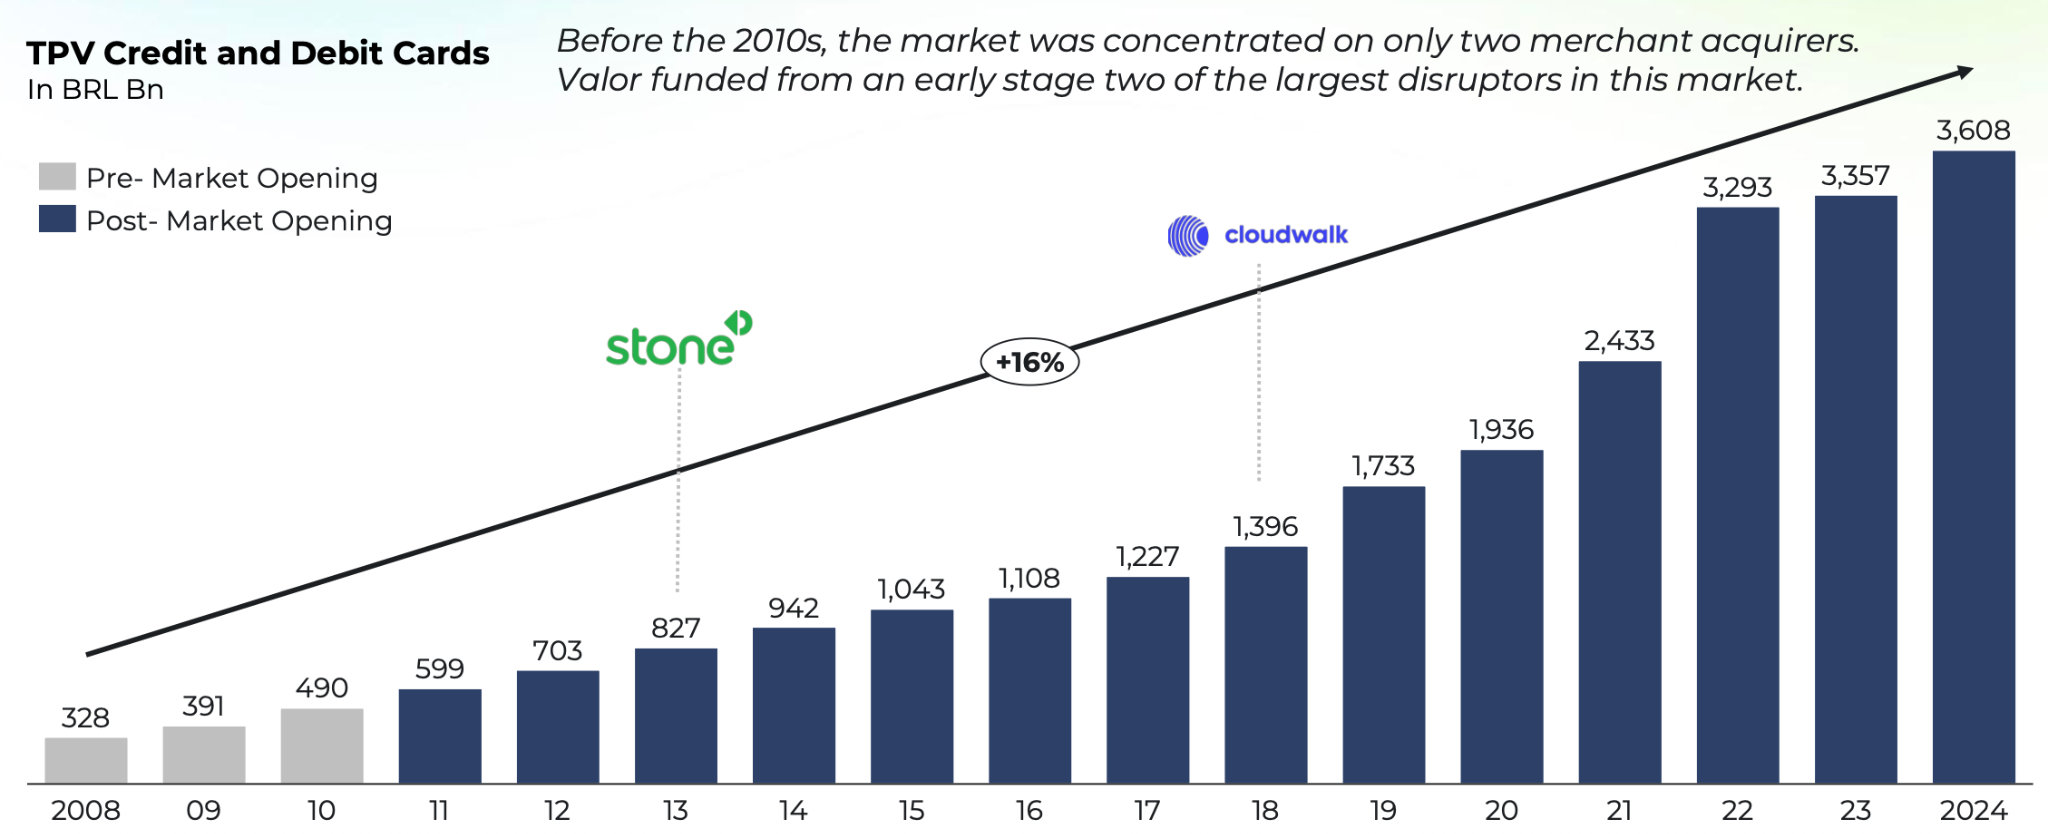
The dynamic of the market also shows a structural expansion of Brazil’s card payments market, with TPV for credit and debit cards rising from BRL 328 bn in 2008 to BRL 3,608 bn in 2024. Post-market opening volumes accelerated from BRL 599 bn in 2011 to BRL 3,293 bn in 2022 and BRL 3,357 bn in 2023, reflecting a sustained CAGR of around 16%. The period also coincides with the emergence of new acquirers, including Stone and CloudWalk, Inc. , reshaping market concentration and competitive dynamics.
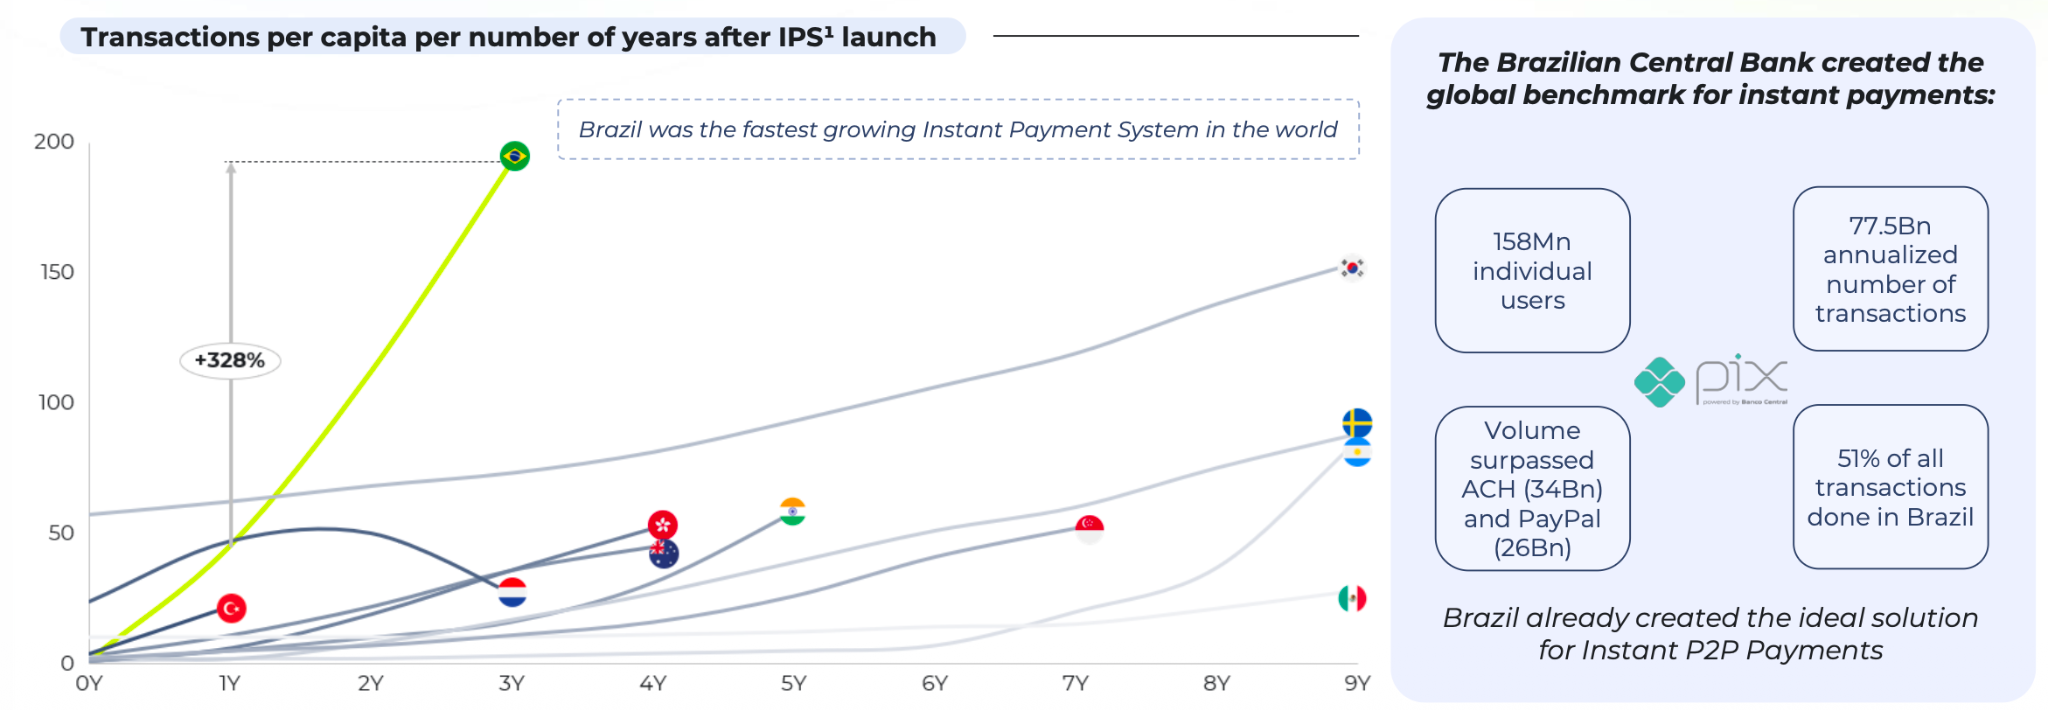
Brazil’s instant payments system shows exceptional scale and adoption, with transactions per capita rising more than 328% within the first year, making it the fastest-growing IPS globally. Pix now serves 158 million users and processes 77.5 billion annualized transactions, representing 51% of all transactions in the country. Its volume has already surpassed ACH at 34 billion and PayPal at 26 billion, positioning Brazil as a global benchmark for instant P2P payments and a central driver of the country’s fintech expansion.
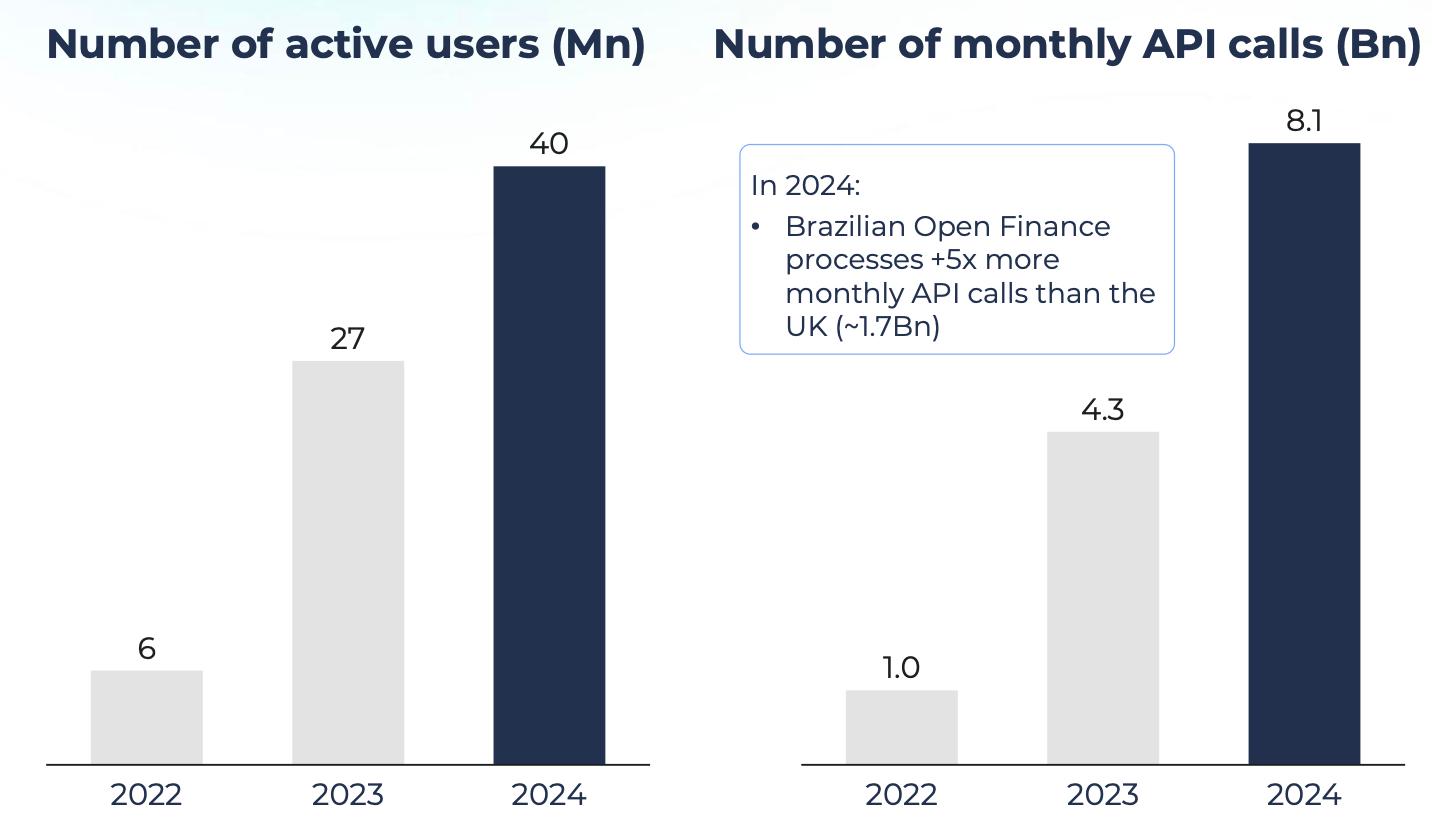
Brazil’s Open Finance system scaled rapidly between 2022 and 2024, with active users increasing from 6 million to 40 million. Monthly API calls rose from 1.0 billion in 2022 to 8.1 billion in 2024, reflecting strong platform adoption and infrastructure maturity. In 2024, Brazil processed over five times more monthly Open Finance API calls than the UK, which recorded approximately 1.7 billion, positioning Brazil as one of the most advanced and heavily used open finance ecosystems globally.
Anyway we saw a lot of interesting news this week. Revolut reaches a $75B valuation in landmark secondary deal, while at the same time making plans to land in Hong Kong. Checkout.com adopted OpenAI for enterprise agentic ecommerce, Kraken launched a 1% cashback credit card for Krak, Robinhood plans to launch a derivative exchange, while Stripe is facing pushback on banking license approval. But also, Klarna partners with Lufthansa, N26 launches personal loans in Spain and Ripple gets a license in UAE for its stablecoin RLUSD. In the VC ecosystem, Onstage launched a $10M fund, Firgun Ventures a $250M quantum fund and Future Energy Ventures a $235M green transition fund. But also Clover and Baobab Ventures. And finally, some very interesting funding rounds from fintech startups like BKN301, Numerai, erad, Pennylane, Higala, HelloTrade and many others.
But let’s take a closer look at the main news of the last seven days.
Rounds
- HelloTrade raises $4.6M to bring U.S. assets On-Chain for global investors
- Model ML raises $75M in major Series A to scale AI workflows for financial institutions
- Fintech startup Sencillo secures £350K+ pre-seed to expand education financing for UK Families
- pay.com.au raises $53M to accelerate US expansion and scale rewards-based payments
- BKN301 raises €32M and acquires Planky to deepen AI-driven fintech infrastructure
- Numerai raises $30M Series C at $500M valuation to scale AI hedge fund
- Wealthy raises Rs 130 Cr ($14.5M) to scale AI-driven WealthTech platform
- Pennylane nears $200M fundraise at $4.25B valuation to scale SME accounting across Europe
- Higala raises $4M to modernize rural banking infrastructure in the Philippines
- STAMP raises $2M to scale AI-driven regulatory compliance platform in Saudi Arabia
- Clara secures $70M debt facility to expand corporate payments in Mexico and Colombia
- Omnisient - Collaborative Consumer Intelligence secures $12.5M Series A to axpand privacy-safe alternative credit data in the US
- Opti launches AI-native identity platform after $20M Seed to automate enterprise IAM
- Square Yards raises $35M and advances toward $900M valuation and 2026 IPO
- erad secures $125M Jefferies-led facility to expand SME embedded finance across the GCC
- Tether.io invests in Brazil’s Parfin to expand institutional USDT adoption in Latam
VC funds
- Onstage launches £10M fund to scale Europe’s leading Demo Day
- Firgun Ventures launches $250M Quantum Fund with $70M first close backed by QIA
- Carles Reina launches $15M Baobab Ventures fund to back AI and defence startups
- Future Energy Ventures closes record €235M energy tech fund to back AI-driven grid and storage startups
- Clover launches €30M evergreen fund to back startups redefining work and education
News on the market
- Revolut reaches $75B valuation in landmark secondary deal
- Coinbase to acquire Vector to accelerate Solana-based onchain trading
- US Banks assess exposure after SitusAMC data breach impacts major institutions
- Exodus acquires W3C Corp for $175M to control end-to-end crypto payments
- Klarna just launched its proprietary stablecoin, KlarnaUSD
- Checkout.com adopts OpenAI-backed ACP to enable enterprise agentic commerce
- ABANCA and Revolut consider €100M bid for Singular Bank to enter private banking
- Smith Ventures to acquire Green Dot Corporation in $1.1B deal, reshaping embedded finance
- Paxos acquires FORDEFI for $100M+ to accelerate institutional DeFi expansion
- Kraken expands Krak with 1% cashback card, salary deposits and DeFi yield
- Stripe’s bank charter bid faces regulatory pushback as OCC reviews Bridge national trust plan
- Mastercard launches Access Pass in UAE with McLaren Racing and FAB to expand digital card experiences
- Cegid acquires Shine to build Europe’s AI-driven financial copilot for SMEs
- Robinhood scales prediction markets with 9B contracts and plans CFTC-regulated derivatives exchange
- Revolut plans Hong Kong expansion following London talks
- Ripple’s RLUSD wins regulatory approval in Abu Dhabi to expand institutional stablecoin use
- N26 launches personal loans and flexible overdrafts in Spain
- Raiffeisen Bank International AG joins EPI Company to enable Wero and expand A2A payments across Europe
- Klarna partners with Lufthansa group to bring flexible payments across Europe and the U.S.
- European Commission launches €5B scaleup Europe Fund to back late-stage deep-tech champions
- POM 🇳🇱 acquires FarPay to build pan-European invoicing and payments automation platform
Italian market
- -
And here some useful resources for everyone involved in the ecosystem:
Events you don’t want to miss
- Seamless Saudi Arabia | Riyadh - 17-19/11/2025 (link here)
- MoneyLIVE Payments | Amsterdam - 19-20/11/2025 (link here)
- 22nd Bank Management Conference | Athens - 20/11/2025 (link here)
You have a cool event you want to mention or to sponsor? Feel free to send me a DM.
Startups raising funds
- Loyyal - Loyalty platform from the MENA region, with entities in the US and South East Asia, provides a B2B2C platform to handle multiple loyalty programs and earn rewards all over the world. Raising a $6M Series A
- Freedhome - Proptech and fintech platform, enabling people to be able to gain profit from real estate by renting them to intermediaries. Raising a $1M seed round
- Weagle - B2B Tech startup that provides the very first browser designed for company, with total security for sensitive data. Raising $6 millions for their seed round.
- Shoppy Code:Gift card platform that offers a points based loyalty program. They share part of the profits coming from marketing budgets with their customers. Raising $500k.
Take also a look at the last edition of the newsletter, Weekly update #108.
Topics
Related funding
| Company | Round | Amount | Date |
|---|---|---|---|
| Square Yards Added · · Weekly update #109 | 35,000,000 USD | 28 November 2025 | |
| Model ML Added · · Weekly update #109 | Series A | 75,000,000 USD | 24 November 2025 |
| Parfin Added · · Weekly update #109 | 24 November 2025 | ||
| Wealthy Added · · Weekly update #109 | Series B | 1,300,000,000 INR | 24 November 2025 |
| STAMP Added · · Weekly update #109 | Pre-seed | 2,000,000 USD | 25 November 2025 |
| erad Added · · Weekly update #109 | Debt facility | 125,000,000 USD | 28 November 2025 |
| Numerai Added · · Weekly update #109 | Series C | 30,000,000 USD | 25 November 2025 |
| Omnisient Added · · Weekly update #109 | Series A | 12,500,000 USD | 25 November 2025 |
| Clara Added · · Weekly update #109 | Debt facility | 70,000,000 USD | 26 November 2025 |
| pay.com.au Added · · Weekly update #109 | 25,000,000 AUD | 24 November 2025 | |
| HelloTrade Added · · Weekly update #109 | Seed | 4,600,000 USD | 20 November 2025 |
| Opti Added · · Weekly update #109 | Seed | 20,000,000 USD | 28 November 2025 |
| BKN301 Added · · Weekly update #109 | Series B | 21,500,000 EUR | 14 April 2025 |
| Sencillo Added · · Weekly update #109 | Pre-seed | 350,000 GBP | 21 November 2025 |
| Higala Added · · Weekly update #109 | Seed | 4,000,000 USD | 26 November 2025 |