Weekly update #150
Tabby | تابي raises $233M at a $6.5B valuation as it expands beyond BNPL. barq closes a $329.5M Series A at $1.85B, two years after launch. S&P Global agrees to acquire OpenZeppelin , the security standard behind $37T in onchain value. Circle launches the Arc mainnet with BlackRock, DTCC, Masterc…
Tabby | تابي raises $233M at a $6.5B valuation as it expands beyond BNPL. barq closes a $329.5M Series A at $1.85B, two years after launch. S&P Global agrees to acquire OpenZeppelin , the security standard behind $37T in onchain value. Circle launches the Arc mainnet with BlackRock, DTCC, Mastercard and Visa. Global M&A hit $4.7T in 2025 — up 43% — with PE deal value rising 54% to $1.2T. Financial services M&A rose 40% to $499B; fintech deal value was up 108%.
Podcast
Builders #52 is out. This week my guest was Nicolas Kipp, CEO and founder of Credibur. Here a short clip from the video:
Listen on YouTube · Spotify · Apple Podcasts · Amazon
This week’s report: McKinsey 2026 M&A Trends
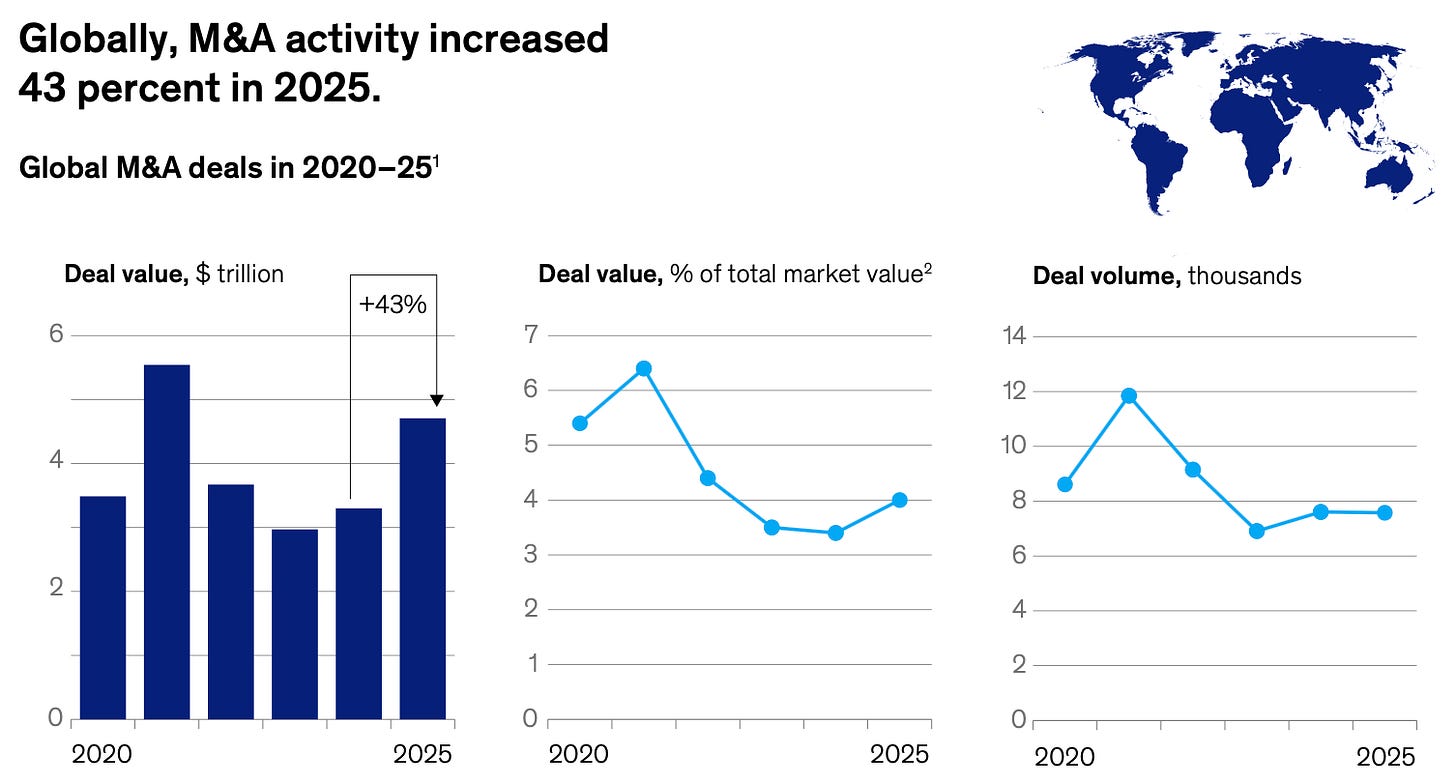
Global M&A deal value rose 43% to $4.7T in 2025, reaching 4.2% of total market value — up from 3.3% in 2024 and still below the 10-year average of 5.3%. Large deals ($10B+) numbered 60, the most since the post-COVID peak in 2021, with value more than doubling to $1.3T (+112%). PE deal value jumped 54% to $1.2T, with average deal size up to $890M.
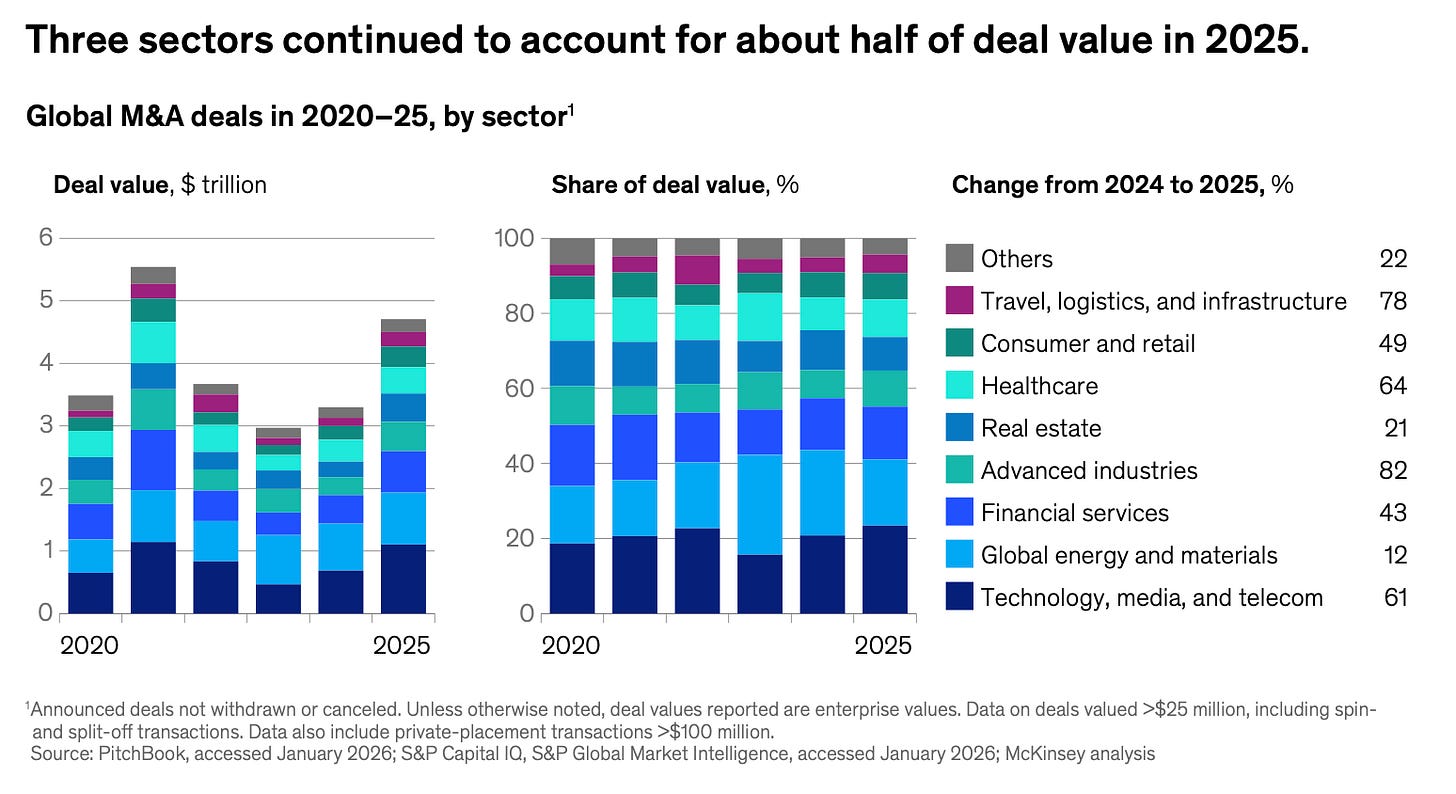
Divestitures grew 30% to $1.6T. Financial services M&A rose ~40% to $499B; fintech and payments deal value grew 108%, average deal size up 131% to $1.2B. The Americas accounted for 51% of financial services deal value ($255B). Banks are still trading at 0.9× book despite record net income of ~$1.2T in 2024 — a gap McKinsey expects to drive consolidation in 2026.
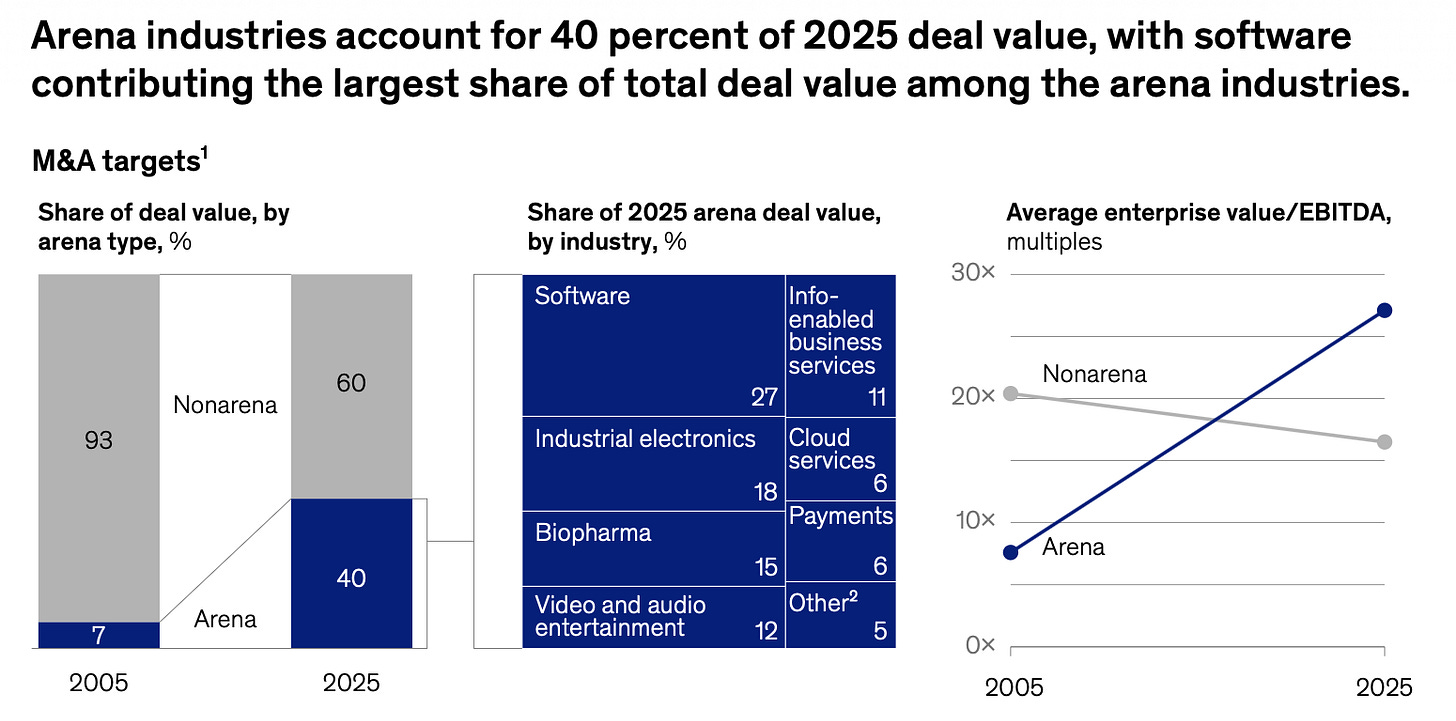
The read: the M&A market is back on volume and conviction. The fintech subsector’s 108% increase in deal value points squarely at two themes this week: scale plays in payments (Global Payments/Worldpay, FIS/Issuer) and capability acquisitions (Allica/Kriya, Banca Ifis/Illimity). The same logic is running through the rounds this week — barq and Tabby are building at scale, not at the margins.
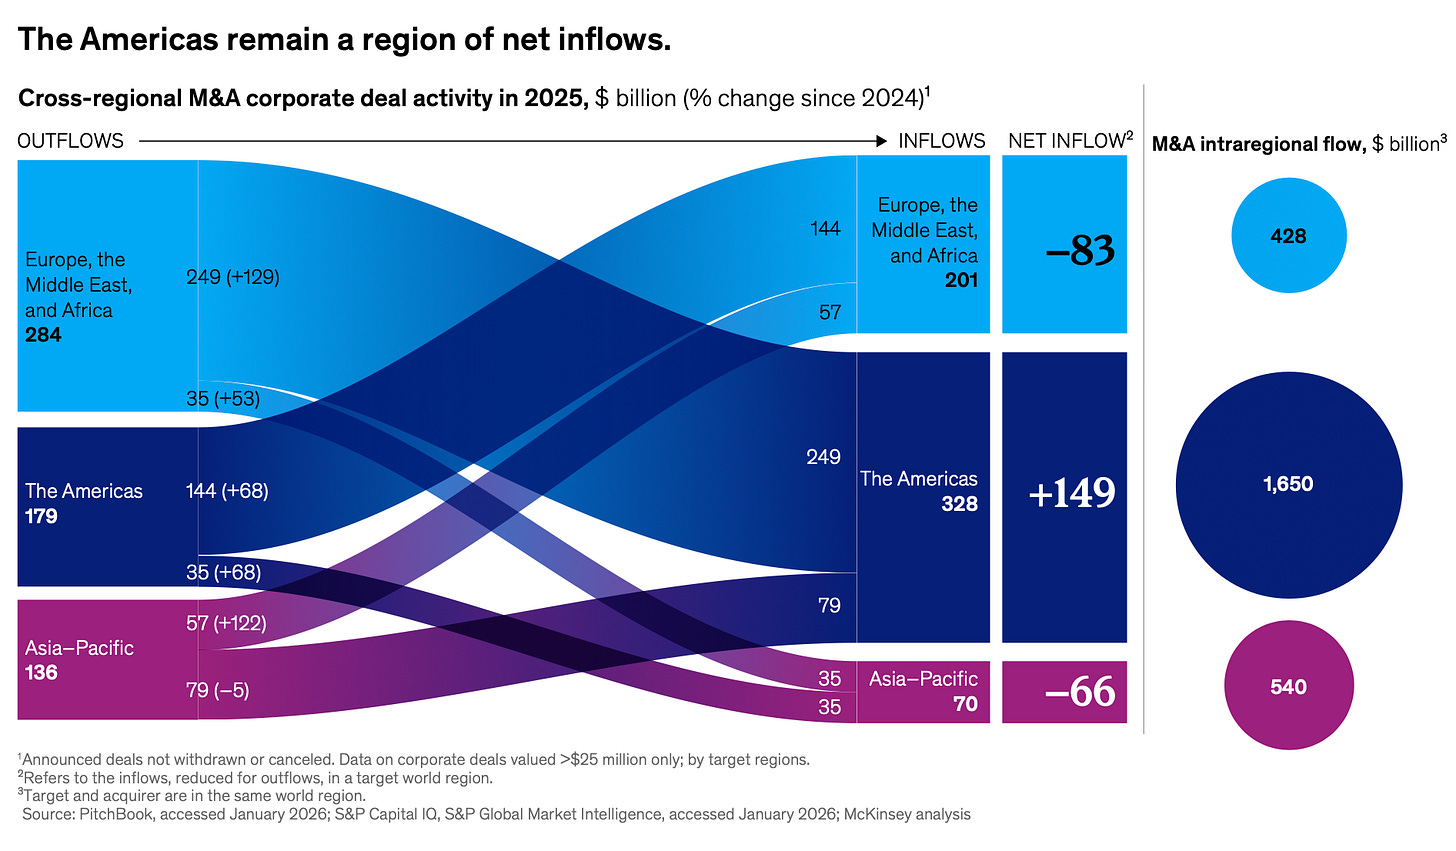
What McKinsey flags for 2026: cross-border deals in EMEA, more carve-outs as banks refocus on core, and AI as an accelerant of integration timelines. That last point is the one to watch — if AI genuinely compresses post-merger integration, deal cadence could keep rising even without valuation compression.
The week in six stories
1. [Tabby raises $233M at a $6.5B valuation as it moves beyond BNPL into a broader financial services platform](https://www.linkedin.com/posts/michele-mattei_tabby-share-7505282282417737728-5JSd/) — The Saudi-based BNPL leader is now valued at $6.5B after raising $233M. The round signals Tabby’s pivot from instalment payments into a full financial services platform across the Gulf.
2. [barq closes a $329.5M Series A at a $1.85B valuation, two years after launch](https://www.linkedin.com/posts/michele-mattei_barq-activity-7506268880554635265-r1zg) — The Saudi-founded payments network reached unicorn status just 24 months in, with the round among the largest Series A closes in MENA fintech.
3. [S&P Global agrees to acquire OpenZeppelin, the smart contract security standard behind $37T in onchain value](https://press.spglobal.com/2026-09-17-S-P-Global-Announces-Agreement-to-Acquire-OpenZeppelin) — Three days after leading Kaiko’s $110M round, S&P now owns both the market data and the security layer under tokenised finance.
4. [Circle launches the Arc mainnet in partnership with BlackRock, DTCC, ICE, Mastercard and Visa](https://www.linkedin.com/posts/michele-mattei_circle-arc-blackrock-share-7506275902863970304-k0jV/) — Arc is a Layer 1 payment blockchain built for instant settlement. The consortium of partners positions it as the institutional-grade stablecoin infrastructure rail.
5. [Qupital raises $300M in Series C and ABS financing led by M CAPITAL to expand e-commerce trade finance](https://www.linkedin.com/posts/michele-mattei_qupital-activity-7505656850076352512-CcgI) — The Hong Kong-based receivables financing platform combines a Series C equity round with an asset-backed securities vehicle to fund e-commerce seller working capital across Asia.
6. [Revolut prepares for a potential dual listing in London and New York, according to CEO Nik Storonsky](https://www.linkedin.com/posts/michele-mattei_fintech-fintech-activity-7506660873369714688-lP1r/) — A dual listing would give Revolut access to deeper capital markets and validate its post-IPO ambition following the UK banking licence approval earlier this year.
Also: Split Pay raises $125M across Series A and B led by Khosla Ventures · Ridgeline raises $250M Series E at $1.425B to build the AI-native investment management platform · Celligence secures up to $100M from Mortgage Treasury to scale its AngelAi mortgage platform · Velocity raises Series A to $48M with Visa, Circle and Ripple · Grab agrees to acquire 60% of Atome Financial for $1.49B · Ramp launches in the UK six months after acquiring Billhop · OpenAI launches ChatGPT for financial services, built with Morgan Stanley and Evercore.
All rounds
Equity
- $329.5M Series A — barq · Saudi digital payments network · $1.85B valuation · two years after launch
- $300M Series C + ABS — Qupital · Hong Kong e-commerce trade finance · led by M CAPITAL
- $233M — Tabby · Saudi BNPL and financial platform · $6.5B valuation
- $125M Series A + B — Split Pay · BNPE X w led by Khosla Ventures
- $110M Series B extension — Kaiko · crypto market data · strategic round led by S&P Global
- R$360M ($70M) Series D — A5X · Brazil derivatives exchange · R$2.7B valuation
- $48M Series A — Velocity · stablecoin · backed by Visa, Circle and Ripple
- $20M seed — Fin.com · stablecoin-to-local-currency infrastructure · led by Expa and Garrett Camp
- $15M Series A — Pave Finance · AI rtortfolio management for advisors · $100M pre-money valuation
- $13M Series A — Synapse Analytics · AI credit decisioning inside bank infrastructure · led by Partech
- $13M — ETFBOOK · ETF data intelligence layer
- $10.5M — Chift API · European financial connectivity layer
- $10M seed — Intermezzo · AI-native global payroll infrastructure
- $10M — Zeal · loyalty software on 4M+ payment terminals
- $3.5M seed — OCTA · AI agents for accounting firms · led by MEVP
- €18M Series A — Integra · account and tax reporting
- €2M seed — Opio · AI financial due diligence · Frst, Seedcamp, Global Founders Capital
- €3.7M — JustSolve · agentic AI for credit collection
- £2.75M — Quartz · AI wealth advisor
- €1.1M seed — Peaky · AI financial planning for finance teams · led by JK Invest
Debt and credit
- Up to $100M — Celligence (AngelAi) · AI mortgage platform · from Mortgage Treasury
- $50M strategic financing — Tarabut · open banking · from Saudi banks and family groups
- $50M corporate debt — Wayflyer · SME working capital · from Trinity Capital
- £2ؕ billion milestone — YouLend + Dojo · SME funding partnership
- £75M ($100M) facility — Ayan Capital · Shariah-compliant car finance · from Triple Point
VC funds
- $600M - Portage Ventures IV · fintech · fourth flagship fund
- $525M debut — Intrepid Growth Partners · AI — Fund I
- $484M across four vehicles — Crane Venture Partners · global tech · multi-stage
- $450M Eund II — Matter Venture Partners · HardTech · LPs include ASML, TSMC, Kleiner Perkins
- $1.6B Fund XI — Bain Capital Ventures · AI infrastructure, applications and services · early-stage
- $254M Fund IV — Artemis Capital Partners · Industrial Tech buyouts · aerospace, defence, life science, semis
- $130M Fund V — Seed Capital · Nordic startups · from Denmark across the Nordics
- $72M first close — Brighteye Ventures III · edtech, AI, productivity, labour tech · Fund III
- $77.6M Fund I — Cosmos Ventures
- $31M Fund II — Grindstone Ventures · Africa’s missing middle
- €40M target, first close — Primo Biotech Lazio · biotech and life sciences · Primo Capital, Lazio Innova cornerstone
- €40M first close — DAL Partners
- $1B allocation — BDC Defence Platform · $500M Defence Fund + $200M StrongNorth top-up · Canada
Market news
Stablecoins and crypto rails
- Circle launches the Arc mainnet with BlackRock, DTCC, ICE, Mastercard and Visa — payment Layer 1 for institutional settlement
- Column releases stablecoins, full-stack card issuing, global banking and multicurrency accounts — the chartered bank built by William Hockey opens its full product suite
- S&P Global agrees to acquire OpenZeppelin — the smart contract security standard behind $37T in onchain value; three days after S&P led Kaiko’s $110M round
AI in financial services
- OpenAI launches ChatGPT for financial services built with Morgan Stanley and Evercore — purpose-built AI for banking workflows
- Meta launches Muse, a personal AI agent that can shop and pay through Stripe’s Link
- Ramp launches in the UK, its first market outside North America, six months after acquiring Billhop for the licences
M&A and exits
- Grab signs definitive agreement to acquire 60% of Atome Financial for $1.49B — remaining 40% about two years later, valuation capped at $4.5B
Expansion and licensing
- Bybit secures an EMI licence in Austria to launch a European super app with bank accounts, stocks and crypto
- Revolut secures a Colombian banking licence ahead of a 2027 launch
- Revolut applies for a Swiss banking licence from FINMA and commits to invest CHF 150M over five years
- Revolut is preparing for a potential dual listing in London and New York
- Wise launches a Chequing Account in Canada with no monthly fee, free Interac e-Transfers and CDIC-eligible balances
- Monzo releases Aura, a new credit card
Security
Funds raising now
Space for GPs and solo GPs launching funds. Not paid. If you’re raising and want to be listed, message me on LinkedIn.
- Parallax Ventures — fintech, LatAm. Fund I: +50% IRR, 0.7x DPI. Raising Fund II. [link] · gennari@parallax.vc
- Founder Factor — YC-focused. Just closed investments in YC W26 and is expanding the current vehicle to double down on the batch. [link]
- RedFish Capital Partners — private equity, Italian SMEs in growth and mature phases. 40%+ IRR track record, €200M+ AUM. Raising a new AIF with a soft commitment from the European Investment Fund. redfish.capital · investor.relations@redfish.capital
Performance figures are provided by the managers. Nothing here is investment advice.
Events, next 30 days
- Money 20/20 Middle East | Riyadh | 14-16 September (link here)
- European blockchain week | Barcelona | 16-17 September (link here)
- Nordic fintech week | Copenhagen | 23-24 September (link here)
- Korea Blockchain Week 2026 | Seoul | September 29 - October 1 (link here)
Later: Money20/20 USA, Las Vegas (18–21 Oct) · MERGE Madrid (27–29 Oct) · Hong Kong Fintech Week (2–6 Nov) · Africa Stablecoin Summit, Johannesburg (12–13 Nov) · Solana Breakpoint, London (15–17 Nov) · Singapore FinTech Festival (18–20 Nov) · Fintech Nerdcon, San Diego (19–20 Nov) · Bitcoin MENA, Abu Dhabi (7–8 Dec) · Abu Dhabi Finance Week (7–10 Dec) · TOKEN2049 Dubai (21–22 Apr 2027) · Money20/20 Asia, Bangkok (27–29 Apr 2027)
Want an event listed or sponsored? DM me.