Weekly update #148
The latest news from the fintech and VC ecosystems
Revolut got conditional OCC approval for a US national bank charter, Mollie closed the GoCardless acquisition, and Anthropic launched AI commerce agents with Visa, Mastercard and Accenture. Below: McKinsey’s read on quantum computing and why financial services is the second-largest pool of value at stake, the week’s rounds and eleven new funds, and three managers raising now.
Builders in Fintech is back: season 5 opened on Tuesday with episode #51, where my guest was Gaston Irigoyen, CEO and founder of Pomelo. You can take a look at the full episode here on YouTube or here on Spotify, in the meanwhile take a look at a short clip:
All episodes: [YouTube] · [Spotify] · [Apple Podcasts] · [Amazon].
Founders and VCs who want to come on the show: message me on LinkedIn!
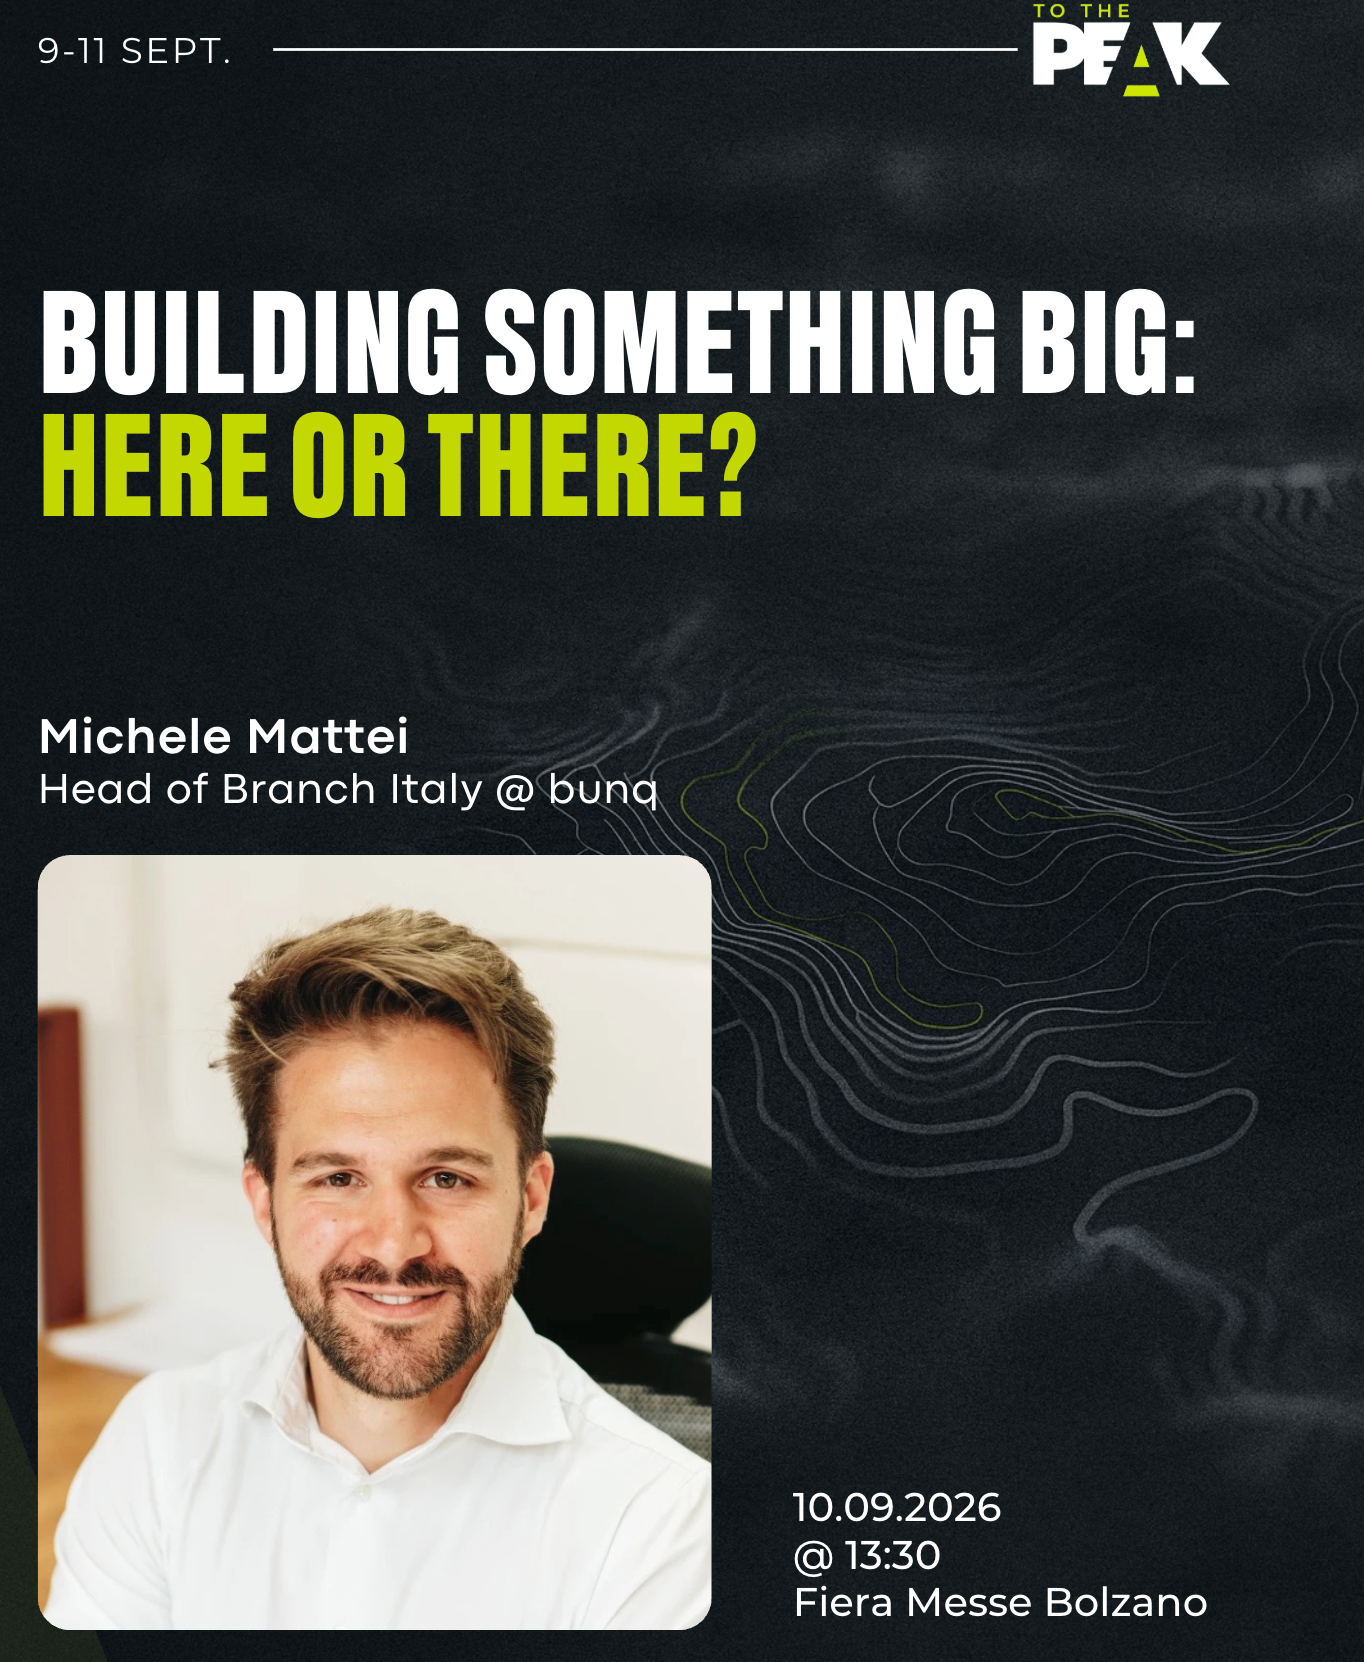
Also, I will be speaking at To the peak in Bolzano next week. I will share the stage with Claudio Erba and Alessandro Fracassi to talk about: “Building Something Big: Here or There?”, a very interesting discussion on why founders should or shouldn’t stay to build in Europe.
The report: quantum computing reaches the commercial phase
McKinsey, Quantum Technology Monitor 2026: A commercial tipping point (April 2026, fifth edition). Here my main takeaways:
The market. Quantum computing companies generated more than $1B in revenue in 2025, projected to reach up to $4.4B by 2028. The “internal” quantum market (hardware, software, services) is forecast at $60–100B by 2035, with computing accounting for $43–71B; McKinsey raised the lower bound from last year’s $28B after seeing corporate budgets shift. Over 300 organizations, including Airbus, Boehringer Ingelheim, E.ON, JPMorgan Chase and Liberty Mutual, are now working with quantum providers, moving from pilots to applications embedded in workflows.
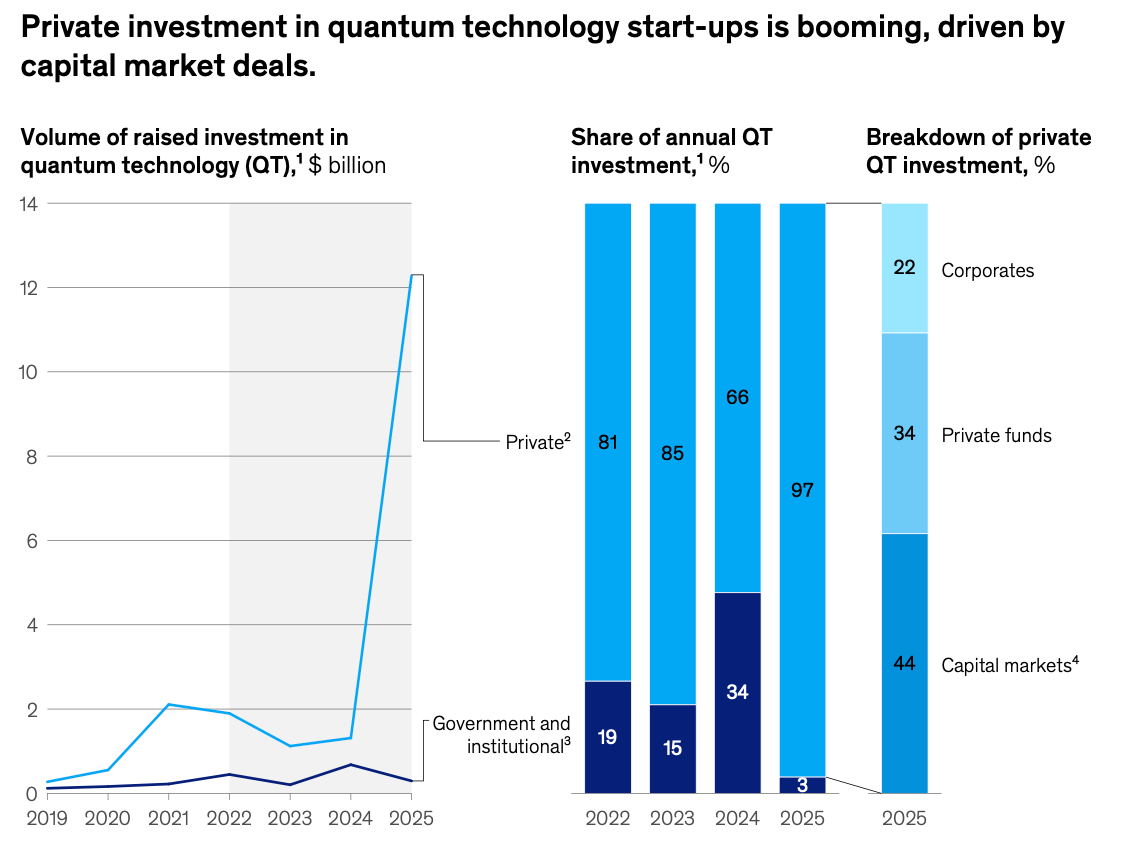
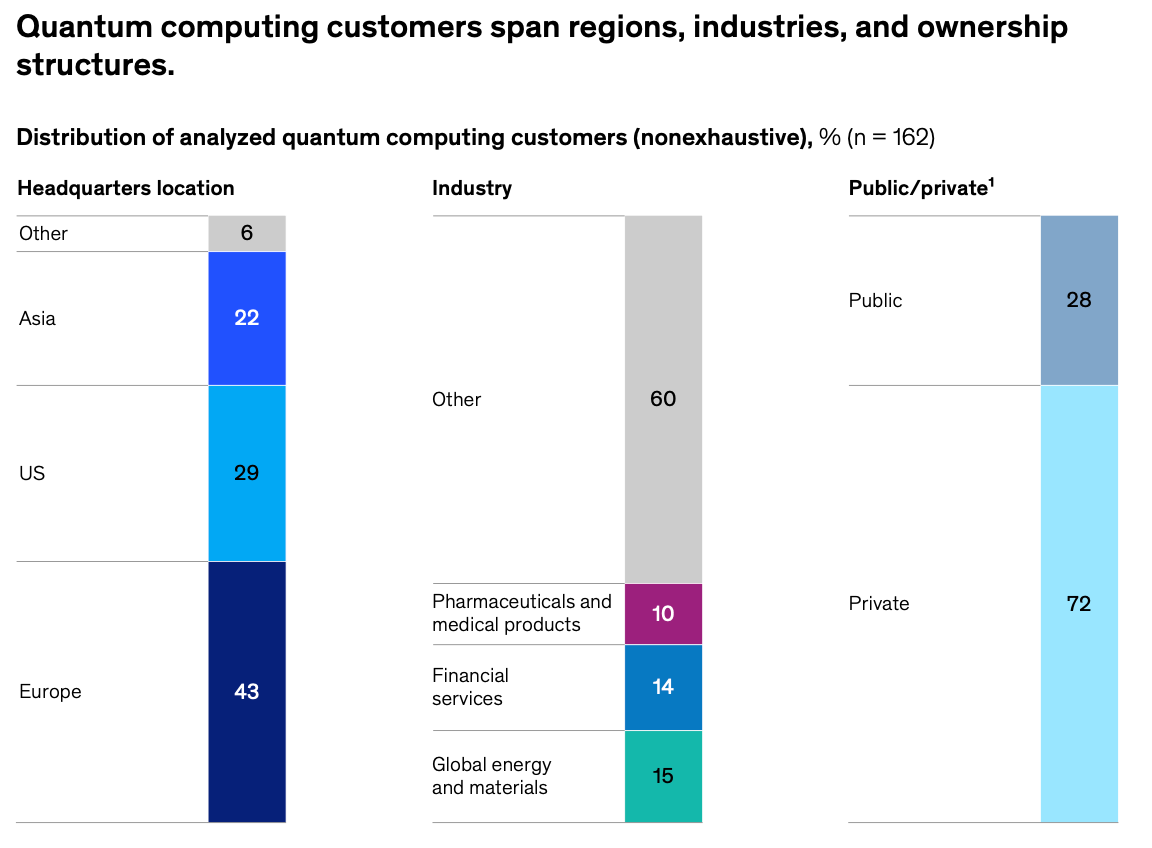
Where the value sits. Economic value at stake by 2035: $1.3–2.7T across industries. Chemicals leads at $450–800B; financial services is second at $400–600B, ahead of travel and logistics ($200–500B) and pharma ($80–400B). Of 162 customers analyzed, 14% are financial services firms, 43% are headquartered in Europe (US 29%, Asia 22%), and 72% are privately owned, a reversal from the public-lab-led market of a few years ago.
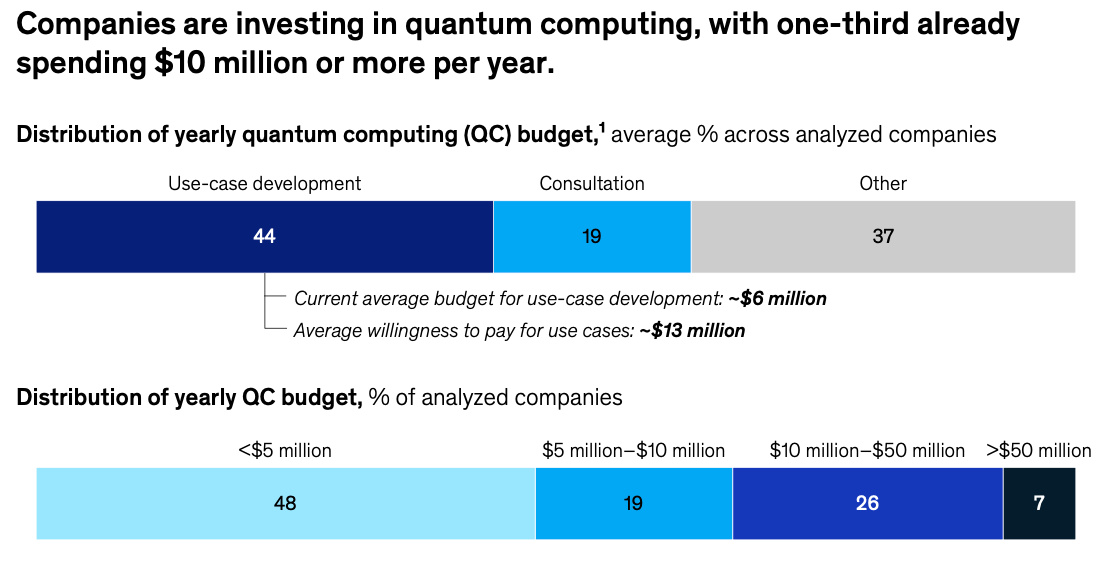
Corporate budgets. One-third of surveyed companies spent more than $10M on quantum in 2025; 7% spent over $50M. 44% of budgets go to use-case development (average ~$6M, with willingness to pay around $13M). Spending is going to applications, integration and internal teams, not hardware: private companies buy quantum-as-a-service via cloud, public entities buy on-premise.
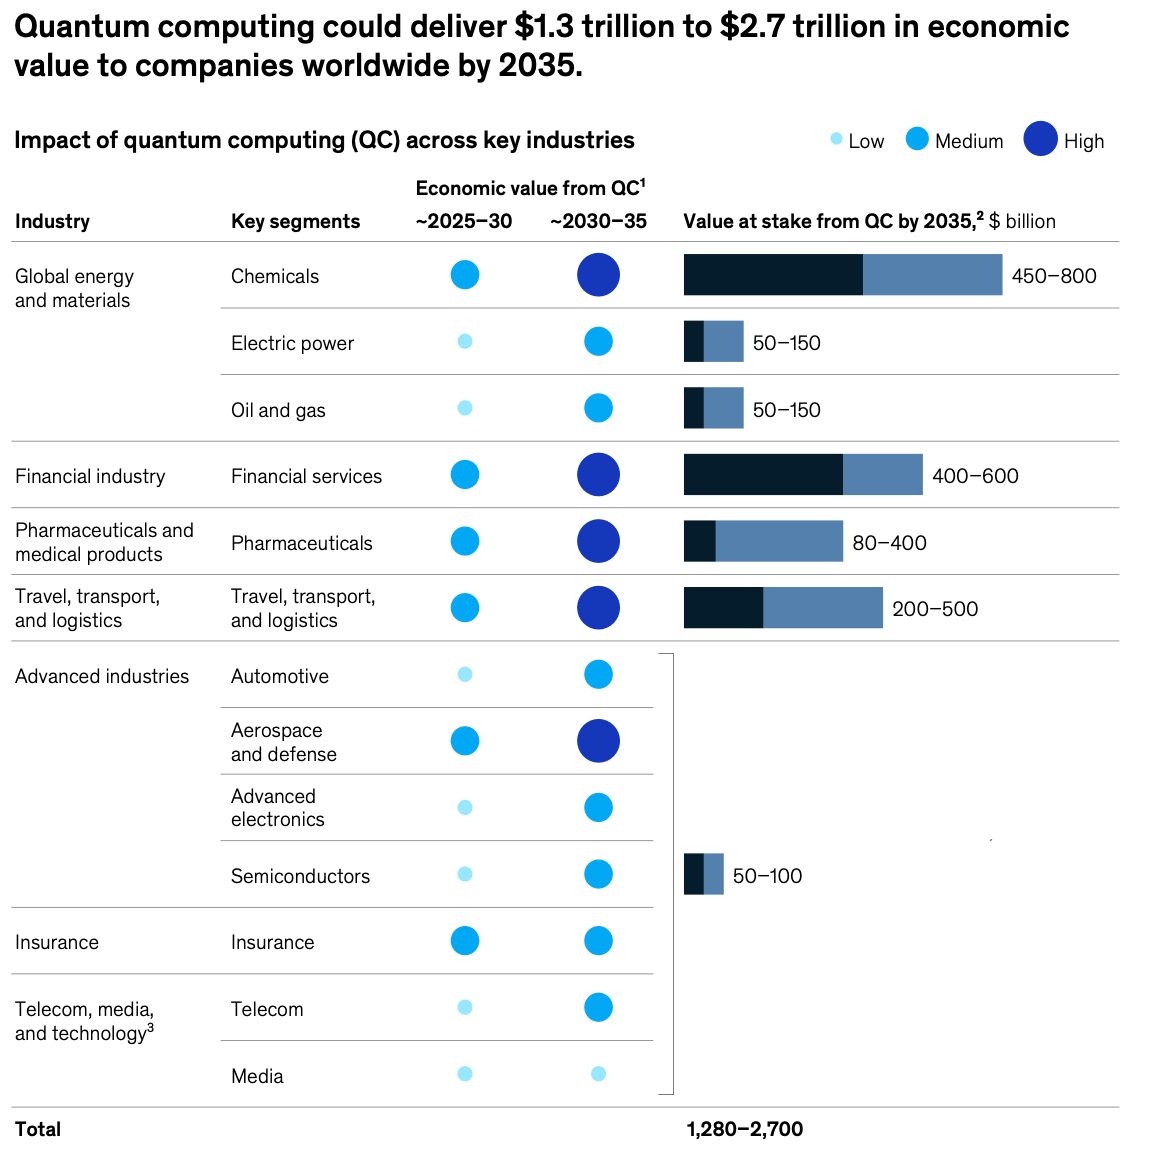
Capital. Investment in quantum start-ups hit $12.6B in 2025, 6.3x 2024. 90% went to computing. The source of capital flipped: public money (governments, sovereign funds, universities) was one-third of the total in 2024 and 3% in 2025. Of private capital, 44% came from capital markets (IPOs, SPACs, PIPEs), 34% from funds, 22% from corporates. Roughly 60% of the year’s total went into the top ten deals. Exits arrived: IonQ’s $1.1B acquisition of Oxford Ionics, Xanadu’s SPAC listing, and IonQ’s further purchases of Qubitekk, Lightsynq, Capella Space, Vector Atomic and a majority of ID Quantique, with SkyWater Technology expected to close in 2026.
What’s still hard. Bottlenecks have moved from qubits to lasers, cryogenics, control electronics and manufacturing. Provider roadmaps range from hundreds to hundreds of thousands of logical qubits within a few years; fault-tolerance timelines remain uncertain. The credible near-term path is hybrid: classical HPC does most of the work, AI orchestrates, quantum handles the hardest sub-problems.
The read. Finance is the second-largest value pool in the report and the one with the clearest forcing function: Q-Day, when public-key cryptography breaks, is a compliance deadline that every bank and payments network will have to budget for, regardless of whether quantum optimization ever pays off. JPMorgan already has an internal team on portfolio optimization, AI and cryptography, and the report’s use cases in finance (risk scenarios, edge-case correlations) look like today’s model-risk stack with a new back end. Two things to watch. First, the 2025 capital number is mostly public-market money going into a handful of listed names; with only 3% public funding and 60% concentrated in ten deals, valuations are pricing in roadmaps that the report itself calls uncertain. Second, “quantum-as-a-service” via AWS and Azure means the buy-side for fintech is going to look like cloud procurement, not R&D partnerships, and the winners will be the software layer (Classiq, Zapata) that makes it usable, not the hardware. For post-quantum cryptography specifically, the vendors selling migration tooling to banks are the fintech angle nobody is pricing yet.
The week in six stories
- Revolut wins conditional OCC approval for a US national bank charter. The application was filed in March; FDIC, Federal Reserve and final OCC sign-off are still required. The bank will be based in Stamford, Connecticut, with ~$95M of initial capital and a 2027 launch target.
- Mollie completes the GoCardless acquisition, creating a broader European payments platform spanning card acceptance and bank-to-bank collections.
- EQT completes its $3.2B combination with Coller Capital, taking a private-markets secondaries specialist inside one of Europe’s largest alternative managers.
- Anthropic launches AI commerce agents with Visa, Mastercard and Accenture. The card networks are now partners of the model providers on agentic checkout, a week after Experian brought credit-card shopping into ChatGPT.
- Félix secures a $200M Series C to build an AI-powered financial platform for Latinos in the US.
- TabaPay raises $155M and moves to acquire Transact Bank, the payments processor’s route to owning a bank charter.
Also: Wonderful raises $550M at a $5B valuation for enterprise AI agents; London Stock Exchange and Kraken parent Payward bring FTSE 100 stocks onchain; X moves US creator payouts from Stripe to X Money; Polymarket reportedly in talks for $300M from 1789 Capital as part of a $1B round; PayPal cuts nearly 25% of its Israel workforce and 600 jobs in India under a plan to remove ~20% of global headcount.
Funds. Eleven new vehicles this week. Andreessen Horowitz launched a $1.1B Machine Age fund for AI infrastructure and expanded its growth fund to $8.5B; Swish Ventures (Omri Casspi) launched a $250M fund, taking AUM to $800M; Permanent Capital Ventures closed a second $200M fund; Uplift Ventures launched a €100M deep-tech fund; Cherubic Ventures closed a $68.88M Fund VI as a solo GP; Auxxo Female Catalyst Fund closed €33.3M Fund II; British Business Bank committed up to £46M to Zinc’s new deep-tech fund; Redstone launched a €10M deep-tech fund in Finland; GMO VenturePartners announced Fintech Fund 8, ¥6.4B at first close with a ¥10B target, focused on AI × fintech [verify: the Sept 2026 announcement — first close vs launch]; Mykhailo Fedorov plans a Ukrainian defence-tech fund.
All rounds
Equity
- Wonderful raises $550M at $5B valuation to scale enterprise AI agents
- Félix secures $200M series C to build an AI powered financial platform for latinos
- TabaPay raises $155M and moves to acquire Transact Bank
- Firelight Protocol raises $8M to bring staked XRP protection to DeFi
- MFast raises $6M to expand its agent led fintech model into the Philippines
- Plenti raises $3M seed round led by Tether.io to expand across Latin America
- Instarc Technologies raises €1.25M to scale cloud compliance platform in South Africa
Debt and credit
Reported / in progress
- Polymarket reportedly in talks to raise $300M from 1789 Capital in $1B funding round
- Bolt seeks up to $27M in bridge funding as Ryan Breslow leads turnaround
VC funds
- Andreessen Horowitz expands growth fund to $8.5B as AI investment accelerates
- Andreessen Horowitz launches $1.1 billion Machine Age fund for AI infrastructure
- Omri Casspi’s Swish Ventures launches $250M fund, reaching $800M in AUM
- Uplift Ventures launches €100 million deep tech fund
- British Business Bank commits up to £46M to Zinc’s new deeptech fund
- Auxxo Female Catalyst Fund closes €33.3M fund II to back female founders across Europe
- Redstone launches €10 million DeepTech fund in Finland
- Mykhailo Fedorov plans new Ukrainian defence tech fund
Market news
Regulation and licensing
- Revolut wins conditional OCC approval for a US national bank charter
- Fiat Republic and ClearBank partner on MiCA safeguarding
- Monetary Authority of Singapore commits S$220M to accelerate fintech innovation
Stablecoins and digital assets
- London Stock Exchange and Kraken parent Payward bring FTSE 100 stocks onchain
- BitGo acquires NYDIG’s institutional trading business
- Nium launches USDC funding for global fiat payouts
- Alpaca partners with Kalshi to bring prediction markets to its brokerage infrastructure
AI
- Anthropic launches AI commerce agents with Visa, Mastercard and Accenture
- Revolut launches AIR, its AI financial assistant, across Europe
- Experian brings credit card shopping to ChatGPT
- Accrual to acquire Puzzle and expand AI platform into client accounting
- Airwallex backs 10 Australian AI startups with $1M in equity free funding
M&A
- Mollie completes GoCardless acquisition, creating a broader European payments platform
- EQT Group completes $3.2B combination with Coller Capital
- TabaPay raises $155M and moves to acquire Transact Bank
- fomo acquires Mobula’s technology and team in $17M deal
Payments and partnerships
- EPI Company launches Wero in Luxembourg as Payconiq migration enters final phase
- Orange becomes first french merchant to offer Wero for subscription payments
- Revolut and Yuno partner to expand global merchant payments
- X moves US creator payouts from Stripe to X Money
- Ingenico expands leadership team following €150M investment
- Contents welcomes Deel Ventures as strategic investor
- Allica Bank targets Sweden for first international expansion
Sports partnerships
- Circle‘s USDC becomes Chelsea Football Club front of shirt sponsor
- etoro becomes official trading partner of Leeds United
- Finom becomes Juventus Football Club’ official B2B financial platform partner
Restructuring
- PayPal cuts up to 25% of Israel workforce as global restructuring accelerates
Startups to watch
Companies I’ve been talking with this week that I find interesting
- [BigData.com](https://app.bigdata.com/)— Data analysis, embedded directly in your AI tool
- [Syeew](https://www.syeew.it/) — AI powerd ERP for multi point of sales chains
- [BeBelong](https://bebelong.life/capital) — Solving the housing problem in the US with advertising
Let me know if you want to have a chat with them, always happy to make an intro.
Raising now
Space for GPs and solo GPs launching funds. Not paid. If you’re raising and want to be listed, message me on LinkedIn.
- Parallax Ventures — fintech, LatAm. Fund I: +50% IRR, 0.7x DPI. Raising Fund II. [link] · gennari@parallax.vc
- Founder Factor — YC-focused. Closed investments in YC W26 and is expanding the current vehicle to double down on the batch. [link]
- RedFish Capital Partners — private equity, Italian SMEs in growth and mature phases. 40%+ IRR track record, €200M+ AUM. Raising a new AIF with a soft commitment from the European Investment Fund. [link] · investor.relations@redfish.capital
Performance figures are provided by the managers. Nothing here is investment advice.
Events, next 30 days
- Global Fintech Fest 2026 | Mumbai | 9-11 September (link here)
- Money 20/20 Middle East | Riyadh | 14-16 September (link here)
- European blockchain week | Barcelona | 16-17 September (link here)
- Nordic fintech week | Copenhagen | 23-24 September (link here)
- Korea Blockchain Week 2026 | Seoul | September 29 - October 1 (link here)
Later: TOKEN2049 Singapore (7–8 Oct) · Money20/20 USA, Las Vegas (18–21 Oct) · MERGE Madrid (27–29 Oct) · Hong Kong Fintech Week (2–6 Nov) · Africa Stablecoin Summit, Johannesburg (12–13 Nov) · Solana Breakpoint, London (15–17 Nov) · Singapore FinTech Festival (18–20 Nov) · Fintech Nerdcon, San Diego (19–20 Nov) · Bitcoin MENA, Abu Dhabi (7–8 Dec) · Abu Dhabi Finance Week (7–10 Dec) · TOKEN2049 Dubai (21–22 Apr 2027) · Money20/20 Asia, Bangkok (27–29 Apr 2027)
Want an event listed? DM me.
Previous edition: [Weekly update #147]
Topics
Related funding
| Company | Round | Amount | Date |
|---|---|---|---|
| Plenti (Latin America) Added · · Weekly update #148 | Seed | 3,000,000 USD | 3 September 2026 |
| ID Finance Added · · Weekly update #148 | Debt facility | 21,000,000 EUR | 4 September 2026 |
| Wonderful Added · · Weekly update #148 | 550,000,000 USD | 2 September 2026 | |
| Instarc Technologies Added · · Weekly update #148 | Strategic | 1,250,000 EUR | 1 September 2026 |
| TabaPay Added · · Weekly update #148 | Growth | 155,000,000 USD | 2 September 2026 |
| Félix Added · · Weekly update #148 | Series C | 87,000,000 USD | 1 September 2026 |
| Firelight Protocol Added · · Weekly update #148 | Seed | 8,000,000 USD | 31 August 2026 |
| MFast Added · · Weekly update #148 | Series A | 6,000,000 USD | 29 August 2023 |