Weekly update #147
The latest news from the fintech and VC ecosystems
Welcome to this edition of the weekly newsletter. The idea behind this is to gather all the information in the startup ecosystem in one place, with a special focus on the fintech market and the VC industry.
Builders will be back tomorrow with season 5 first episode! Keep an eye open on linkedin for the announce. But you can always recover all episodes here:
If you are interested in joining me on the podcast, feel free to drop a message on Linkedin! I am always looking forward to speak with the best founders and VCs in the market!
Coming back to us, this week I’ve been reading a very interesting report from McKinsey & Company on stablecoins, the “Cross-borders payments: Out of the commodity trap and into the future”. The global cross-border payments industry has run on a single, successful playbook for many years: Reduce the friction, cost, and time needed to move money from point A to point B. Yet this stability hides the underlying shifts that are set to reshape the cross-border payments industry in the years to come. Here my main takeaways:
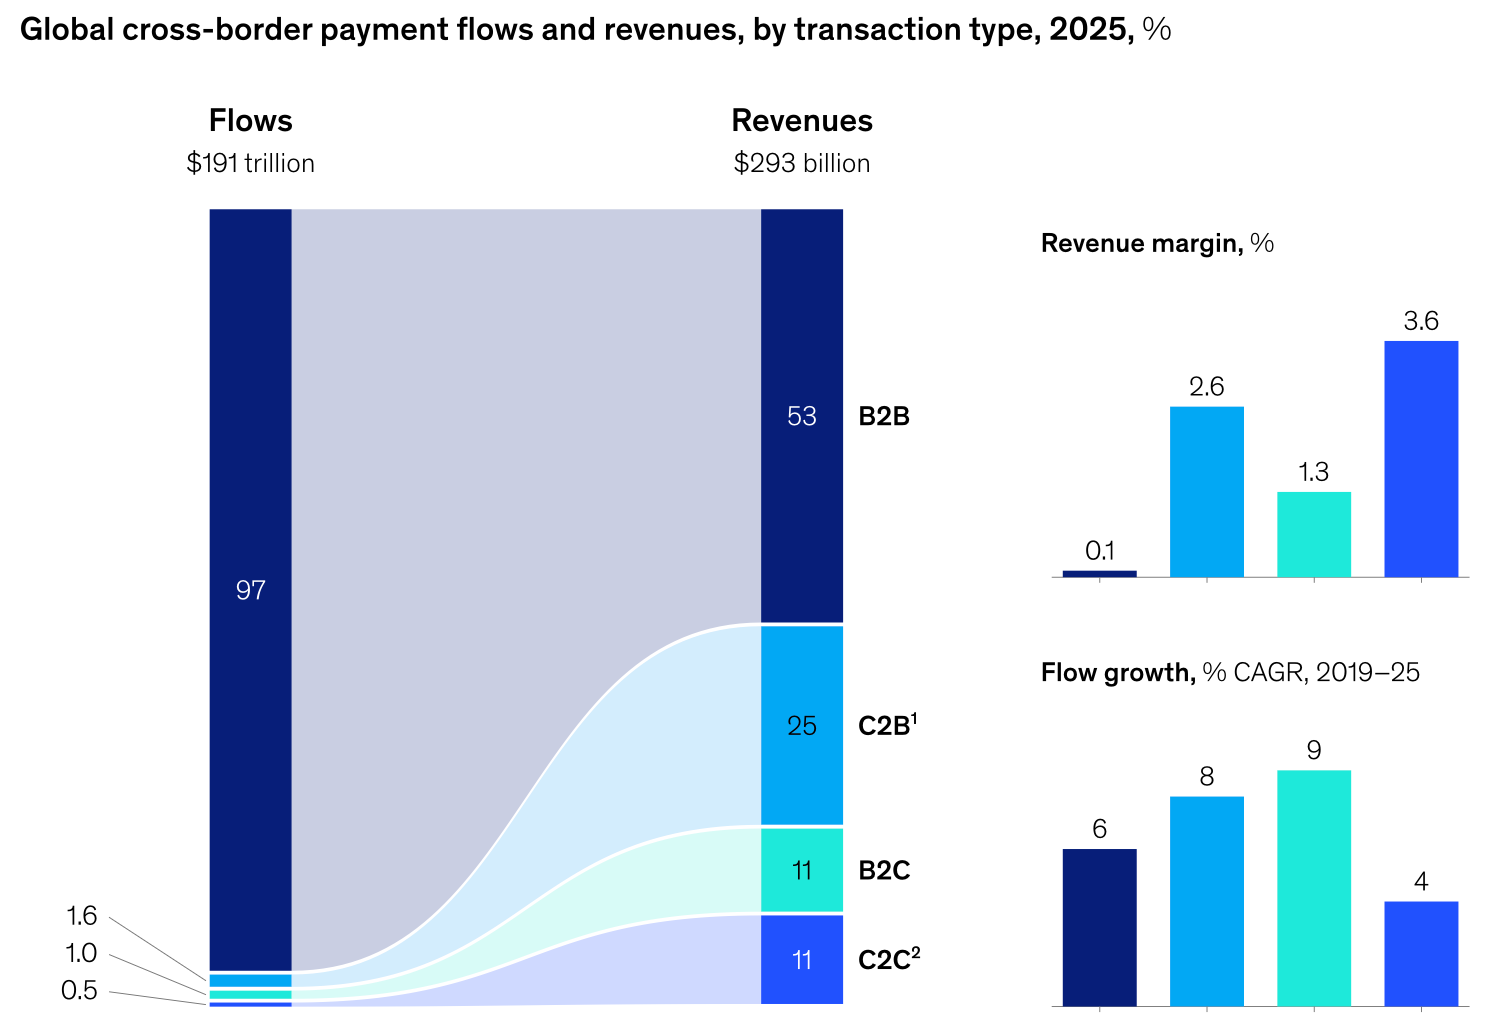
McKinsey estimates cross border payment volumes at $190 trillion, generating more than $290 billion in global revenues, with revenues expected to grow about 4 percent annually.
However, the industry is entering a structural shift. Security, speed, and cost, once key competitive advantages, are increasingly becoming standard capabilities as payment rails modernize, licensed global providers expand, and new settlement networks emerge.
Payments are also becoming embedded within accounting, procurement, and treasury workflows. As a result, moving money alone may no longer be a sustainable standalone product, forcing banks and fintech specialists to compete through broader financial and operational solutions.
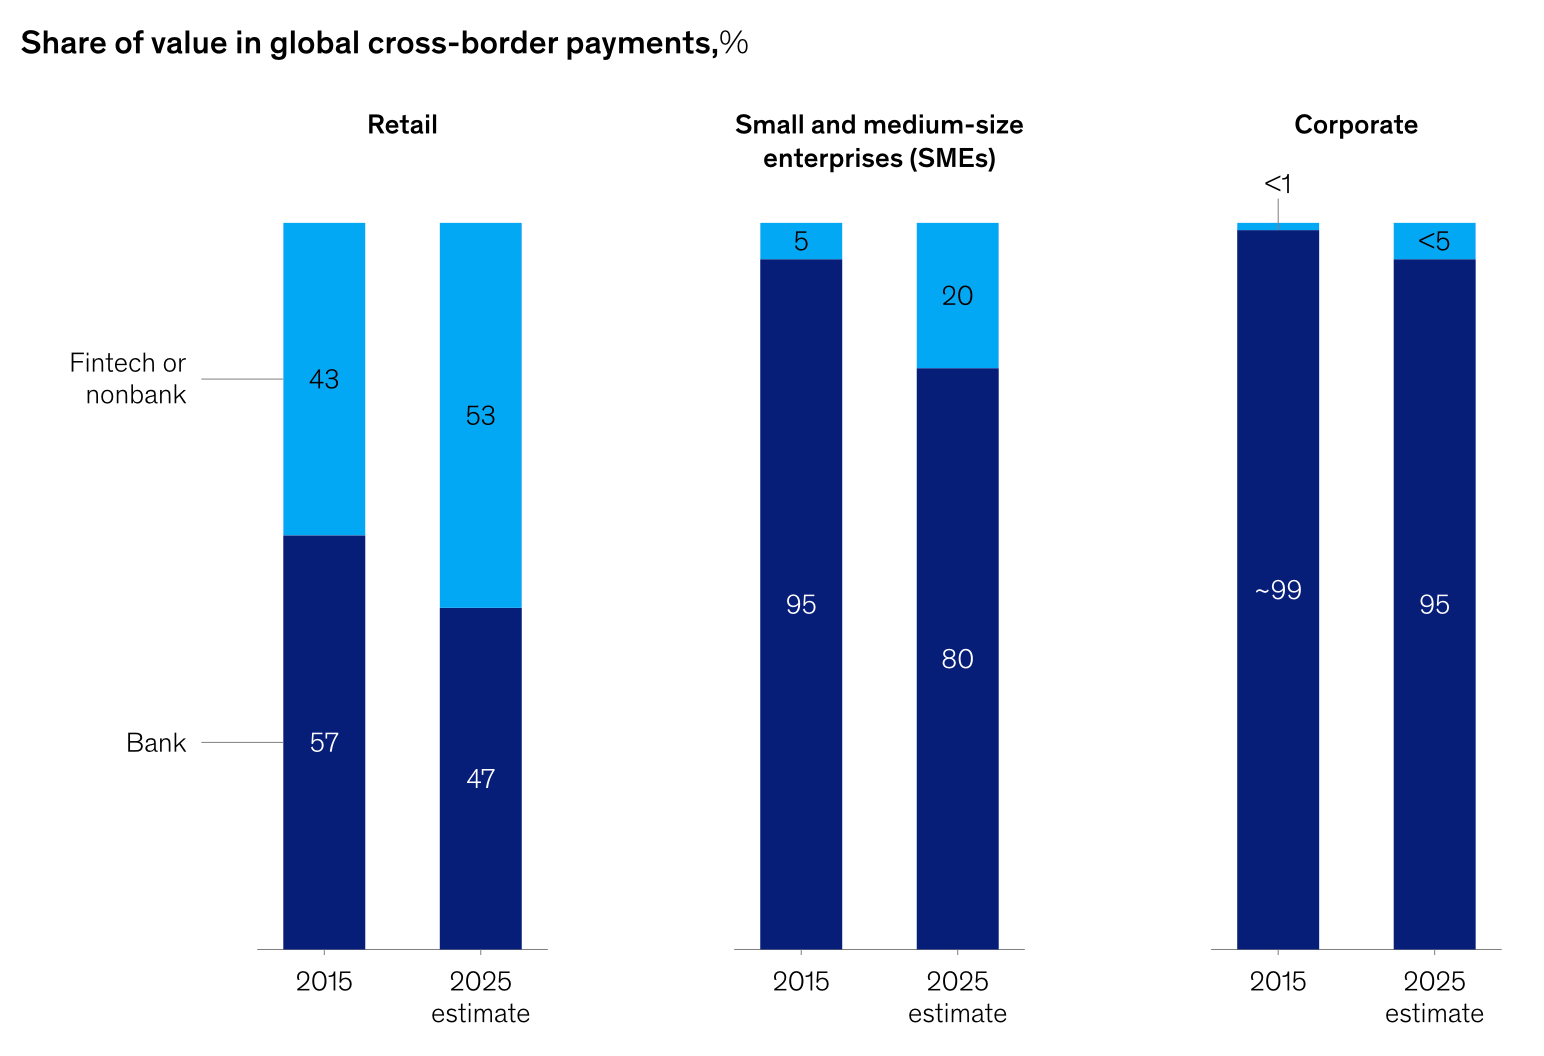
Cost and speed remain central competitive factors in cross border payments, with fintech specialists driving lower prices, faster transactions, and greater margin transparency. Over the past decade, they have captured about 50 percent of consumer payments and remittances and roughly 20 percent of small business and SME flows.
Pricing pressure is accelerating. World Bank data shows the average cost of sending a $200 remittance declined from 6.8 percent in 2019 to 6.3 percent in 2025. Digital only channels now average below 5 percent, while the most competitive corridors already meet or fall below the UN’s 3 percent target.
The G20 is pushing further, targeting total retail payment costs below 1 percent, including fees and FX spreads. This shift is most advanced across high volume G7 corridors, while lower volume and more complex routes still command higher margins.
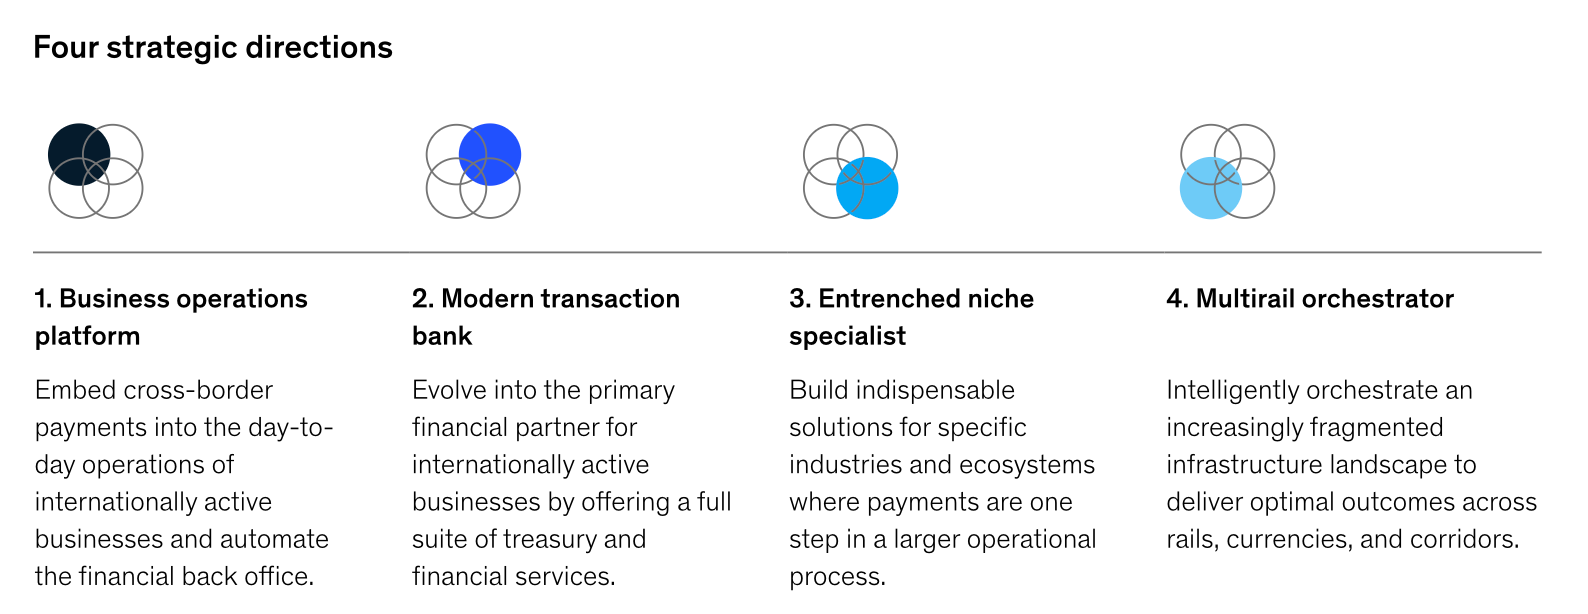
Four strategic models are emerging. Providers can become business operations platforms by embedding payments into invoicing, ERP, expense management, reconciliation, and AI enabled workflows, as seen with Airwallex and Tipalti. They can evolve into modern transaction banks offering liquidity, FX, lending, and treasury services, following examples such as Ebury.
Others may specialize deeply in complex verticals, as Flywire has done in international education, or become multirail orchestrators that optimize transactions across banking networks, instant payments, cards, stablecoins, and tokenized deposits. Thunes and Nium illustrate this infrastructure focused model.
Pricing pressure in cross border payments is intensifying as fintechs such as Wise, Revolut , and Airwallex compete on lower fees, tighter FX spreads, and transparency. Banks are responding: KBC offers commission free FX up to €1,500 per month, while Bank of America and HSBC have removed certain international transfer fees.
Speed is also becoming standard as Banking Circle, Wise, Buna, Project Nexus, Swift, stablecoins, and tokenized deposits push payments toward instant settlement. Open USD already involves more than 140 members.
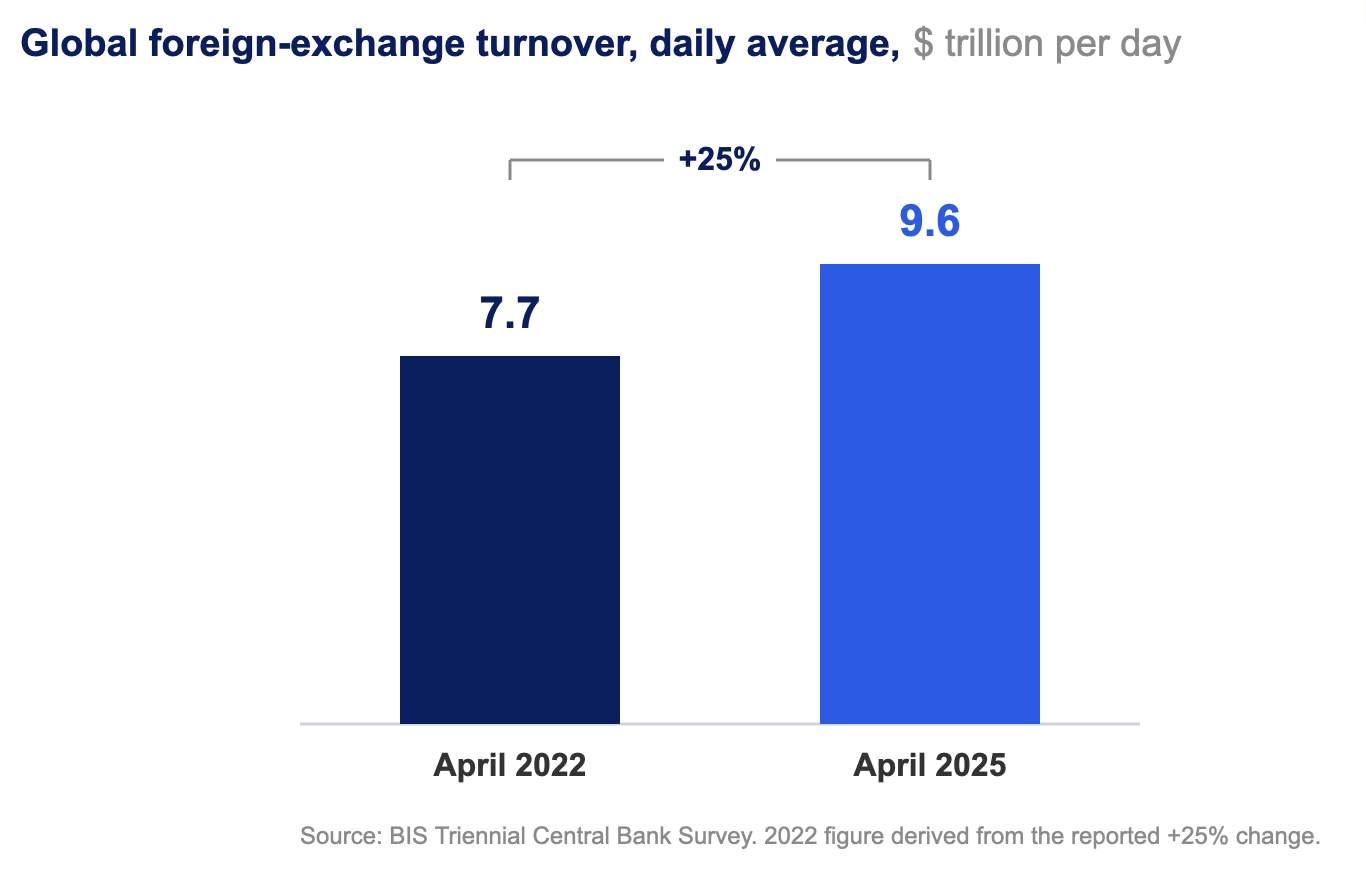
Value is therefore shifting toward advisory and workflow services. FX turnover reached $9.6 trillion per day in April 2025, 25 percent above 2022. US China trade fell about 12 percent in 2025, Vietnam exports grew 17 percent, and India redirected an additional $15 billion in smartphone exports to the US.
But let’s take a closer look at the main news of the last seven days, Revolut launched EURR, its proprietary stablecoin, NVIDIA acquired Hugging Face for $12.9 billion, Stripe and Advent deal to acquire PayPal officially collapsed and SumUp became Newcastle United Football Club official training kit sponsor. But also, Airwallex commits $43M to UAE expansion, Revolut launches AI research division to work on PRAGMA, Kraken parent company Payward explores full US banking license and Vanguard acquires Altruist. In the VC ecosystem, lots of new funds this week. RunwayVC closed a $40M fund II, Fiat Ventures became FGV Capital and raised $35M for fund II, Capital F debuted with a $17M first fund, but also OpenAI, Einride, SaaSholic . And finally, some very interesting funding rounds from fintech startups like Fasset, Natural, Helcim, Repodo (congrats Ken Villum Klausen!), Socure, neno and many others.
Let’s take a closer look:
Rounds
- Fasset raises $68M series C at $1B valuation
- Natural secures $100M credit facility to scale agentic payments
- Helcim raises $53M Series C at $250M valuation
- Pago ASAP raises $1.15M to expand in Colombia
- Lunar founder Ken Villum Klausen launches AI native audit firm Repodo with €8.2M round
- neno raises €6.6M to expand AI native financial services across Europe
- AppsFlyer secures $400M credit line from Bank Leumi בנק לאומי
- Nexedge Capital raises $20M to scale wealth management platform
- ItoFlow raises $2.5M for AI investment research agents
- Standard Metrics raises $20M series B for AI portfolio management
- Imprint secures $2 billion in new debt funding
- Payload raises $9 million Series A led by Fifth Third Bank
- Fina partner raises $1 million seed round to expand SME fintech platform
- Hivemind Capital raises $17 million to scale tokenization infrastructure
- Socure reaches $5.2B valuation and acquires Fravity AI
- RQD\* Clearing raises $74 million to expand clearing infrastructure
- Ajaib raises $270 million series C to expand its investment platform across Indonesia
VC funds
- RunwayVC reaches €40M first close for fund II
- Fiat Ventures rebrands as FGV Capital and raises $35M fund II
- Einride founders launch Navisalma to invest €450M in European deep tech startups
- OpenAI prepares $400M second VC fund
- Capital F closes $17M debut fund with 80% female LPs
- SaaSholic closes $30 million fund III to back Latin American software
News on the market
- Airwallex plans to expand into autonomous finance after the $320M round
- SumUp becomes Newcastle United Football Club’s official training kit partner
- Nubank will spend around $475 million in office expansion across Brazil
- Kraken parent Payward explores full banking license outside the US
- Miracle Pay partners with zerohash to bring stablecoin payments to US merchants
- Revolut launches AI research division to power PRAGMA in collaboration with NVIDIA
- Guzco partners with Mollie to automate chargeback resolution
- Airwallex commits $43M to UAE expansion
- Zand expands stablecoin infrastructure with USDC
- Revolut launches EURR, its first Euro stablecoin
- Scalable Capital opens investing platform to AI Agents
- payabl. expands Visa partnership to automate dispute resolution
- Plum expands Upvest partnership to power UK investments
- NVIDIA agrees to $12.9B acquisition of Hugging Face
- Vanguard to acquire AI wealthtech platform Altruist
- DBS Bank and Stripe partner on AI powered commerce and cross border payments in Asia
- Deutsche Bank Private Bank selects Thought Machine for core banking transformation
- zerohash resubmits OCC national trust bank charter application
- Ant International backed R2 expands into Brazil
- Stripe and Advent end $53 billion pursuit of PayPal
- UK gives Bank of England new mandate to support stablecoin innovation
And here some useful resources for everyone involved in the ecosystem:
Events you don’t want to miss
- Global Fintech Fest 2026 | Mumbai | 9-11 September (link here)
- Money 20/20 Middle East | Riyadh | 14-16 September (link here)
- European blockchain week | Barcelona | 16-17 September (link here)
- Nordic fintech week | Copenhagen | 23-24 September (link here)
- Korea Blockchain Week 2026 | Seoul | September 29 - October 1 (link here)
- TOKEN2049 | Singapore | 7-8 October (link here)
- Money 20/20 USA | Las Vegas | 18-21 October (link here)
- MERGE Madrid 2026 | Madrid | October 27-29 (link here)
- Hong Kong fintech week | Hong Kong | 02-06 November (link here)
- Africa Stablecoin Summit 2026 | Johannesburg | 12-13 November (link here)
- Solana Breakpoint 2026 | London | 15-17 November (link here)
- Singapore FinTech Festival 2026 | Singapore | 18-20 November (link here)
- Fintech Nerdcon | San Diego | 19-20 November (link here)
- Bitcoin MENA 2026 | Abu Dhabi | 7-8 December (link here)
- Abu Dhabi Finance Week 2026 | Abu Dhabi | 7-10 December (link here)
- TOKEN2049 Dubai 2027 | Dubai | 21-22 April, 2027 (link here)
- Money20/20 Asia 2027 | Bangkok | 27-29 April, 2027 (link here)
You have a cool event you want to mention or to sponsor? Feel free to send me a DM.
Founders to watch in fintech
I also wanted to start shining a light on the most interesting fintech founders out there, so I thought to start sharing how I look for ideas to invest on. Every week, I will start sharing the most interesting founders in fintech, divided per area.
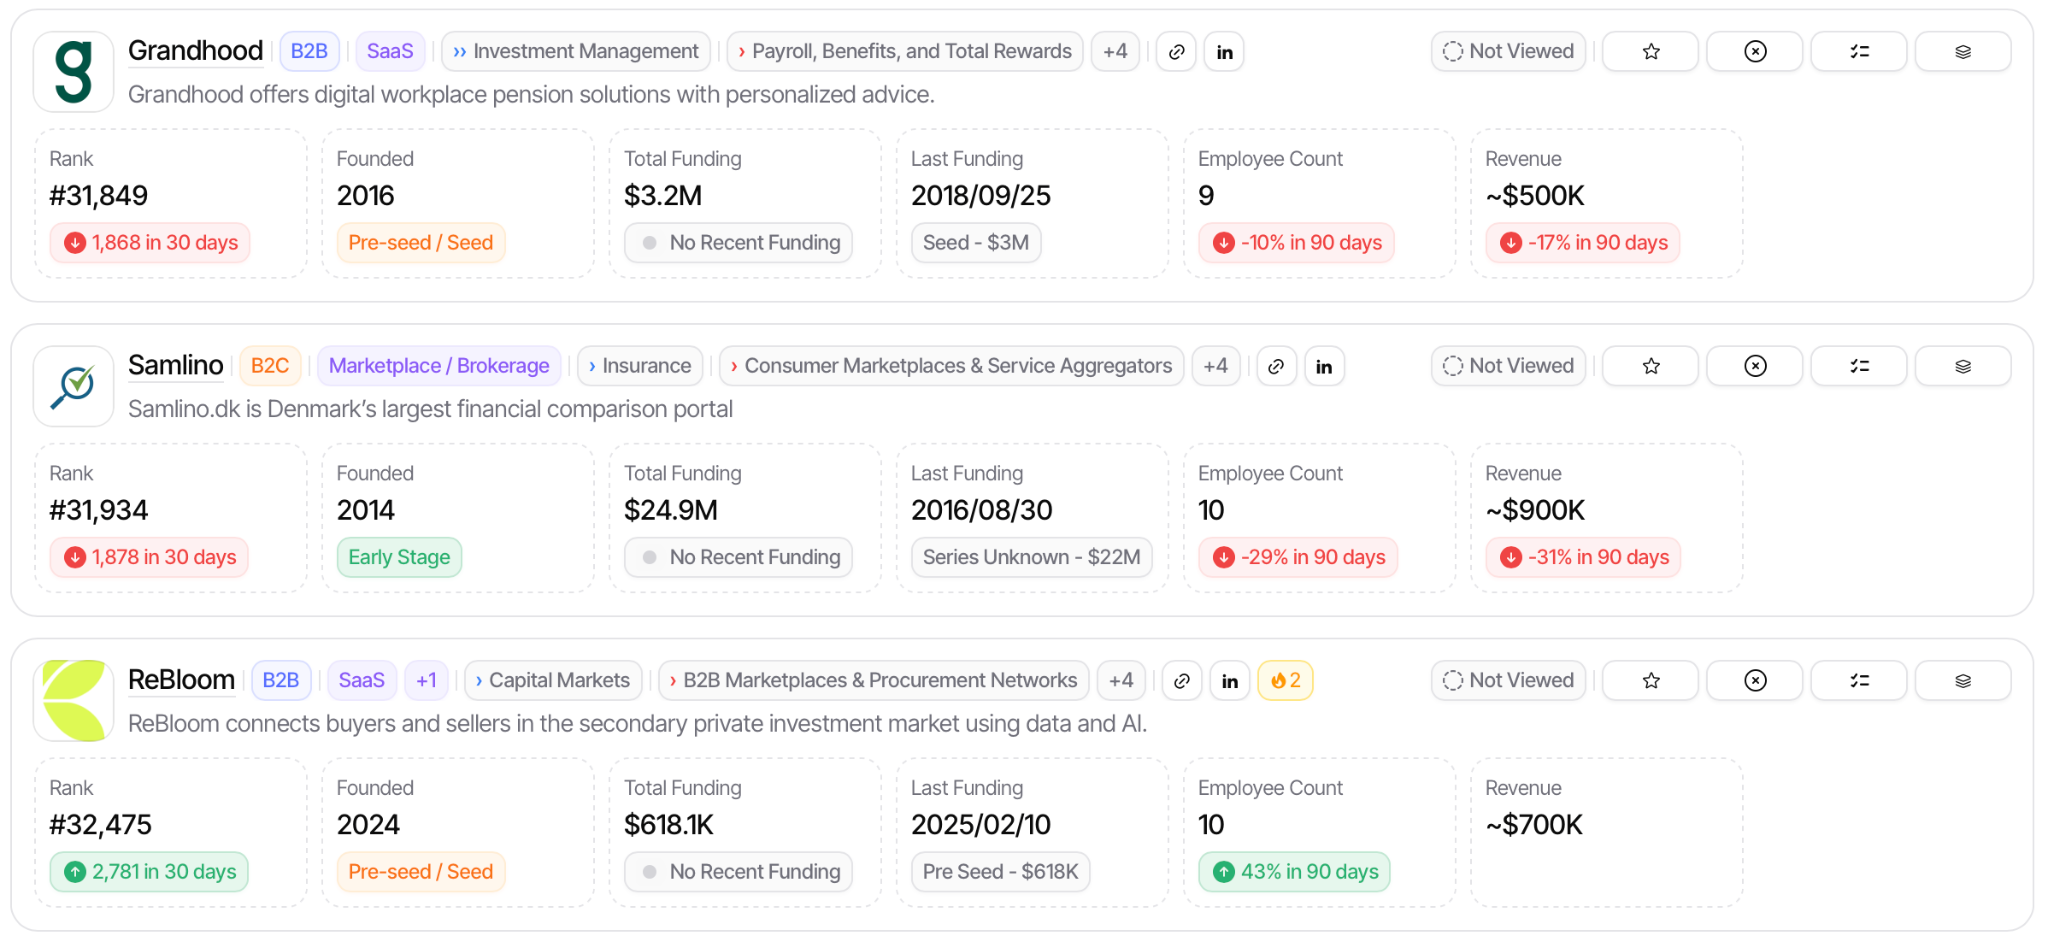
This week I took a look at the most interesting fintech startups in Copenaghen, focusing on companies bootstrapped in the early stage (pre-seed and seed).
I usually use Spectre to scout for new ideas, the team is great and they also give me a free account once they learned I was a fan of the product. So if you wanna take a look at it, you can find it here.
VCs and PEs raising new funds now
I would like to leave this part of the newsletter as space for VC and solo GP that are launching new funds right now. I frequently speak with GPs and LPs, and I like the idea of giving them a showcase where to announce what they are doing. Here the new funds raising right now that I have been talking with:
- Parallax Ventures, a fintech VC fund focused on Latam. They closed Fund I with a strong +50% IRR and 0.7x DPI, and are now raising Fund II. Take a look here if you want to know more or reach out directly to the GP at gennari@parallax.vc for details.
- Founder Factor, VC focused on YC companies, that just closed investments on the latest YC W26. They are expanding the current vehicle to double down on the current batch. You can take a look here if you are interested.
- RedFish Capital Partners, a private equity investor focused on Italian SMEs in growth and mature capital phases, with a track record exceeding 40% IRR and with over €200M in Assets. Currently raising its brand new AIF, which has already secured a soft commitment from the European Investment Fund (EIF). You can check them out at redfish.capital or contact the team at investor.relations@redfish.capital.
Overall, very interesting to see where the VC ecosystem is heading recently, between new emerging managers, solo GP and micro funds.
Always happy to support if I can! If you are raising a fund and you want to be listed here send me a message on Linkedin.
And finally, take also a look at the last edition of the newsletter, Weekly update #146
Topics
Related funding
| Company | Round | Amount | Date |
|---|---|---|---|
| Fasset Added · · Weekly update #147 | Series C | 68,000,000 USD | 24 August 2026 |
| Natural Added · · Weekly update #147 | Credit facility | 100,000,000 USD | 24 August 2026 |
| Payload Added · · Weekly update #147 | Series A | 9,000,000 USD | 26 August 2026 |
| Hivemind Capital Added · · Weekly update #147 | Strategic | 17,000,000 USD | 25 August 2026 |
| Helcim Added · · Weekly update #147 | Series C | 53,000,000 CAD | 21 August 2026 |
| Nexedge Capital Added · · Weekly update #147 | 20,000,000 USD | 25 August 2026 | |
| Repodo Added · · Weekly update #147 | Pre-seed | 8,200,000 EUR | 25 August 2026 |
| Imprint Added · · Weekly update #147 | Debt financing | 2,000,000,000 USD | 26 August 2026 |
| ItoFlow Added · · Weekly update #147 | Pre-seed | 2,500,000 USD | 25 August 2026 |
| Ajaib Added · · Weekly update #147 | Series C | 270,000,000 USD | 28 August 2026 |
| Pago ASAP Added · · Weekly update #147 | 1,150,000 USD | 24 August 2026 | |
| RQD* Clearing Added · · Weekly update #147 | Growth | 74,000,000 USD | 27 August 2026 |
| neno Added · · Weekly update #147 | Seed | 6,600,000 EUR | 25 August 2026 |
| Fina Partner Added · · Weekly update #147 | Seed | 1,000,000 USD | 27 August 2026 |
| AppsFlyer Added · · Weekly update #147 | Credit line | 400,000,000 USD | 25 August 2026 |
| Standard Metrics Added · · Weekly update #147 | Series B | 20,000,000 USD | 24 August 2026 |