Weekly update #138
The latest news from the fintech and VC ecosystems
Welcome to this edition of the weekly newsletter. The idea behind this is to gather all the information in the startup ecosystem in one place, with a special focus on the fintech market and the VC industry.
The latest episode of Builders has been released last week! In this episode, I sit down with Deniz Güven 顧海, CEO of wamo. You can watch the full episode here on YouTube, or listen to it here on Spotify or here on Apple Podcast. But take a look at a quick clip first:
Deniz is a senior fintech and digital banking executive with extensive experience building financial services across Europe, the Middle East, and Asia. He is currently Group CEO and Chair of the Board at wamo, and has held leadership and board roles at AKTech, Platform XIT, Colendi, Trust Bank Singapore, and Beşiktaş JK.
Previously, Deniz served as CEO of Mox Bank in Hong Kong, the virtual bank backed by Standard Chartered, and held senior digital leadership roles at Standard Chartered and Garanti BBVA. His career spans digital banking, fintech ventures, product innovation, and alternative revenue streams. Deniz has also mentored fintech start ups through Garanti Partners and brings a global perspective on how digital platforms are reshaping financial services.
With him, we will talk about SMEs banking in Europe, but also about his incredible careers in banking across APAC and MENA, and the future of banking.
Coming back to us, I’ve been reading a very interesting report this week, “Private credit in 2025: a maturing industry navigates change” by McKinsey & Company. Private credit markets recently are on everyone’s mouth, mostly because of the disruption we currently see on the infrastructure side. But what’s their shape in terms of size, deals and returns? Here my main takeaways:
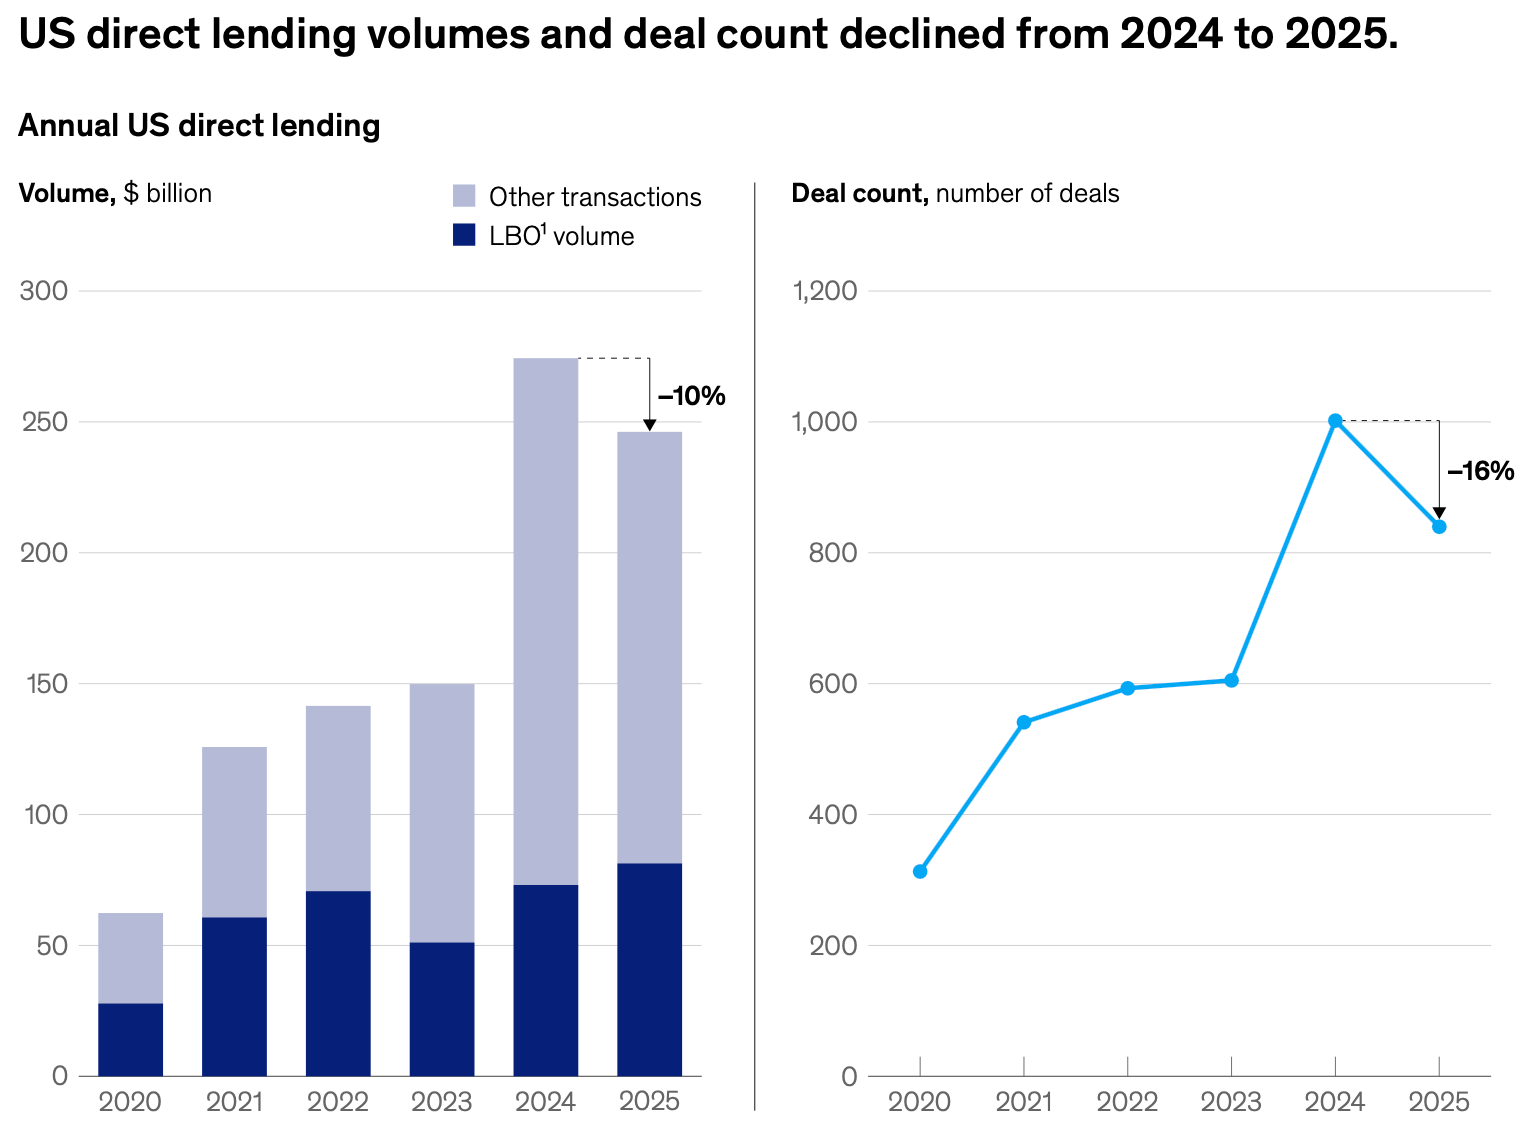
In 2025, direct lending remained near historic highs despite softer activity. Estimated US volume declined by approximately 10 percent, while deal count fell about 16 percent, although both remained well above pre-2024 levels. Rising capital availability and deployment pressure strengthened borrowers’ negotiating position and increased competition among lenders.
Leveraged buyout financing reached a record $81 billion, up from $73 billion in 2024, even as LBO deal count declined from 248 to 214. Growth therefore came from fewer, larger transactions. Average direct lending LBO deal size increased by 29 percent to approximately $380 million, compared with about $295 million in 2024 and $200 million in 2020.
Non-LBO activity, including refinancings and recapitalizations, declined by nearly 20 percent year on year. Meanwhile, Adevinta completed a €6.5 billion unitranche refinancing, the largest direct lending transaction on record, reflecting the market’s continued expansion into larger deals.
Competition for direct lending deals intensified in 2025. Closed-end dry powder reached approximately $500 billion in the first half of 2025, while semiliquid vehicles increased deployment pressure. Banks and the broadly syndicated loan market also competed more aggressively, with J.P. Morgan allocating $50 billion to private-credit-style lending.
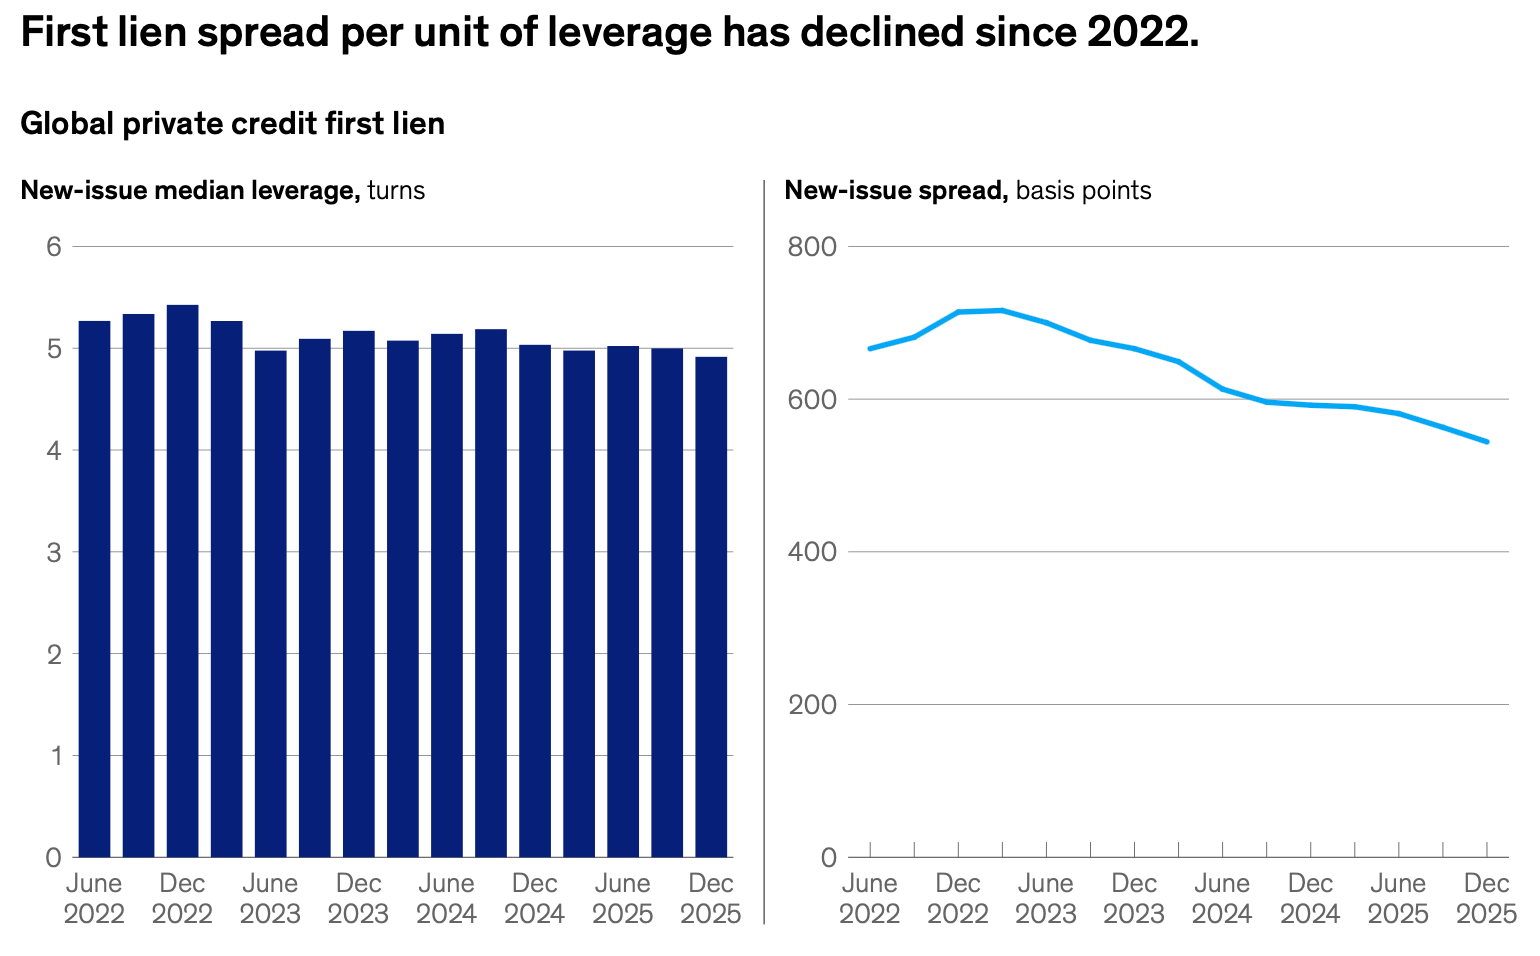
Refinancing flows neared parity: approximately $37 billion moved from syndicated loans into direct lending, while $34 billion shifted the other way. Median spreads fell from 716 basis points in March 2023 to 666 at year-end 2023, 596 in 2024 and 544 in 2025. Origination prices rose from 98.4 percent of par in 2023 to 99.1 percent. Three-month SOFR averaged 4.35 percent in 2025, versus 5.27 percent in 2024, reducing yields from 10.5 percent to 9.3 percent. Leverage averaged 4.9 times EBITDA, compared with 5.0 in 2024 and 5.2 in 2023, while covenant-lite deals increased from 4 percent to 21 percent.
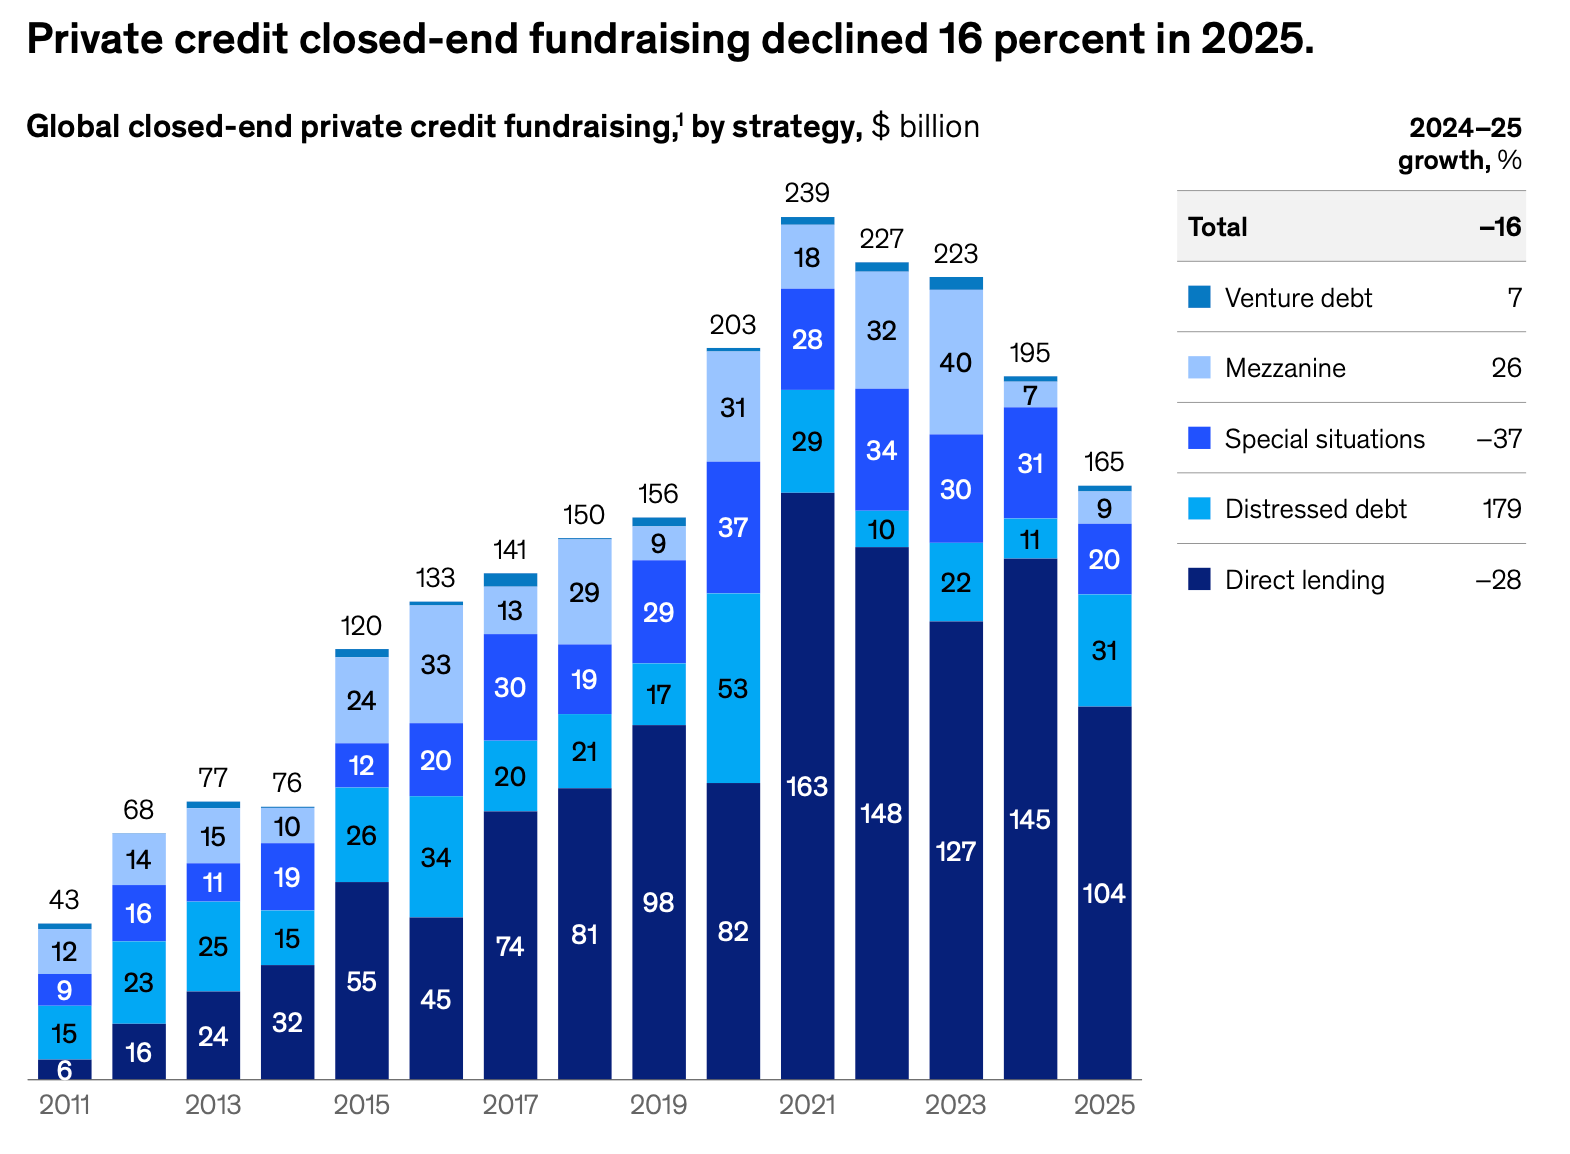
Private credit fundraising softened in 2025, with closed-end capital raising falling 16 percent year over year to approximately $165 billion. Since 2021, closed-end private credit and private equity fundraising have declined by 9 percent and 12 percent per annum, respectively. However, capital is increasingly entering through BDCs, evergreen and interval funds, insurance mandates and other permanent-capital vehicles.
Direct lending fundraising declined 28 percent, while strategies outside direct lending grew 22 percent. Distressed debt surged nearly 180 percent, supported by Oaktree Capital Management, L.P. ’s record $16 billion Opportunities Fund XII. Mezzanine fundraising recovered approximately 26 percent after falling 80 percent in 2024, whereas special situations declined 37 percent.
Fundraising decreased across all major regions. North America represented 64 percent of the global total and Europe 32 percent. Since 2021, their closed-end fundraising has contracted at annual rates of 8 percent and 9 percent, respectively.
Distressed debt fundraising rose nearly 180 percent, supported by Oaktree Capital Management’s record $16 billion Opportunities Fund XII. Mezzanine fundraising increased approximately 26 percent after declining 80 percent in 2024, while special situations fell 37 percent.
Closed-end fundraising decreased across all major regions in 2025. North America represented 64 percent of global fundraising and Europe 32 percent, with respective CAGRs of –8 percent and –9 percent since 2021.
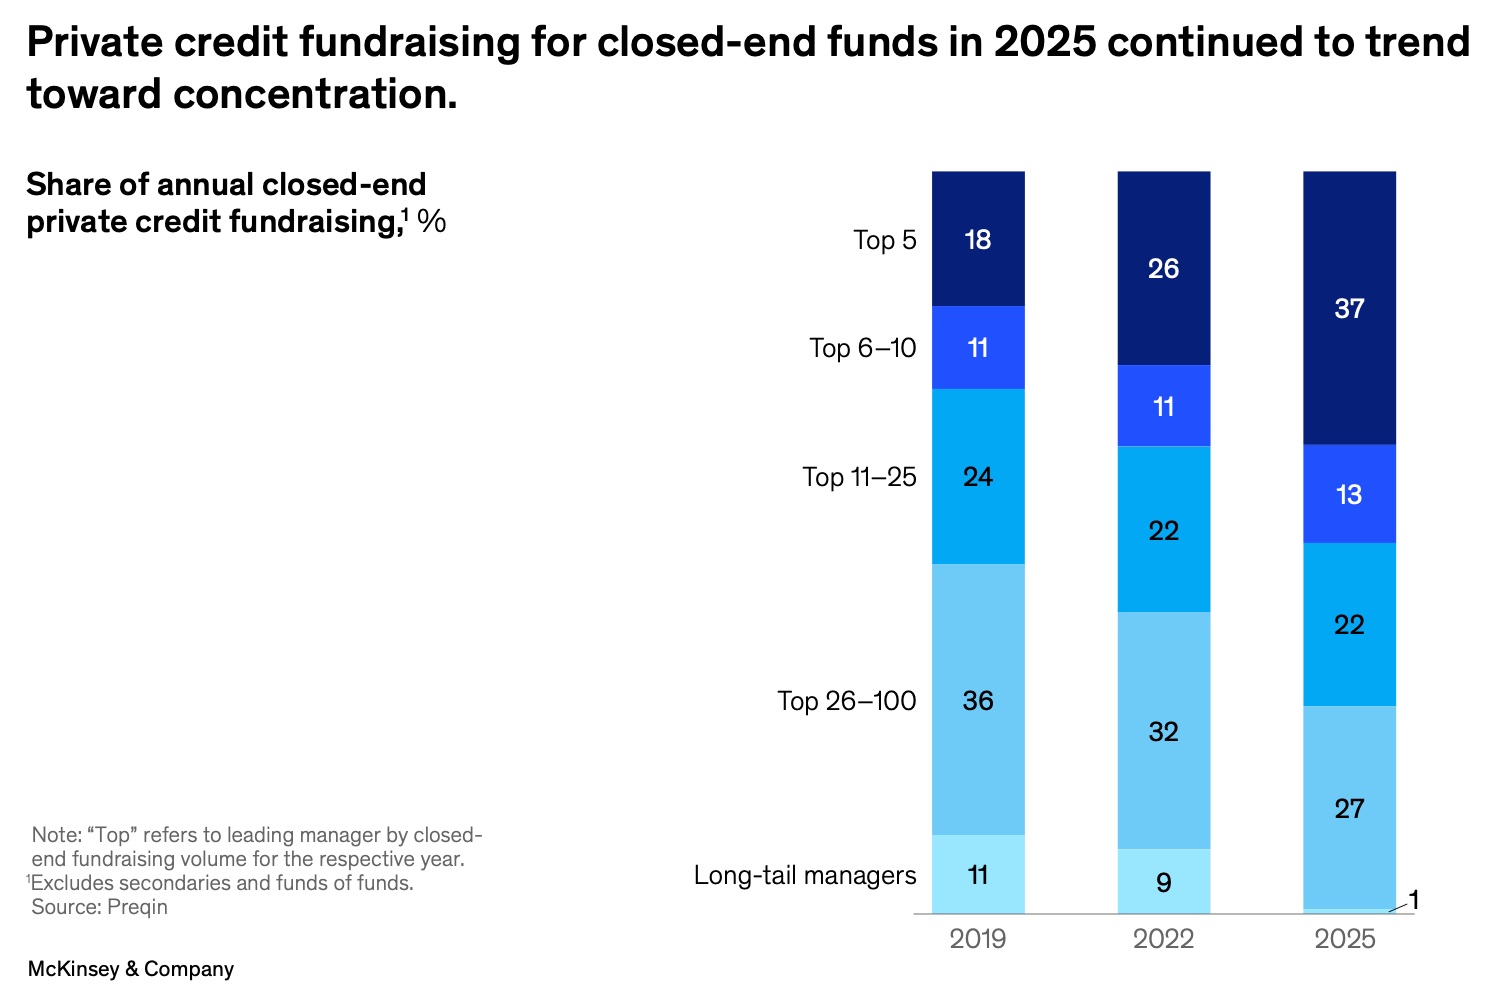
Capital also became more concentrated. Ares Management raised €17.1 billion for its sixth European fund, while the top 25 managers captured approximately 72 percent of fundraising. The seven largest platforms expanded AUM by approximately 20 percent annually from 2022 to 2025.
Evergreen and open-end AUM grew approximately 27 percent in 2025. In Q4, BDC redemptions nearly tripled, averaging 4.5 percent of NAV, and five BDCs exceeded their 5 percent quarterly caps.
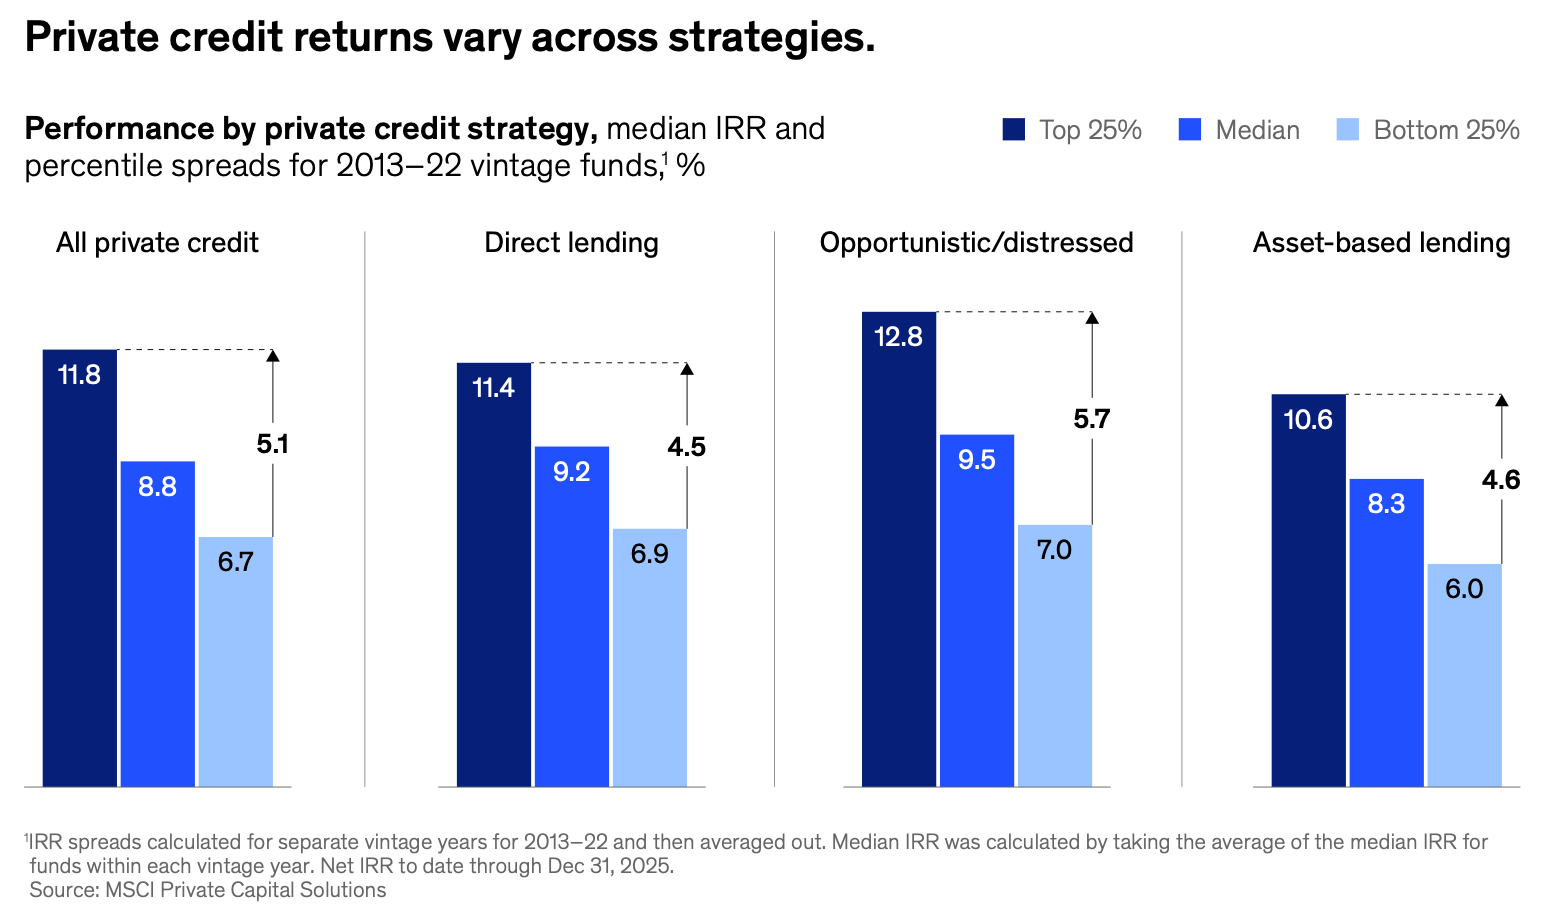
Private credit performance remained resilient in 2025 despite defaults and closer scrutiny of portfolio quality. Pooled net IRR reached 8.5 percent, up from 7.0 percent in 2024 and close to the 8.8 percent median for 2013–2022 vintages. Return dispersion was 5.1 percentage points, compared with 14.3 for private equity and 6.7 for infrastructure.
Across private credit, top-quartile, median and bottom-quartile returns were 12.8 percent, 8.8 percent and 6.7 percent. The equivalent figures were 11.8 percent, 9.2 percent and 7.0 percent for direct lending; 11.4 percent, 10.6 percent and 6.9 percent for opportunistic and distressed credit; and 9.5 percent, 8.3 percent and 6.0 percent for asset-based lending.
Interest coverage improved from 1.83 to 2.09 times EBITDA. Payment-in-kind income declined from 8.1 percent to 7.3 percent. Loans marked below 90 rose from 4.9 percent to 5.5 percent in the US and from 4.6 percent to 5.4 percent globally.
But let’s take a closer look at the main news of the last seven days, bunq launches in Italy, Airbnb enters fintech a flexible payment product, Erste Group and Raiffeisen Bank International AG join EPI Company to boost Wero adoption, Revolut waitlist in Africa tops 100k users. But also, Bending Spoons officially files for a Nasdaq IPO, Ripple gets a MiCA license in Europe, MoonPay acquires Entendre and Backbase acquires Kasisto AI. In the VC ecosystem, Seedcamp launches a new $320M fund to back european founders, Norrsken Launcher a new $80M fund, Gareth Bale join Juggernaut Capital Partners to launch a $500M fund to invest in sport assets. But also new funds from Nucleo Ventures, Menlo Ventures, Main Capital Partners and Senovo. And finally, some very interesting funding rounds from fintech startups like fomo, Taktile, Lama AI, Caplight, Allium, equipal and many others.
Let’s take a closer look:
Rounds
- Meta explores CRED investment at $4B valuation
- fomo raises $75M series B to scale social first trading platform
- compri raises €3.2M to scale its AI workforce for industrial procurement
- Allium raises $40M to build the system of record for onchain finance
- equipal secures €18.84M to expand UK equipment finance platform
- Taktile raises $110M series C led by Goldman Sachs!
- Lama AI raises$20M series A to scale AI native loan origination
- Kalipso raises $3.2M to scale AI powered regulatory compliance
- Airwallex raises $320M at $11B valuation!
- Caplight raises $16M to scale private market data and liquidity infrastructure
- Libeara raises US$14M to scale regulated tokenisation infrastructure
- Trovy raises $15M to expand home equity lending platform
- Talentir raises €4M to reinvent global creator payouts
- GrailPay raises $10.5M to build the trust layer for instant payments
- Orthogonal (YC W26) raises $4.3M to build infrastructure for agentic commerce
VC funds
- Seedcamp raises $320M to back Europe’s next global technology leaders
- Norrsken Launcher closes €80M fund II for deeptech impact ventures
- Gareth Bale joins Juggernaut Capital Partners to launch a £500M fund to invest in sport assets
- Nucleo Ventures launches €34M fund for Central and Eastern European startups
- Menlo Ventures raises record $3B fund following Anthropic bet
- Main Capital Partners closes €5.25B across two enterprise software funds
- Senovo closes fund IV above $100M for European B2B software
News on the market
- Erste Group and Raiffeisen Bank International AG join EPI Company to bring Wero to Austria
- bunq launches IT Ibans and BaaS product
- Airbnb enters fintech with flexible cancellation payment product
- Midas moves toward digital payments with Turkish eMoney license application
- Younited and Nexi Group partner to bring instant credit to italian checkouts
- Pollen Street Capital to acquire Finastra’s Universal Banking business
- Bending Spoons officially filed for a Nasdaq IPO valued at up to $1.8B
- Revolut’s South Africa waitlist approaches 100,000 ahead of 2028 launch
- Backbase acquires Kasisto AI to accelerate agentic banking
- MoonPay acquires Entendre to expand agentic finance infrastructure
- SoFi acquires Composer by SoFi to expand AI powered retail trading
- Van Lanschot Kempen joins EPI Company to bring Wero to private banking clients
- Ripple secures preliminary MiCA approval to scale payments across Europe
- Revolut targets 50,000 New Zealand business customers with SME platform
- BKN301 launches sovereign AI infrastructure for banking operations
- Revolut splits global risk and compliance leadership
And here some useful resources for everyone involved in the ecosystem:
Events you don’t want to miss
- We make future | Bologna | 24-26 June (link here)
- Dutch blockchain week | Amsterdam | 22-28 June (link here)
You have a cool event you want to mention or to sponsor? Feel free to send me a DM.
Founders to watch in fintech
I also wanted to start shining a light on the most interesting fintech founders out there, so I thought to start sharing how I look for ideas to invest on. Every week, I will start sharing the most interesting founders in fintech, divided per area.
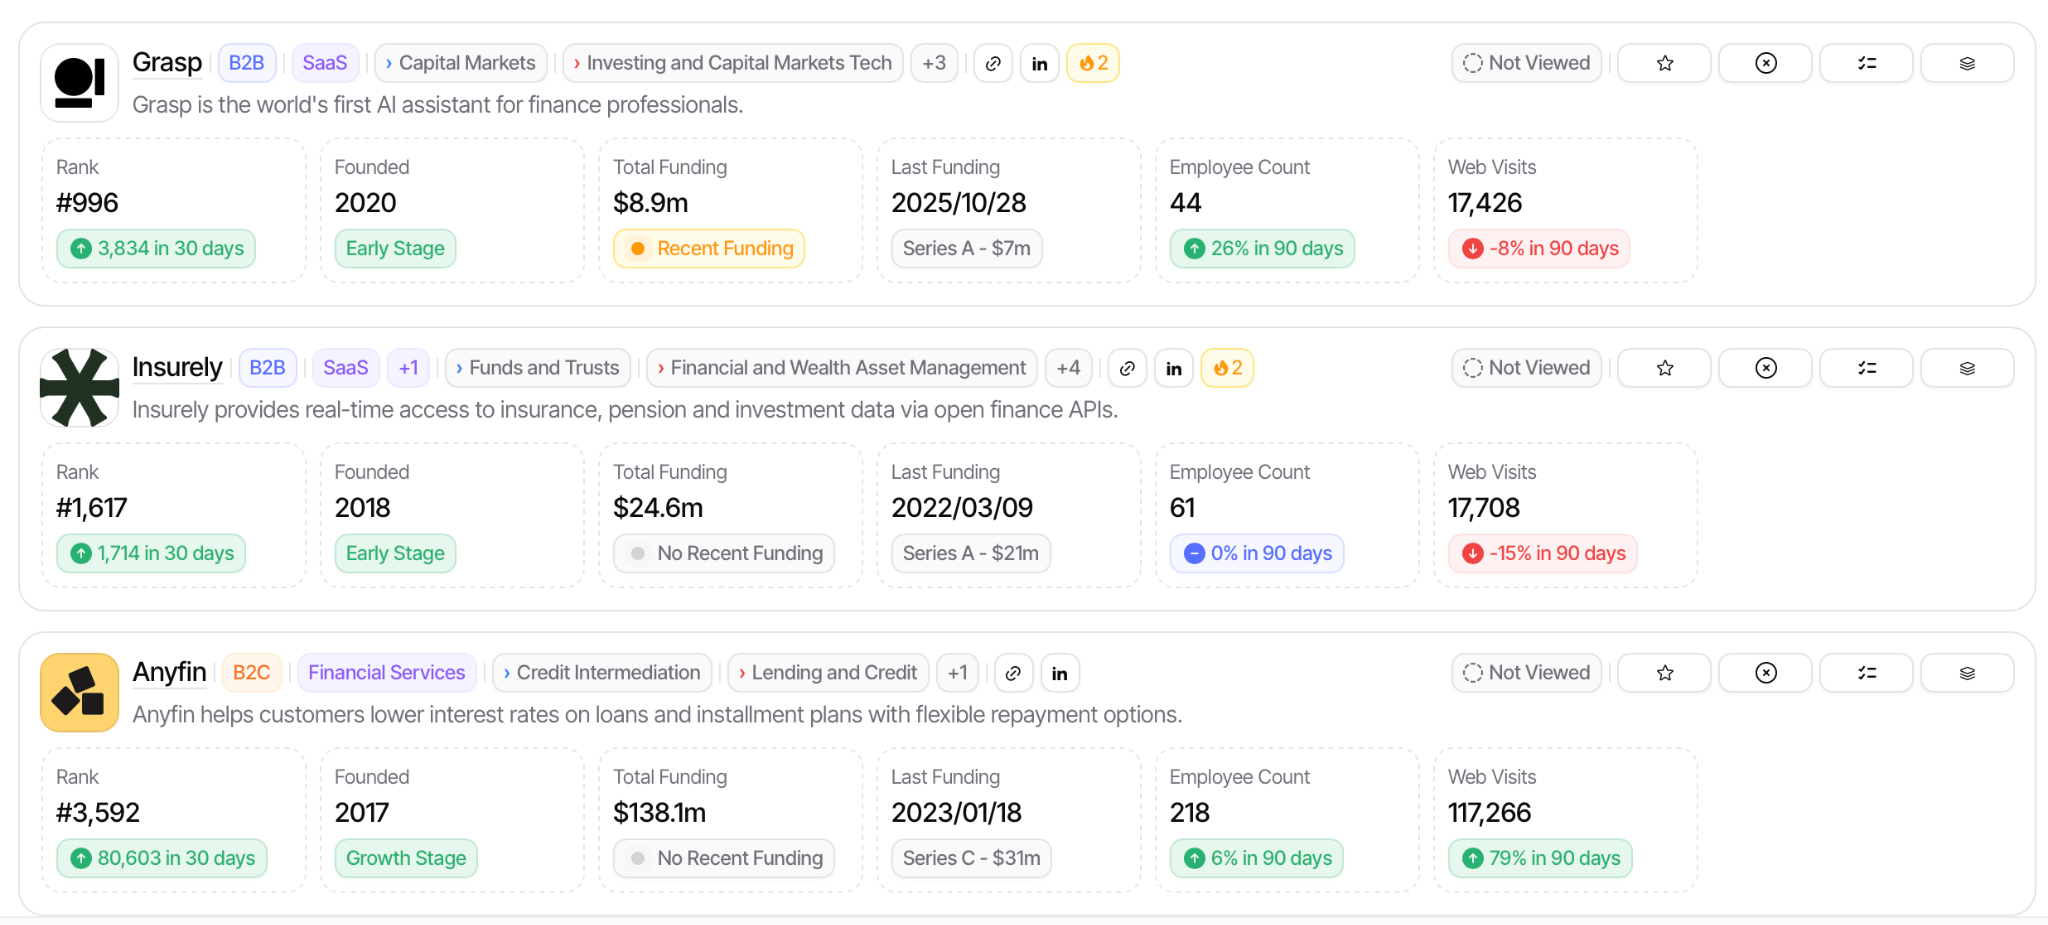
This week I am taking a look at the most interesting fintech companies in Sweden! And you can already see a couple of interesting founders in stealth!
I usually use Spectre to scout for new ideas, the team is great and they also give me a free account once they learned I was a fan of the product. So if you wanna take a look at it, you can find it here.
VCs and PEs raising new funds now
I would like to leave this part of the newsletter as space for VC and solo GP that are launching new funds right now. I frequently speak with GPs and LPs, and I like the idea of giving them a showcase where to announce what they are doing. Here the new funds raising right now that I have been talking with:
- Parallax Ventures, a fintech VC fund focused on Latam. They closed Fund I with a strong +50% IRR and 0.7x DPI, and are now raising Fund II. Take a look here if you want to know more or reach out directly to the GP at gennari@parallax.vc for details.
- Founder Factor, VC focused on YC companies, that just closed investments on the latest YC W26. They are expanding the current vehicle to double down on the current batch. You can take a look here if you are interested.
- RedFish Capital Partners, a private equity investor focused on Italian SMEs in growth and mature capital phases, with a track record exceeding 40% IRR and with over €200M in Assets. Currently raising its brand new AIF, which has already secured a soft commitment from the European Investment Fund (EIF). You can check them out at redfish.capital or contact the team at investor.relations@redfish.capital.
Overall, very interesting to see where the VC ecosystem is heading recently, between new emerging managers, solo GP and micro funds.
Always happy to support if I can! If you are raising a fund and you want to be listed here send me a message on Linkedin.
And finally, take also a look at the last edition of the newsletter, Weekly update #137
Topics
Related funding
| Company | Round | Amount | Date |
|---|---|---|---|
| Lama AI Added · · Weekly update #138 | Series A | 20,000,000 USD | 25 June 2026 |
| Trovy Added · · Weekly update #138 | Series A | 15,000,000 USD | 24 June 2026 |
| Allium Added · · Weekly update #138 | Series B | 40,000,000 USD | 23 June 2026 |
| Caplight Added · · Weekly update #138 | Series A | 16,000,000 USD | 24 June 2026 |
| Airwallex Added · · Weekly update #138 | Series H | 320,000,000 USD | 25 June 2026 |
| GrailPay Added · · Weekly update #138 | Series A | 10,500,000 USD | 25 June 2026 |
| Orthogonal Added · · Weekly update #138 | Seed | 4,300,000 USD | 25 June 2026 |
| compri Added · · Weekly update #138 | Seed | 3,200,000 EUR | 24 June 2026 |
| Kalipso Added · · Weekly update #138 | Seed | 3,200,000 USD | 25 June 2026 |
| fomo Added · · Weekly update #138 | Series B | 75,000,000 USD | 22 June 2026 |
| Talentir Added · · Weekly update #138 | Seed | 4,000,000 EUR | 25 June 2026 |
| Libeara Added · · Weekly update #138 | Strategic | 14,000,000 USD | 23 June 2026 |
| Taktile Added · · Weekly update #138 | Series C | 110,000,000 USD | 24 June 2026 |
| equipal Added · · Weekly update #138 | 1,250,000 GBP | 23 June 2026 |