Weekly update #128
The latest news on the fintech and VC ecosystems
Welcome to this edition of the weekly newsletter. The idea behind this is to gather all the information in the startup ecosystem in one place, with a special focus on the fintech market and the VC industry.
No episode of Builders has been released this week, but you can always recover the last one, where I sit down with Aurimas Bakas, CEO and founder of Copla. You can watch the full episode here on YouTube, or listen to it here on Spotify, here on Amazon Podcast or here on Apple Podcast.
Aurimas is a serial fintech entrepreneur and chief executive with over two decades of experience building and scaling technology-driven businesses across Europe and globally. He is currently the co-founder of Copla, focusing on bridging the gap between cyber readiness and operational security in fintech.
Aurimas is best known for founding Paysolut, a banking technology company serving fintech scale-ups, which was successfully acquired by SumUp in 2021. His track record also includes multiple exits, such as DtecNet to Markmonitor and Marguard to Prisync | Dynamic Pricing, alongside leadership roles in companies later acquired by QUAERO CAPITAL .
Earlier in his career, he played a key role in expanding international operations for Gaumina and scaling DtecNet into a global anti-piracy leader. His experience spans payments, data infrastructure, and enterprise software, complemented by executive education at UC Berkeley.
Coming back to us, this week I’ve been reading a very interesting report, the “VC Fund performance” by Carta. The report is a very interesting study spanning from 2017 until 2025, taking in consideration average returns for VC funds in different geographies, with different sizes and focus. Here my main take aways:
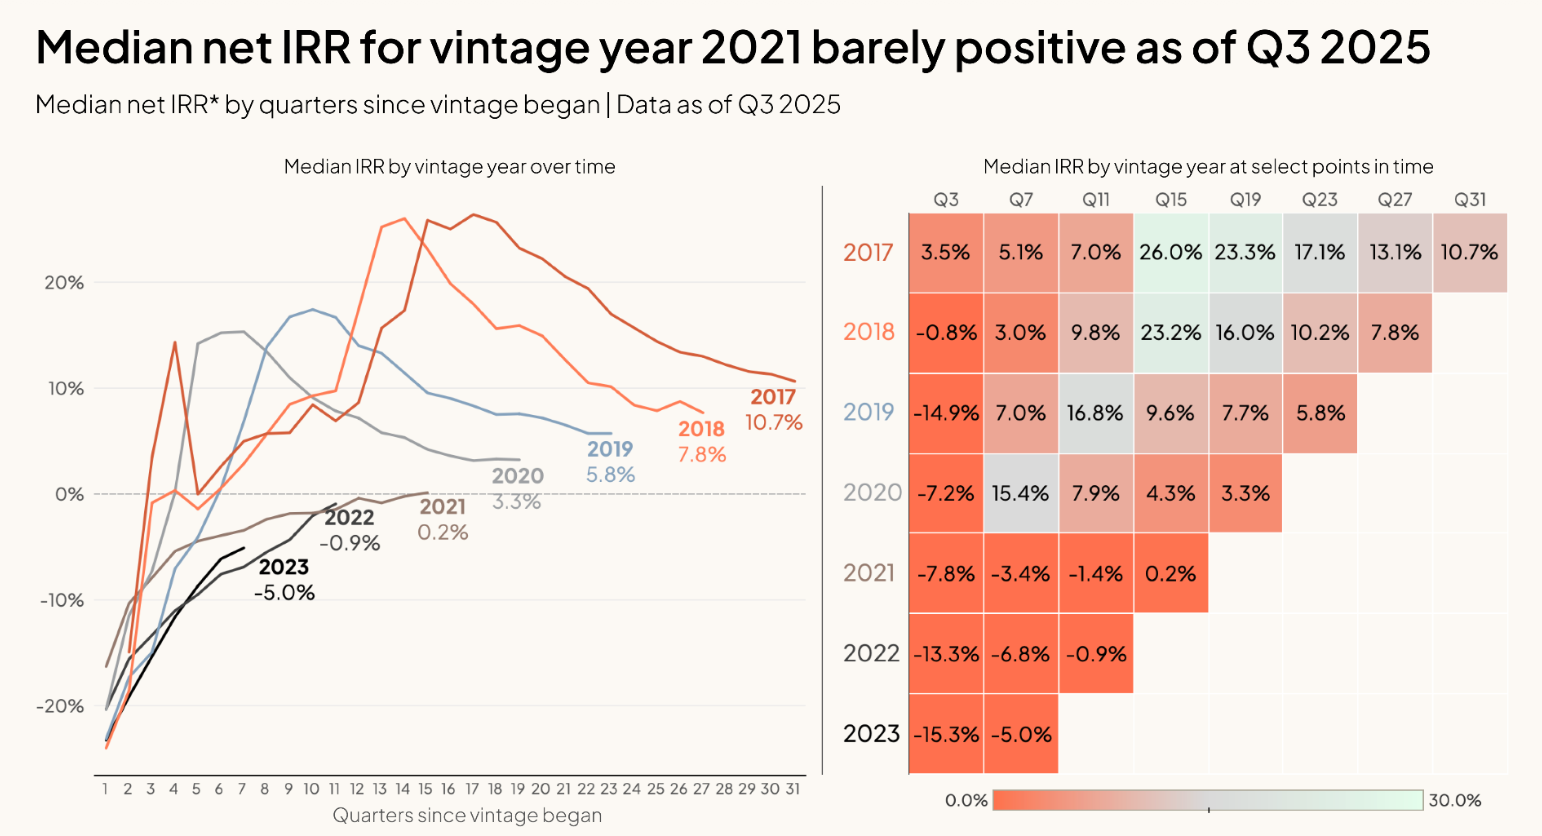
Median IRRs for the 2021, 2022, and 2023 venture fund vintages remain significantly below those of earlier vintages at comparable stages. After 15 quarters of management, nearly four years, the 2021 vintage reports a median IRR of just 0.2%, compared to 4.3% for the 2020 vintage at the same point, and 26% for the 2017 vintage.
This pattern reflects the typical J-curve dynamic in venture capital. In the early years, returns are often negative, as still observed for the 2022 and 2023 vintages, due to upfront investments and unrealized gains. Over time, as portfolios mature and exits occur, IRRs tend to turn positive and increase. As of Q3 2025, each successive newer vintage continues to underperform all prior vintages in median IRR terms, reinforcing the lagged nature of venture fund performance.
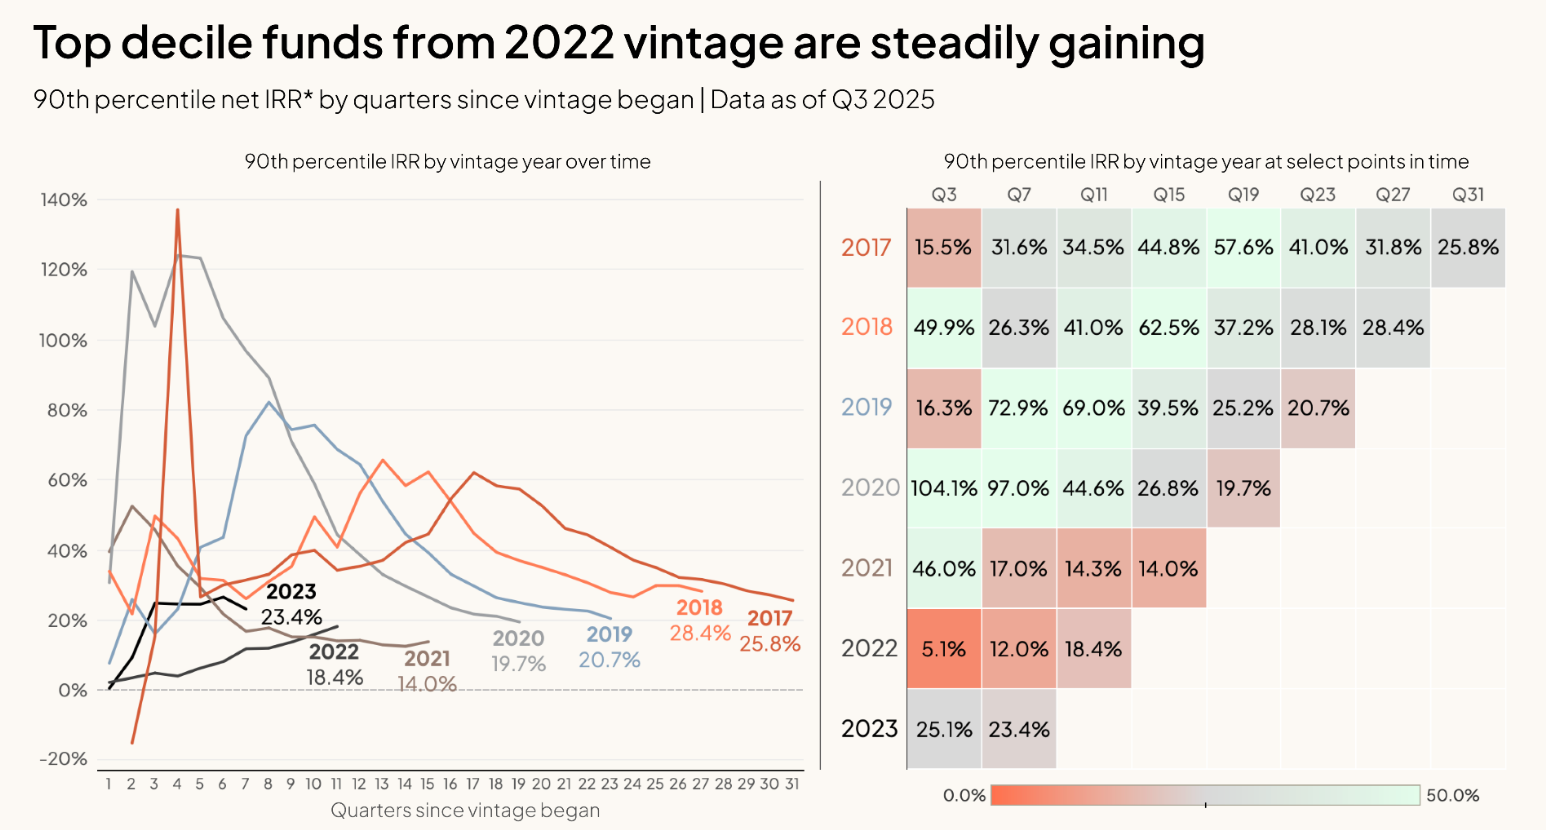
Top-decile IRR trends diverge across recent venture vintages. For funds launched between 2017 and 2021, the 90th percentile IRR has declined consistently over the past ten quarters. In contrast, more recent vintages are showing stronger momentum.
The 2022 vintage has seen steady improvement in top-decile performance, reaching a 90th percentile IRR of 18.4% after 11 quarters, surpassing the 2021 vintage at the same stage. The 2023 vintage is advancing even faster, with its 90th percentile IRR rising to 23.4% after just seven quarters.
This level is not only well above the current top-decile returns for both 2021 and 2022, but also approaches the performance achieved by the 2017 and 2018 vintages at a comparable point in their lifecycle, suggesting early signs of stronger upside dispersion in newer funds.
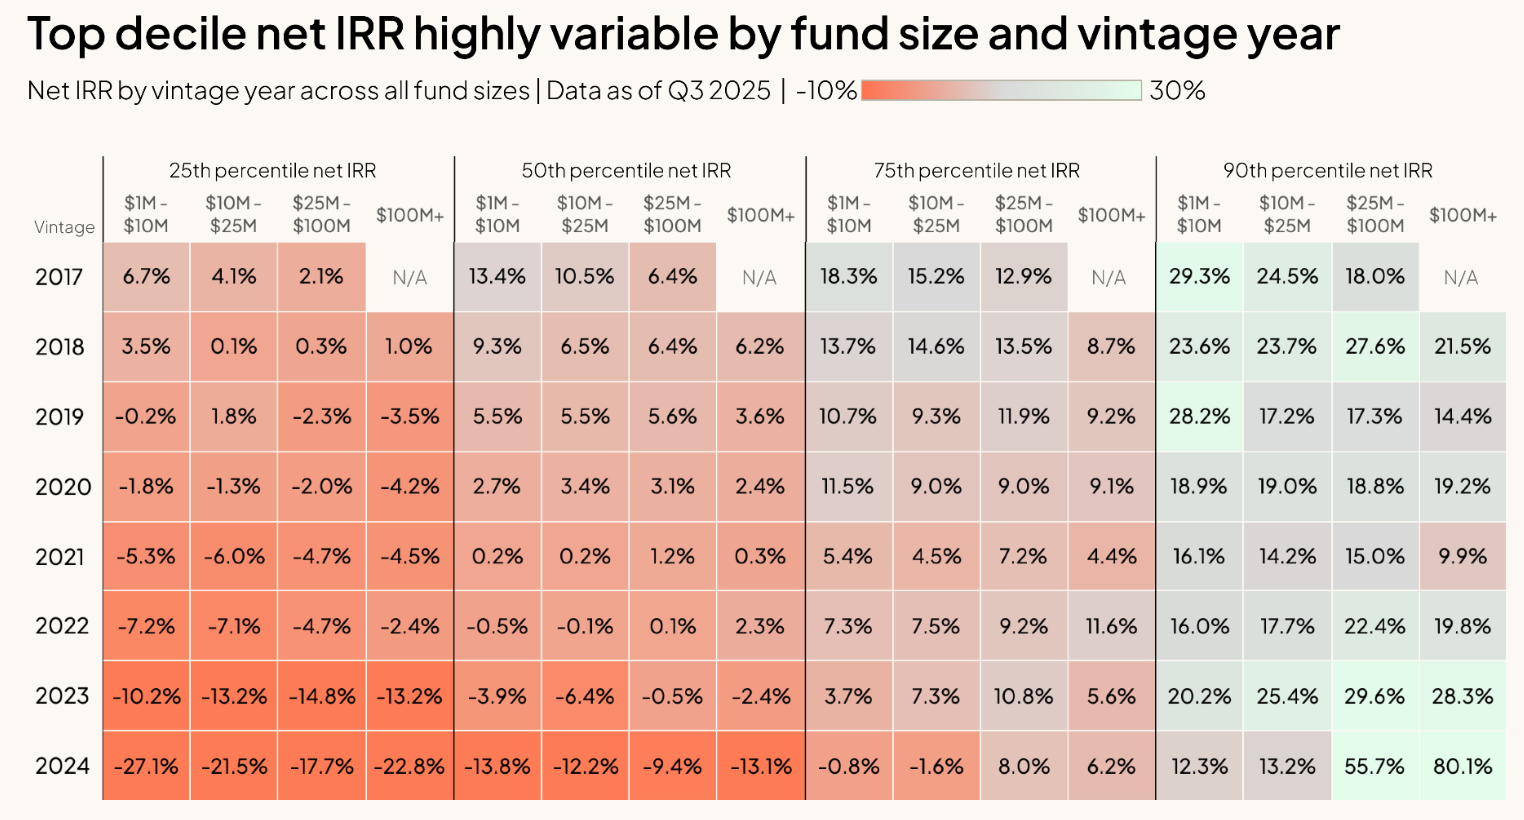
The table compares IRR performance across fund sizes and vintages, revealing two broad patterns, despite some exceptions. First, smaller funds generally outperform larger ones, a well-established dynamic that tends to persist even as portfolios mature and more investments are realized.
Second, older vintages of still-active funds typically show stronger performance than newer ones. This is largely explained by time: older funds have had more opportunity to develop their portfolios, generate exits, and increase the value of underlying investments. As a result, comparisons with newer vintages are inherently uneven.
Together, these trends suggest that both fund size and vintage play a significant role in shaping IRR outcomes, with structural advantages favoring smaller and more seasoned funds over larger or more recently launched counterparts.
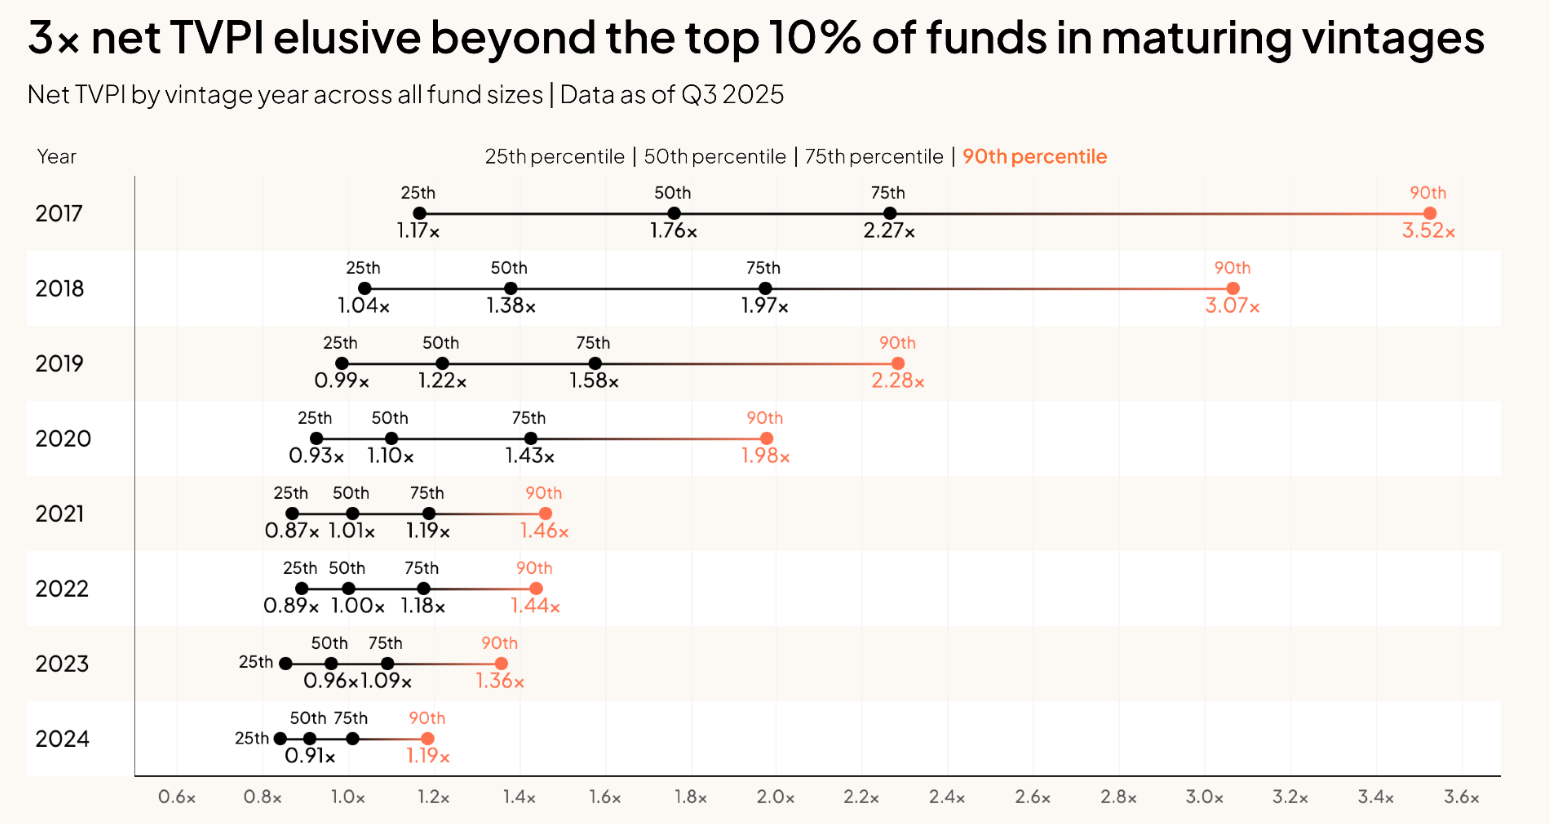
Eight years into its lifecycle, the 2017 venture vintage reports a median net TVPI of 1.76x, with strong dispersion at the top end. The 75th percentile reaches 2.27x, while the 90th percentile climbs to 3.52x. Even lower-quartile funds are generating positive returns, with a 25th percentile TVPI of 1.17x.
Across all these thresholds, the 2017 vintage outperforms every subsequent vintage from 2018 to 2024. This reflects the typical J-curve dynamic, where performance strengthens over time as investments mature and exits materialize.
In contrast, more recent vintages from 2021 to 2024 show a much tighter range of outcomes. Their top-decile TVPI remains below 1.5x, while the lower quartile ranges between 0.8x and 0.9x, indicating more limited value creation at this stage of their lifecycle.
But let’s take a closer look at the main news of the last seven days. Revolut launched GlobalHire to expand in HRtech, OpenAI acquired personal finance startup Hiro Finance, Trade Republic committed to bring back human support 24/7 and Monzo Bank entered the Irish market. But also, Revolut unveils financial model PRAGMA, Tether.io launched self custodian wallet, PayPal integrates Pix in Brasil and eToro acquired Zengo Wallet. Lots of interesting new funds in the VC market! Accel raised a $5B fund while Sequoia Capital raised a $7B fund, but also new funds from Eka Ventures and Newfund. And finally, some very interesting funding rounds from fintech startups like wamo, Ralio, Pillar, Brix, Slash, Banco Plata, Balerion AI and many others.
Let’s take a closer look:
Rounds
- Round Treasury raises $6M to rebuild finance operations with AI driven automation
- Astranova Mobility raises $6.4M Series A to scale EV financing across India
- Standard Bank Group commits $330M to Optasia to accelerate Pan-African fintech expansion
- SimpleChain Foundation Official secures $15M to build RWA focused layer 1 for Asia’s tokenized asset boom
- Ralio raises $2.5M to build Europe’s first payments infrastructure for AI agents
- wamo raises €10M Series A to scale SME financial infrastructure across Europe
- Casavo acquires Casando Agency and raises €12M to accelerate real estate platform expansion
- Deutsche Börse Group invests $200M in Kraken to advance institutional crypto markets
- Zell secures €500K to expand AI driven sales management platform across Europe
- Common Wealth Retirement raises $12M Series A to expand retirement access for Canadian workers
- Paxos spins off DeFi arm as Paxos Labs secures $12M to expand stablecoin utility
- Pillar raises $20M seed led by Andreessen Horowitz to automate commodity risk management
- BlockInvest closes a $5.4M strategic round led by UniCredit
- Depay raises $4M to scale cross border instant payments infrastructure from LatAm
- Haast raises $12M Series A to turn compliance into AI driven infrastructure
- spektr raises $20M Series A to automate KYC and KYB with AI agents
- SolvaPay raises €2.4M to power payments for the agentic economy
- openlaw raises $3.3M to digitize Europe’s company formation
- Brix raises $5.5M to bring emerging market assets on chain
- Smartwage Società Benefit secures €2M pre seed to reinvent employee welfare spending with AI
- Slash raises $100M Series C at $1.4B valuation
- Banco Plata reaches $5B valuation after $405M Series C
- Balerion AI raises $6M to cut mortgage origination costs and close loans faster
VC funds
- Eka Ventures closes $107M Fund II to scale impact tech across health and sustainability
- Newfund closes €60M HEKA fund to scale Europe’s brainTech and AI ecosystem
- Accel raises $5B to double down on late stage AI investments
- Sequoia Capital raises $7B fund to double down on AI expansion strategy
News on the market
- Revolut enters Turkey with app launch in waiting list and banking license strategy
- Moltiply Group’s Mavriq acquires 100% of Italian fintech Switcho
- XTB online investing upgrades UAE licence to full broker status, expanding MENA strategy
- OpenAI acquires personal finance startup Hiro Finance
- Worldline and YouLend launch cash advance to unlock SME liquidity in Poland
- Monzo Bank enters Ireland with 100,000 waitlist users ahead of EU expansion
- PayPal integrates Pix to boost SMB payments in Brazil’s $944B digital commerce market
- Revolut expands into HRtech with launch of GlobalHire platform
- Norta launches from 0TO9 | Bank of Entrepreneurship to address Europe’s €285M financial stress gap
- Tether.io launches self custodial wallet to bring digital dollars to 570M users
- eToro acquires Zengo Wallet to strengthen self custody and on chain strategy
- Trade Republic commits to bring back human to customer support and restore trust
- Revolut unveils PRAGMA: a foundation model built on 40B banking events
- Allica Bank and ClearBank deliver third year of profitability as UK fintechs scale
- Vivid brings Ray Dalio’s “All Weather” portfolio to SMEs targeting 8% returns
- GoCardless grows revenue to £155.5M while advancing toward profitability
And here some useful resources for everyone involved in the ecosystem:
Events you don’t want to miss
- Stablecon EMEA | Amsterdam - 19th-20th May (Link here)
- Money 20/20 | Amsterdam - 02-04 June (Link here)
You have a cool event you want to mention or to sponsor? Feel free to send me a DM.
Founders to watch in fintech
I also wanted to start shining a light on the most interesting fintech founders out there, so I thought to start sharing how I look for ideas to invest on. Every week, I will start sharing the most interesting founders in fintech, divided per area.
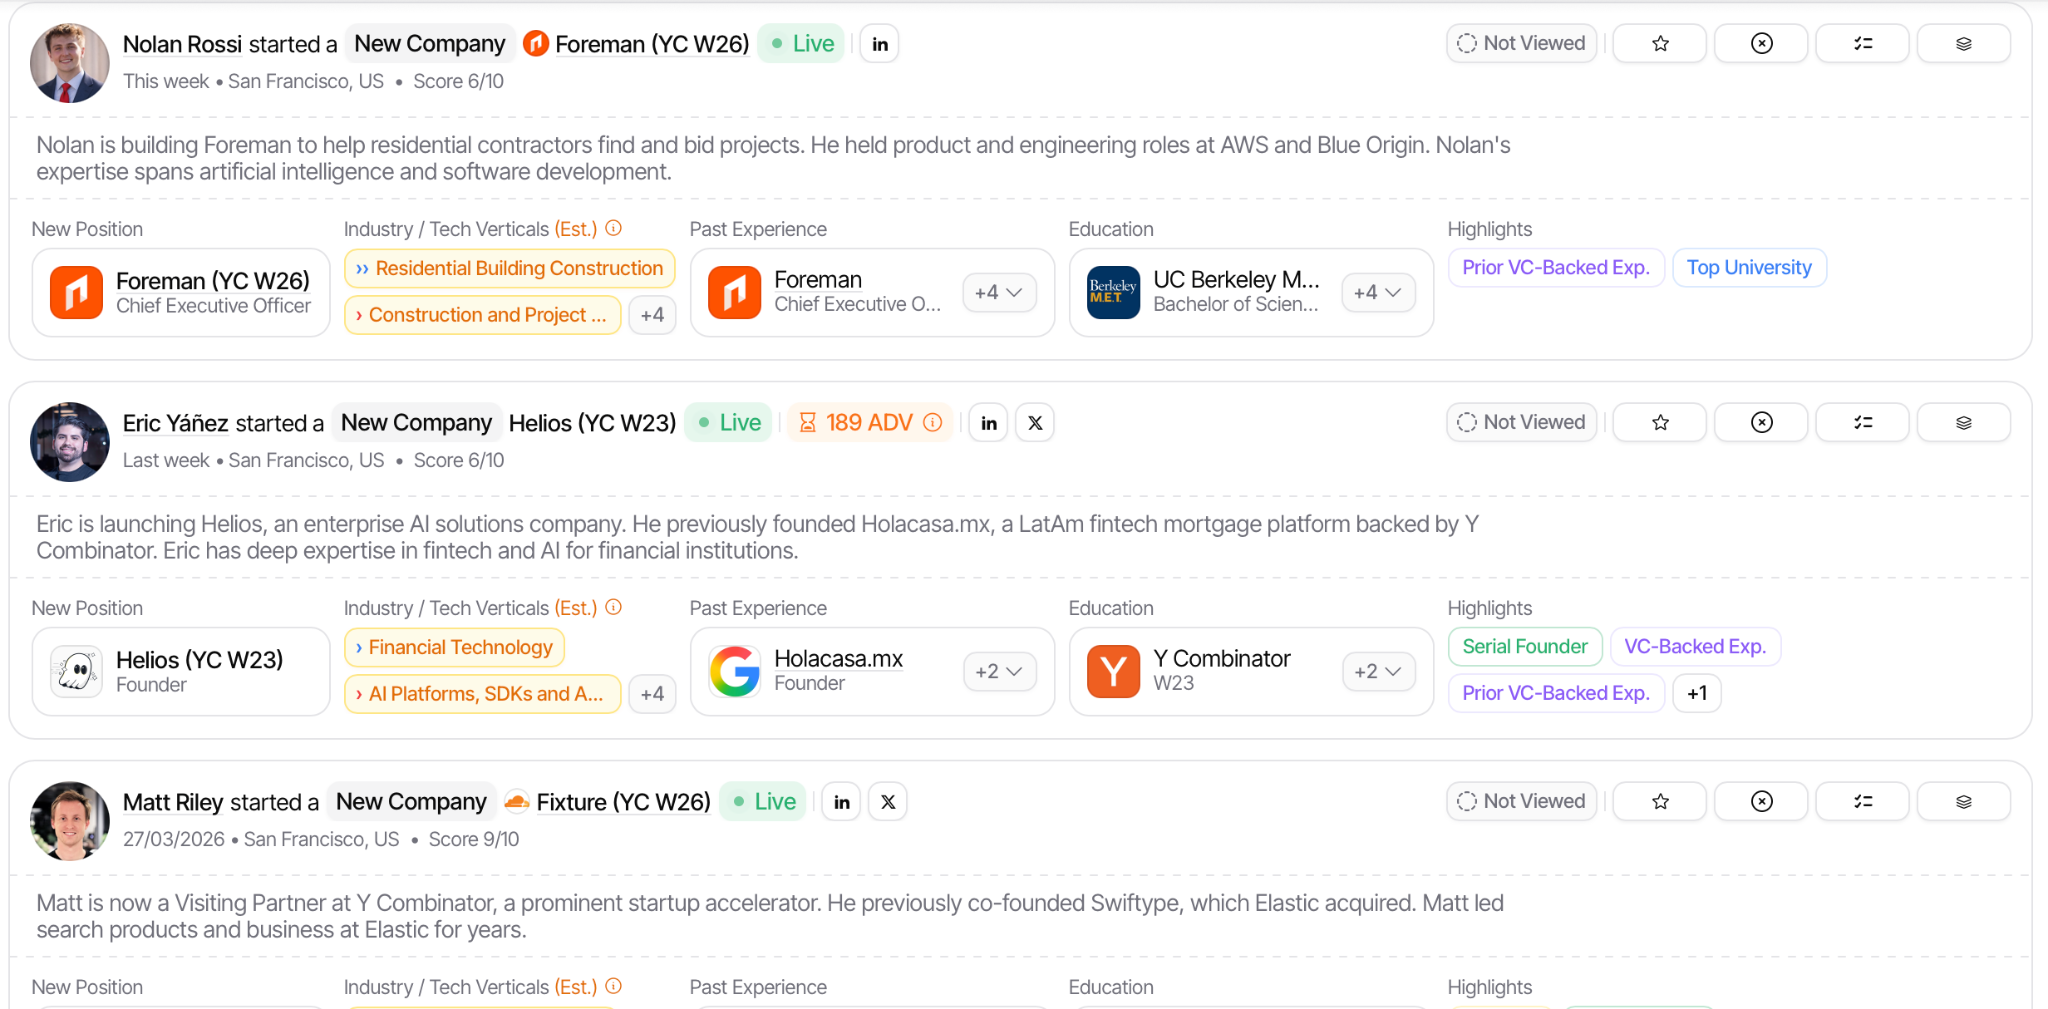
This week we take a look at the most interesting founders just accepted in Y Combinator.
I usually use Spectre to scout for new ideas, the team is great and they also give me a free account once they learned I was a fan of the product. So if you wanna take a look at it, you can find it here.
New funds
I would like to leave this part of the newsletter as space for VC and solo GP that are launching new funds right now. I frequently speak with GPs and LPs, and I like the idea of giving them a showcase where to announce what they are doing. Here the new funds raising right now that I have been talking with:
- Parallax Ventures, a fintech VC fund focused on Latam. They closed Fund I with a strong +50% IRR and 0.7x DPI, and are now raising Fund II. Take a look here if you want to know more or reach out directly to the GP at gennari@parallax.vc for details.
- Founder Factor, VC focused on YC companies, that just closed investments on the latest YC W26. They are expanding the current vehicle to double down on the current batch. Partner is Marco Scotti, you can take a look here if you are interested.
Overall, very interesting to see where the VC ecosystem is heading recently, between new emerging managers, solo GP and micro funds.
Always happy to support if I can under this point of view! If you are raising a fund and you want to be listed here send me a message on Linkedin.
And finally, take also a look at the last edition of the newsletter, Weekly update #127.
Topics
Related funding
| Company | Round | Amount | Date |
|---|---|---|---|
| Smartwage Società Benefit Added · · Weekly update #128 | Pre-seed | 2,000,000 EUR | 17 April 2026 |
| Paxos Labs Added · · Weekly update #128 | Strategic | 12,000,000 USD | 14 April 2026 |
| spektr Added · · Weekly update #128 | Series A | 20,000,000 USD | 16 April 2026 |
| Pillar Added · · Weekly update #128 | Seed | 20,000,000 USD | 15 April 2026 |
| Ralio Added · · Weekly update #128 | 2,500,000 USD | 14 April 2026 | |
| Round Treasury Added · · Weekly update #128 | Seed | 6,000,000 USD | 13 April 2026 |
| Kraken Added · · Weekly update #128 | 200,000,000 USD | 14 April 2026 | |
| Balerion AI Added · · Weekly update #128 | 6,000,000 USD | 17 April 2026 | |
| Astranova Mobility Added · · Weekly update #128 | Series A | 600,000,000 INR | 9 April 2026 |
| Common Wealth Retirement Added · · Weekly update #128 | Series A | 12,000,000 CAD | 13 April 2026 |
| SolvaPay Added · · Weekly update #128 | Pre-seed | 2,400,000 EUR | 15 April 2026 |
| Haast Added · · Weekly update #128 | Series A | 12,000,000 USD | 16 April 2026 |
| SimpleChain Foundation Official Added · · Weekly update #128 | 15,000,000 USD | 13 April 2026 | |
| Zell Added · · Weekly update #128 | Pre-seed | 500,000 EUR | 13 April 2026 |
| Casavo Added · · Weekly update #128 | 12,000,000 EUR | 14 April 2026 | |
| Slash Added · · Weekly update #128 | Series C | 100,000,000 USD | 16 April 2026 |
| wamo Added · · Weekly update #128 | Series A | 10,000,000 EUR | 14 April 2026 |
| Depay Added · · Weekly update #128 | Seed | 4,000,000 USD | 14 April 2026 |
| Brix Added · · Weekly update #128 | 5,500,000 USD | 15 April 2026 | |
| BlockInvest Added · · Weekly update #128 | Strategic | 5,400,000 USD | 15 April 2026 |