Weekly update #126
The latest news from the fintech and VC ecosystems
Welcome to this edition of the weekly newsletter. The idea behind this is to gather all the information in the startup ecosystem in one place, with a special focus on the fintech market and the VC industry.
No episode of Builders has been released this week, but you can always recover the last one where I sit down with Michael Hurup Andersen, CEO and founder of kompasbank. You can find the full episodes here on YouTube, or here on Spotify and here on Apple Podcast and here on Amazon podcast.
Michael is a Danish fintech entrepreneur and seasoned financial markets professional, currently serving as Founder and co-CEO of kompasbank, a Copenhagen based fintech focused on empowering small and midsized enterprises with integrated financial and operational solutions.
Coming from a Master’s degree in Finance from Aarhus University and Mathematical Finance at the University of Oxford, he has over two decades of experience across banking, trading, and advisory, he has held senior roles at institutions including Alvarez & Marsal, where he advised on M&A and private equity transactions, and Deloitte UK, where he led large teams in banking treasury and risk management.
Earlier in his career, he built deep expertise in capital markets at Saxo Bank and Nordea Markets, Corporates & Institutions, specializing in FX options, asset and liability management, and global macro strategies.
Coming back to us, this week I’ve been reading a very interesting report, the “State of Italian VC: tracing evolution and market opportunities” by P101 . The study is a comprehensive analysis on the venture capital landscape in Italy. The report provides an in depth look at the investment patterns, trends and growth dynamics within the Italian VC sector, tracing its developments over the last decade, with a focus on 2025. Here my main takeaways:
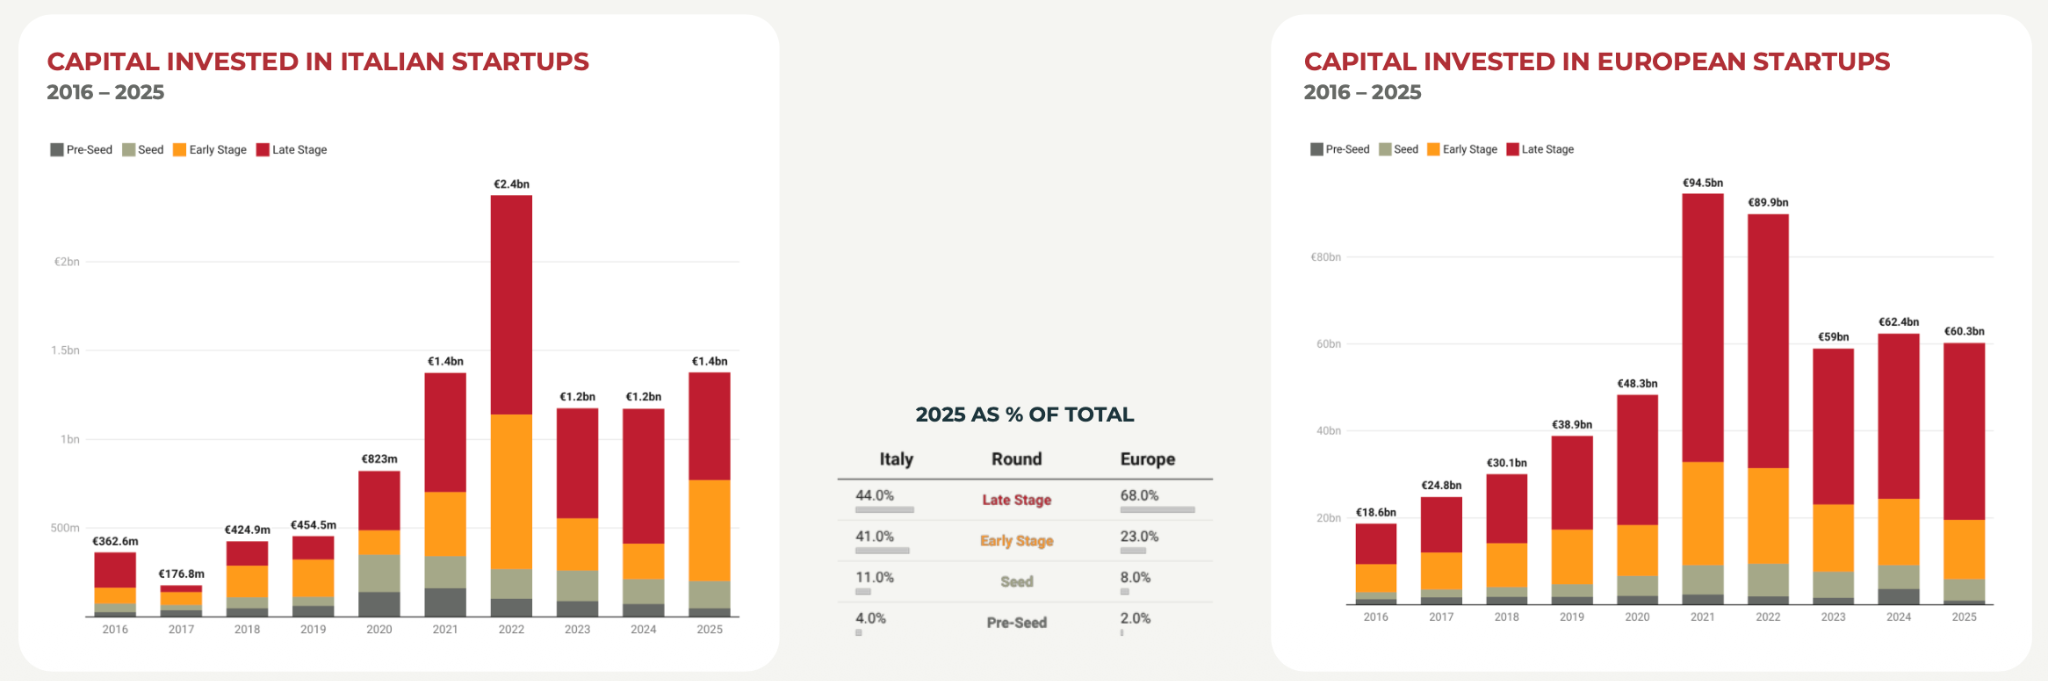
Italy’s venture capital market reached €1.38 billion in 2025, up 17% from 2024, marking a return to growth after two years of decline. The increase was largely driven by a strong rebound in early stage investments, which surged to €568 million, up 186%. In contrast, late stage funding declined 20% to €606 million. Seed investments rose slightly to €155 million, gaining 9%, while pre seed continued to fall, dropping 32% to €48 million.
Across Europe, the VC market contracted by 3% to €60.3 billion following a strong 2024. Late stage remained the largest segment at €40.7 billion, representing 68% of total activity, while early stage and seed investments declined by 11% to €13.6 billion and €4.9 billion respectively. Within this context, Italy outperformed the broader EU market, driven by its early stage recovery despite a smaller ecosystem.
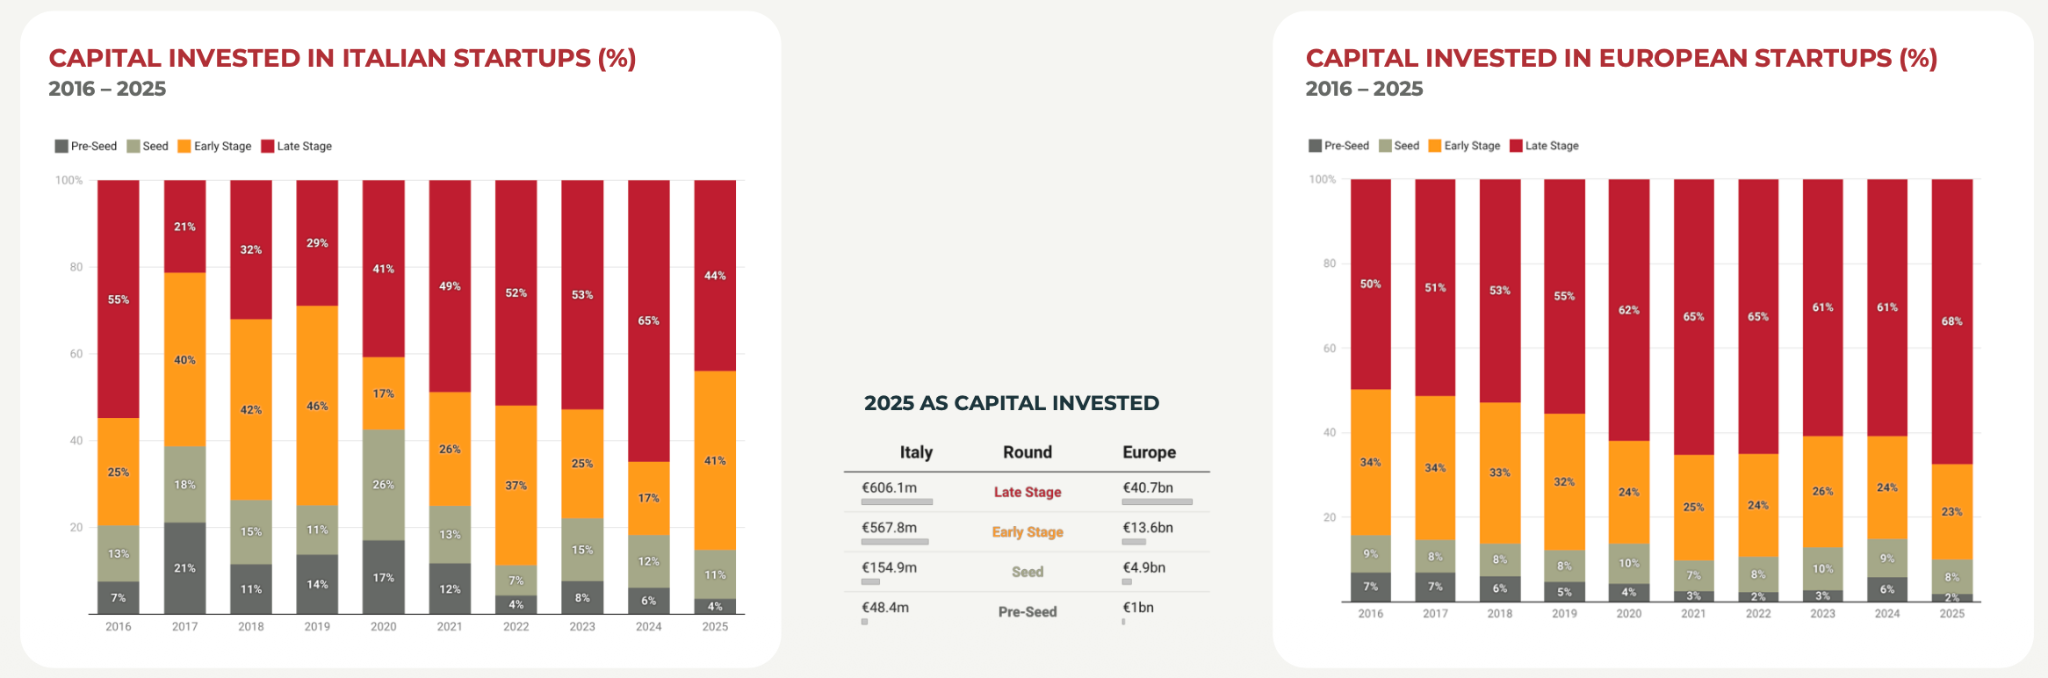
In 2025, Italy’s venture capital market underwent a clear shift toward early stage investments, which accounted for 41% of total capital, up from 17% in 2024. At the same time, late stage funding declined from 65% to 44%. Pre seed and seed represented 4% and 11% respectively, continuing a longer term contraction in the earliest phases. This distribution reflects a return to the 2018–2019 pattern, when early stage played a more central role.
At the European level, capital allocation remained concentrated in late stage deals, which captured 68% of total funding in 2025. Early stage accounted for 23%, while pre seed and seed stood at 2% and 8%. While the EU has maintained a relatively stable structure since 2020, Italy’s repositioning in 2025 points to a stronger focus on earlier growth phases rather than late stage scaling.
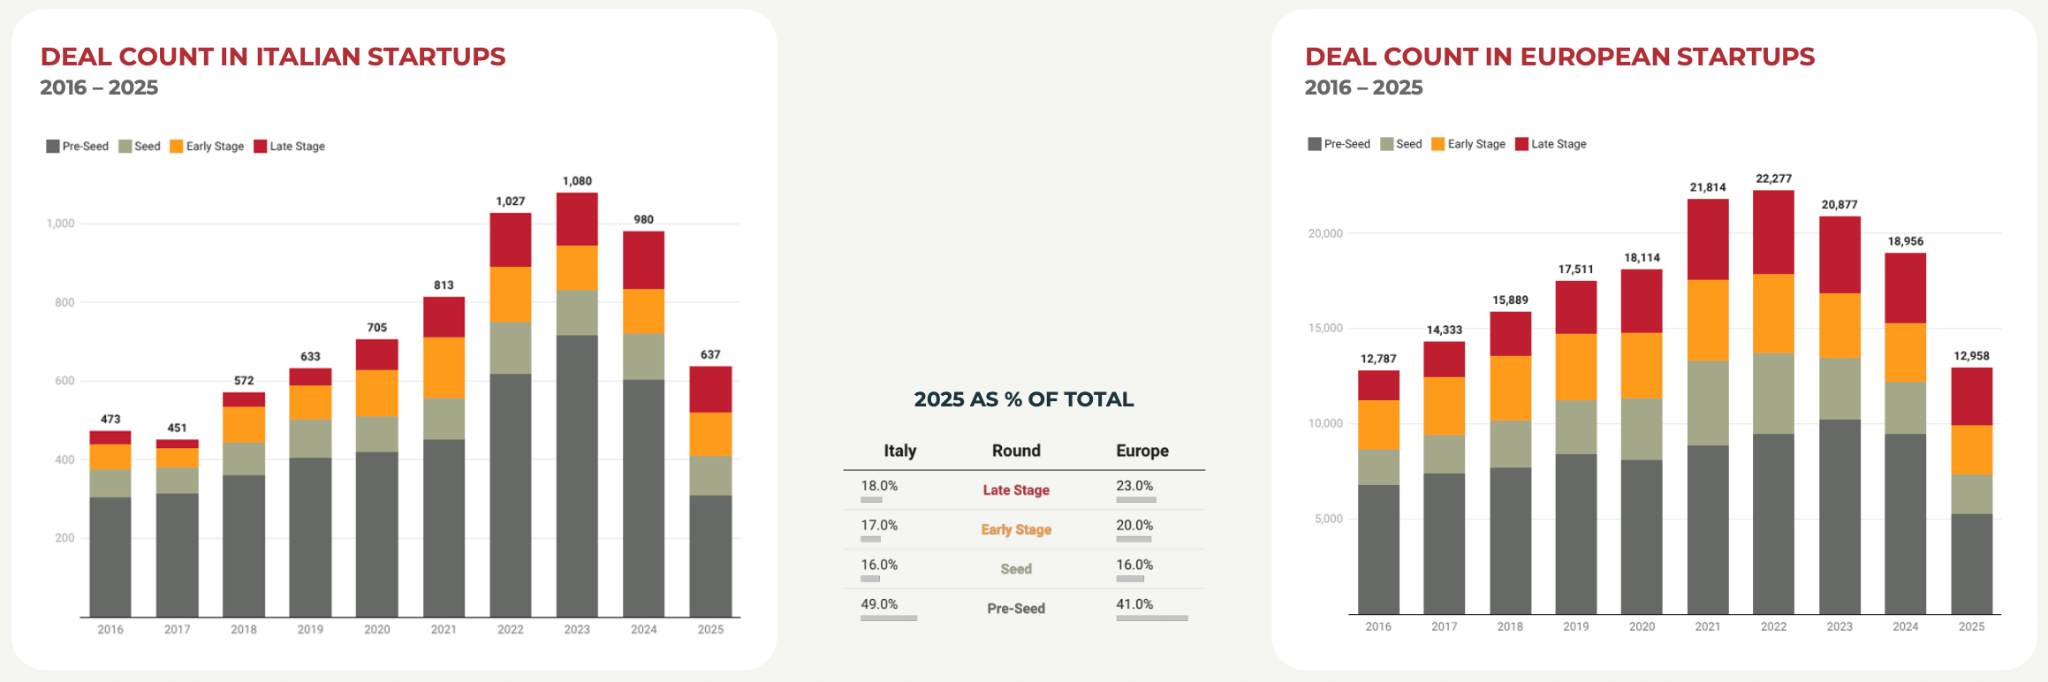
Italy recorded 637 venture capital deals in 2025, down from 980 in 2024, indicating a return to more normalized levels after recent peaks. Pre seed transactions dropped significantly from 603 to 309, while late stage deals declined from 147 to 117. Despite this short term correction, the long term trajectory remains positive, with total deal volume more than doubling from 473 in 2016 to recent highs.
Across Europe, VC activity also slowed, with 12,958 deals in 2025 compared to 18,956 in 2024 and 20,877 in 2023. The decline was largely driven by a reduction in pre seed deals, while late stage activity experienced a more moderate contraction.
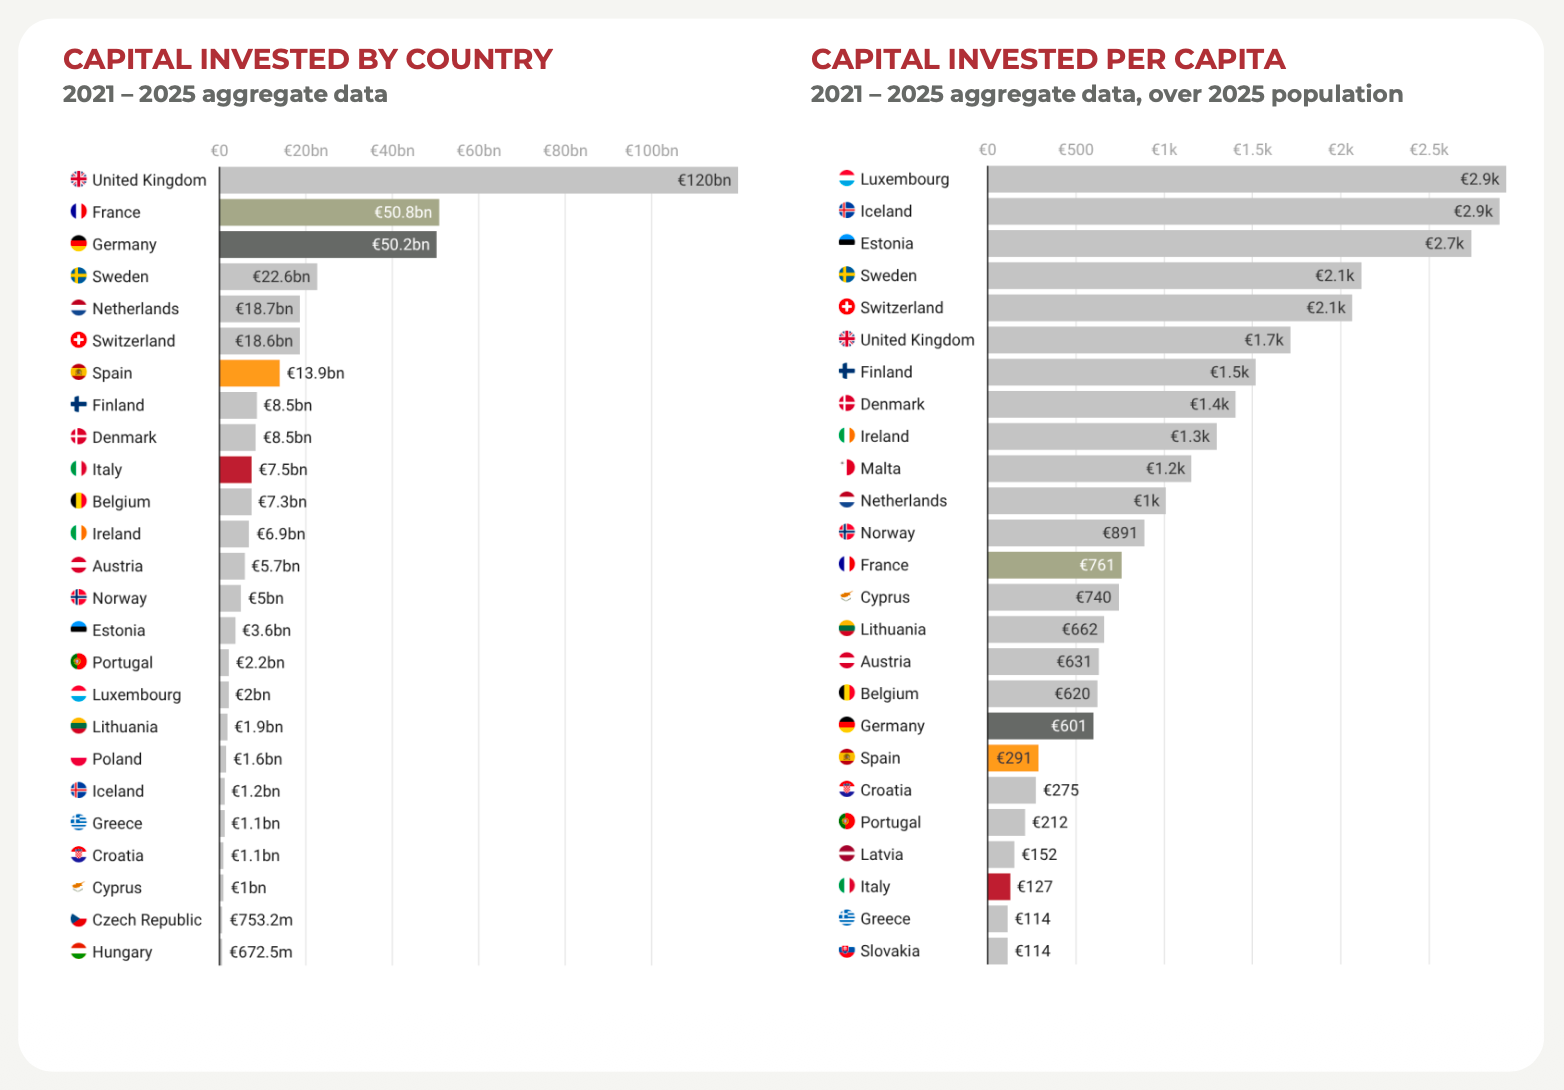
Italy ranks tenth in Europe for total venture capital investment, with €7.5 billion deployed over the past five years. It trails significantly behind leading markets such as the United Kingdom (€120.0 billion), France (€50.8 billion) and Germany (€50.2 billion). Spain also exceeds Italy with €13.9 billion, while smaller ecosystems like Sweden (€22.6 billion) and the Netherlands (€18.7 billion) attract substantially higher volumes relative to their size.
The gap widens on a per capita basis. Italy records €127 of VC investment per inhabitant, placing it among the lowest in Europe. In contrast, Luxembourg (€2,937), Iceland (€2,900) and Estonia (€2,737) show far greater capital intensity, alongside Sweden (€2,115), Switzerland (€2,066) and the United Kingdom (€1,715).
This disparity reflects a structural imbalance between market size and investment depth. Despite its scale, Italy remains undercapitalised, with France (€761 per capita) and Germany (€601) investing around five times more per inhabitant.
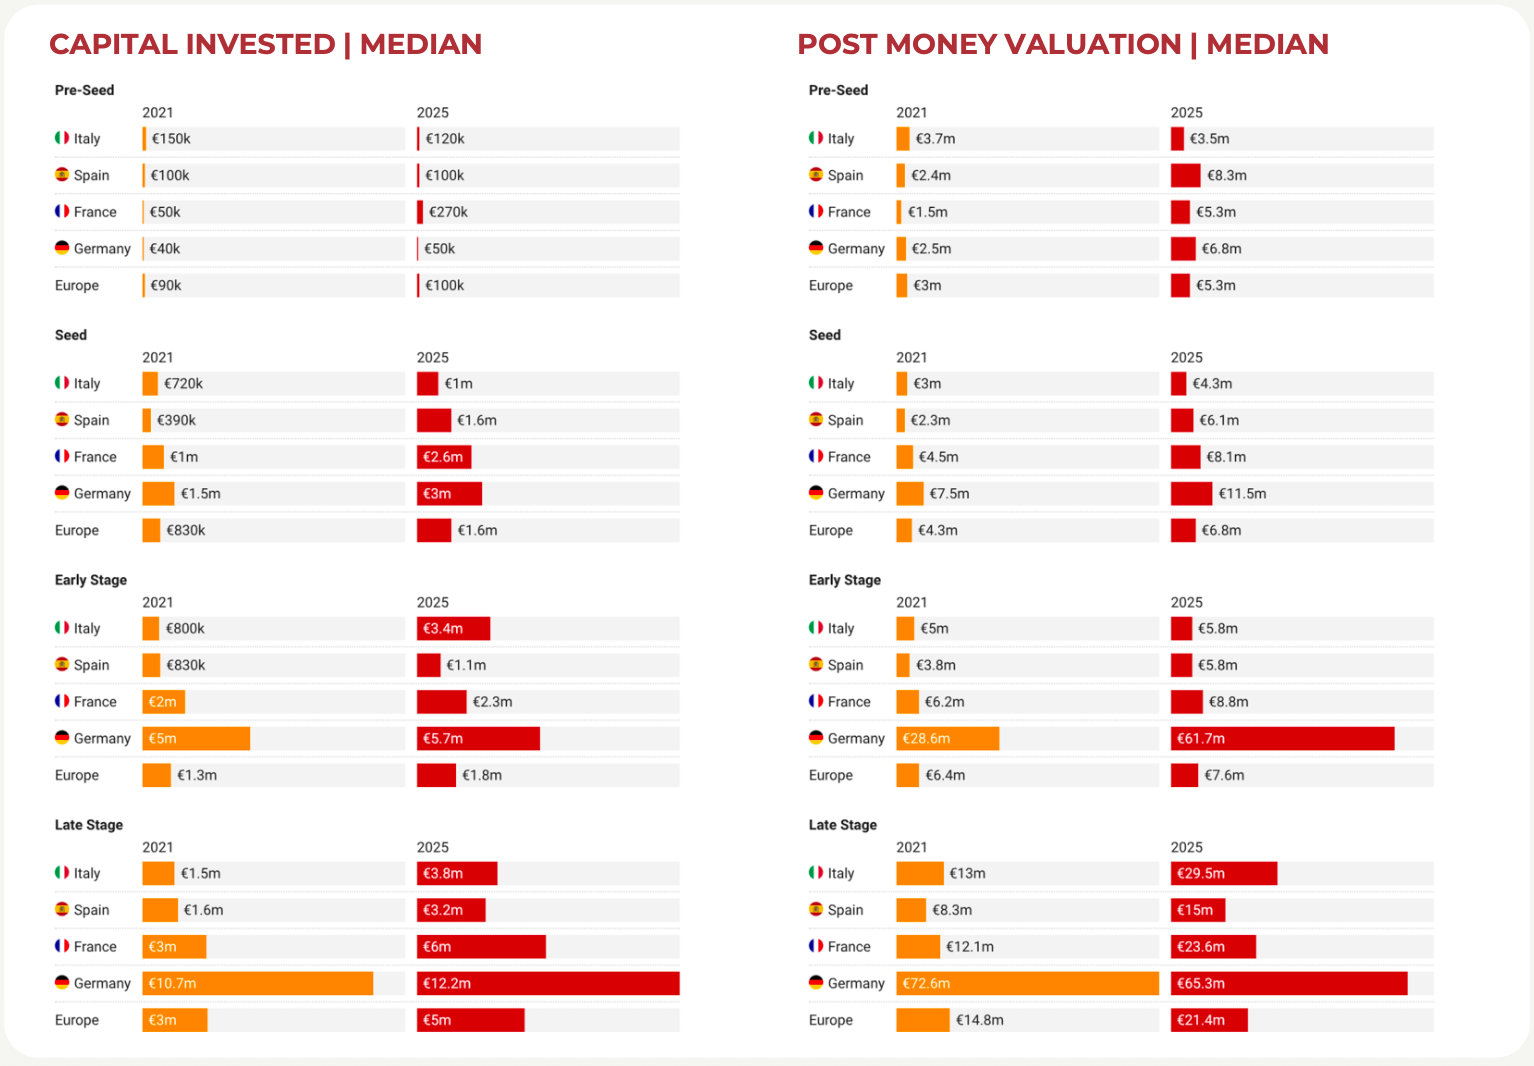
Between 2021 and 2025, Italy recorded a significant increase in median capital invested across most stages, particularly along the growth pipeline. Early stage rounds rose from €800k to €3.4 million, representing the strongest expansion, while late stage rounds increased from €1.5 million to €3.8 million. Seed rounds grew from €720k to €1 million, still below the European median of €1.6 million, while pre-seed declined slightly from €150k to €120k, remaining close to Europe’s €100k.
Valuations also improved, especially at later stages. In 2025, median valuations reached €3.5 million at pre seed, €4.3 million at seed, €5.8 million at early stage, and €29.5 million at late stage, more than doubling from €13 million in 2021. Despite this progress, Italy remains below European benchmarks and behind France and Germany.
But let’s take a closer look at the main news of the last seven days. X presented a Visa metal card with 6% APY and 3% cashback, Monzo Bank just came out of the US market to focus on EU, Kraken launched “Embed” to bring crypto to banks and fintechs and OpenAI closed the biggest private round in history, with $122B. But also, LALIGA partners with Polymarket to bring predictions to soccer fans in North America, Klarna’s dutch users won’t need to pay them back, and Revolut got fined $13M in Italy. Lot of movement in the VC market, mostly in the UK! A $200M VC fund from British Business Bank backed by UK pension funds, a $100M biotech fund from Ysios Capital and a $50M fund from Future Wealth Investments. But also Women backing Women, Gateway Capital, Runway and many others. And finally, some very interesting funding rounds from fintech startups like Ume, Midas, Keyrock, 9fin, Brickken, Better Money, Kulipa and many others.
Let’s take a closer look:
Rounds
- Ume secures $28.5M credit fund to scale retail financing model in Brazil
- Midas raises $50M Series A to advance tokenized investment infrastructure
- UNCIA raises $3M to scale AI lending infrastructure across global markets
- Valinor raises $25M to bring private credit on chain
- Keyrock becomes EU latest unicorn, reaching $1.1B valuation in Series C Led by SC Ventures
- 4G Capital raises $2M to scale SME lending across East Africa
- 9fin reaches $1.3B valuation with $170M raise to modernise debt capital markets
- OpenFX raises $94M to build stablecoin powered FX infrastructure at scale
- Skillsvest raises ₹5.5Cr pre seed to scale income linked student financing
- Brickken raises €3M to scale tokenisation infrastructure for institutional markets
- OpenAI just raised the largest private round in history, securing $122B
- Bachatt raises $12M Series A led by Accel to build fintech solutions for India’s 300M merchants market
- Better Money raises $10M to build regulated stablecoin clearing infrastructure
- Financial News Systems raises €1.5M to build AI driven newsroom for investors
- Latitude raises $8M to scale stablecoin powered cross border payments
- Kulipa secures $6.2M to bridge stablecoins and card payments
- blanco raises $1.7M to build AI native factoring and digital banking for SMEs
- Cross River raises $50M to accelerate AI driven embedded finance and crypto expansion
- V1C raises KRW 13.4B to expand AI driven B2B fintech platform
- Cifrato (YC W25) raises $1M+ seed to scale AI powered accounting automation in Latin America
VC funds
- Ysios Capital launches €100M InceptionBio fund to accelerate biotech creation in Spain
- Empirical Ventures secures £10M to back UK deeptech “Venture Scientists”
- Future Wealth Investments launches $50M fund to back early stage founders
- UK pension funds commit £200M to VC fund from British Business Bank as Wayve secures first £8M investment
- Runway launches $10M fund to back next generation AI applications
- UK’s “Women Backing Women” fund reaches £130M first close to tackle gender funding gap
- Gateway Capital Partners launches $25M Fund II to back midwest innovation
News on the market
- X launches metal Visa card offering 6% APY and 3% cashback
- Wise expands into everyday banking with UK deposit accounts offering 3.26% interest
- Zopa Bank explores Northern Europe expansion through potential acquisition
- Nium bridges stablecoins and global payments with dual network card issuance platform
- Checkout.com reports 71% TPV growth in APAC as enterprise demand accelerates
- Kalshi moves into margin trading after securing institutional license
- Monzo Bank exits US market to refocus on European expansion strategy
- TikTok moves into fintech with a payment and credit license request in Brazil
- Kraken launches “Embed” to bring crypto trading to banks and fintechs
- REPAY - Realtime Electronic Payments to acquire KUBRA for $372M to scale consumer bill payments platform
- slice expands UPI linked credit card to all users, targeting India’s 300M UPI base
- Kraken’s Krak app launches metal card, 2% cashback, and travel concierge
- Italy fines Revolut €11.5M over transparency and account practices
- Visa and Ramp introduce agentic AI to automate corporate payments
- LALIGA partners with Polymarket to bring prediction markets to North American fans
- BLIK expands into EU eCommerce, unlocking cross border payments for 21M users
And here some useful resources for everyone involved in the ecosystem:
Events you don’t want to miss
- FIBE | Berlin - 15th-16th April 2026 (Link here)
- Stablecon EMEA | Amsterdam - 19th-20th May (Link here)
You have a cool event you want to mention or to sponsor? Feel free to send me a DM.
Founders to watch in fintech
I also wanted to start shining a light on the most interesting fintech founders out there, so I thought to start sharing how I look for ideas to invest on. Every week, I will start sharing the most interesting founders in fintech, divided per area.
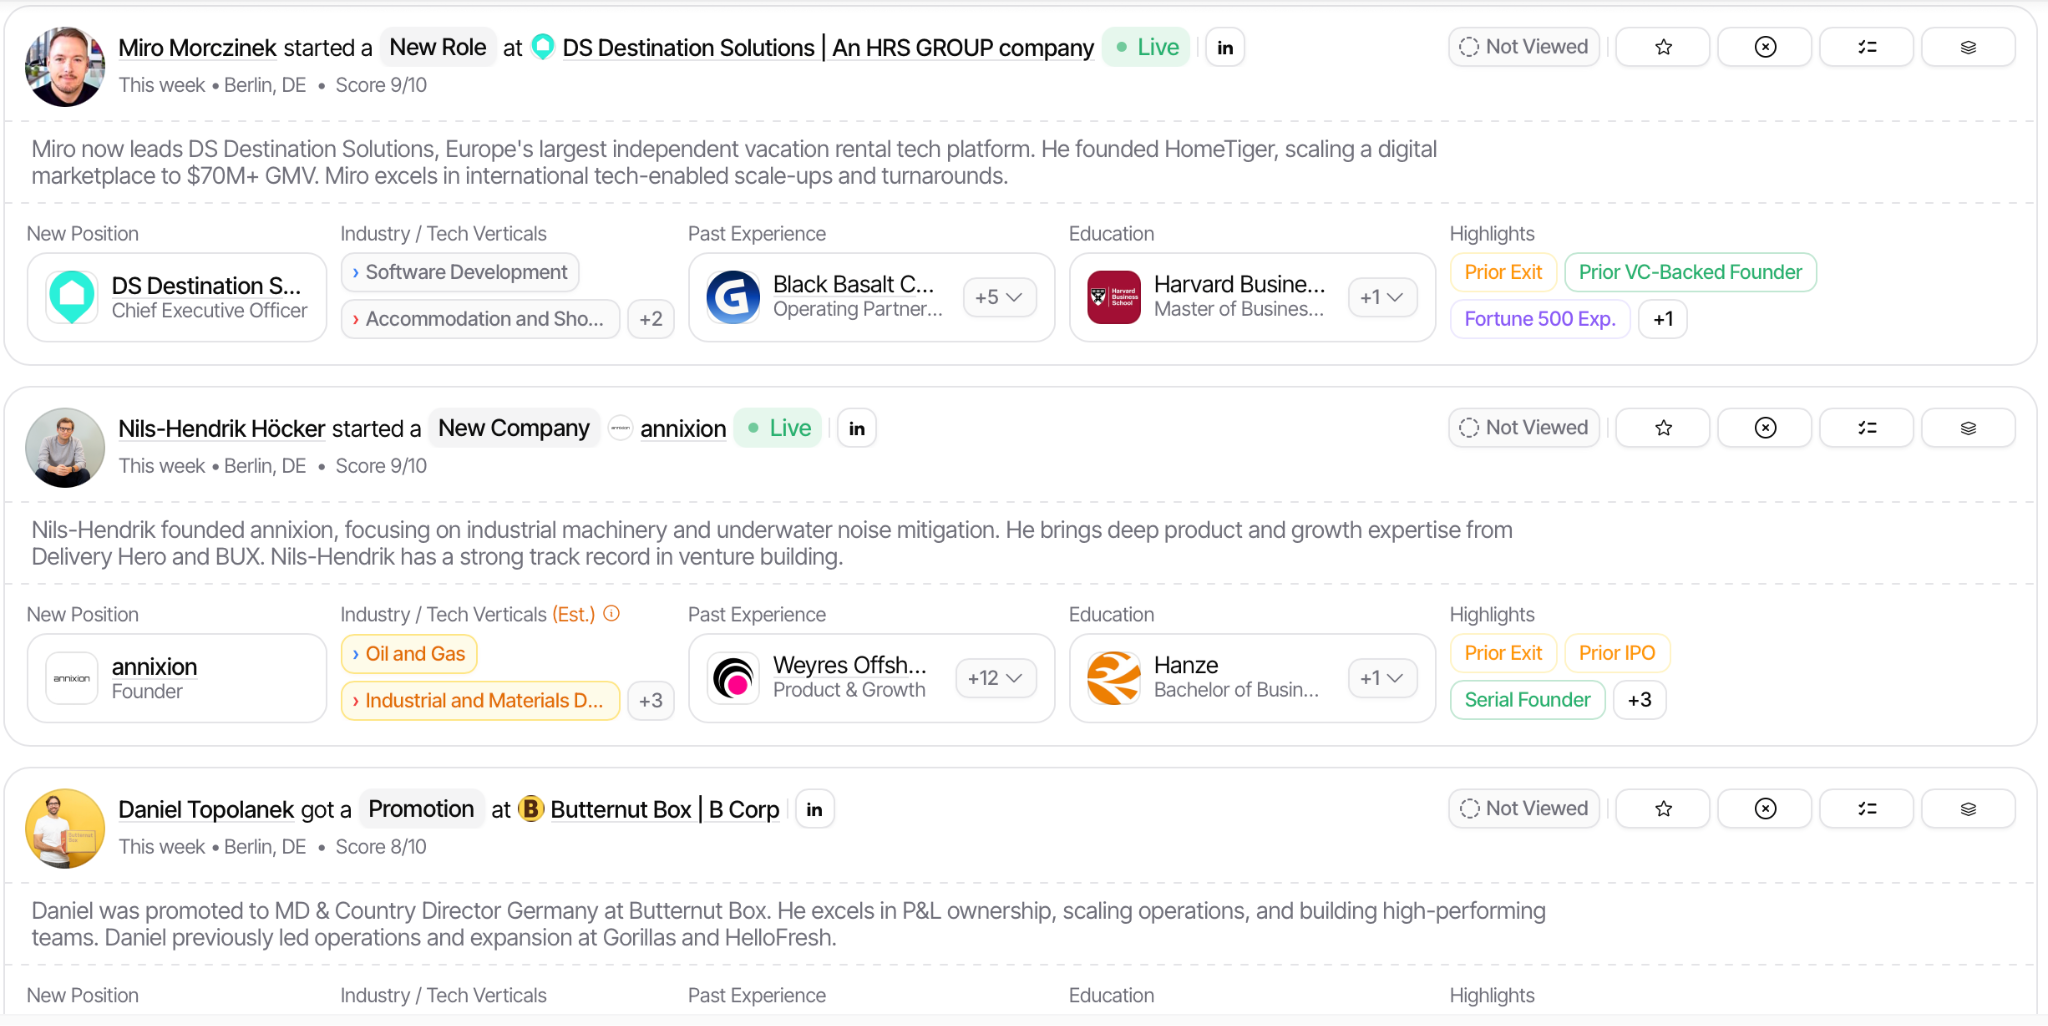
This week we take a look at the most interesting founders with fintech experience in Berlin.
I usually use Spectre to scout for new ideas, the team is great and they also give me a free account once they learned I was a fan of the product. So if you wanna take a look at it, you can find it here.
New funds
I recently spoke with Marco Scotti from Raspberry Ventures. Thanks to their Y Combinator Alumni network, they unlock access to the top 10% of YC companies for Angel investors. Co-investing up to $3M across 15 - 25 companies in each YC batch, 4 batches a year, before Demo Day; and before the Silicon Valley VCs come in and take allocations in the best companies.
Their next batch YC W26m is closing in the upcoming weeks. You can take a look here if you are interested!
Take also a look at the last edition of the newsletter, Weekly update #125.
Topics
Related funding
| Company | Round | Amount | Date |
|---|---|---|---|
| 9fin Added · · Weekly update #126 | Series C | 170,000,000 USD | 31 March 2026 |
| OpenAI Added · · Weekly update #126 | 122,000,000,000 USD | 1 April 2026 | |
| Cifrato Added · · Weekly update #126 | Seed | 1,000,000 USD | 3 April 2026 |
| Brickken Added · · Weekly update #126 | Pre-Series A | 3,000,000 EUR | 31 March 2026 |
| UNCIA Added · · Weekly update #126 | 3,000,000 USD | 27 March 2026 | |
| Cross River Added · · Weekly update #126 | Growth | 50,000,000 USD | 31 March 2026 |
| 4G Capital Added · · Weekly update #126 | Loan | 2,000,000 USD | 27 March 2026 |
| Skillsvest Added · · Weekly update #126 | Pre-seed | 55,000,000 INR | 31 March 2026 |
| Bachatt Added · · Weekly update #126 | Series A | 12,000,000 USD | 1 April 2026 |
| OpenFX Added · · Weekly update #126 | Series A | 94,000,000 USD | 31 March 2026 |
| Latitude Added · · Weekly update #126 | Seed | 8,000,000 USD | 31 March 2026 |
| blanco Added · · Weekly update #126 | Equity crowdfunding | 2,000,000 USD | 30 March 2026 |
| Kulipa Added · · Weekly update #126 | Seed | 6,200,000 USD | 2 April 2026 |
| Financial News Systems Added · · Weekly update #126 | Pre-seed | 1,500,000 EUR | 31 March 2026 |
| V1C Added · · Weekly update #126 | 13,400,000,000 KRW | 2 April 2026 | |
| Midas (tokenization) Added · · Weekly update #126 | Series A | 50,000,000 USD | 30 March 2026 |
| Better Money Added · · Weekly update #126 | Seed | 10,000,000 USD | 31 March 2026 |
| Valinor Added · · Weekly update #126 | Seed | 25,000,000 USD | 30 March 2026 |