Weekly update #112
The latest news from the fintech and VC ecosystem
Welcome to this edition of the weekly newsletter. The idea behind this is to gather all the information in the startup ecosystem in one place, with a special focus on the fintech market and the VC industry.
Builders is back with Season 3! In this episode, I sit down with Nik Talreja, CEO and founder at Sydecar. You can find the full episode here on YouTube, or here on Spotify and here on Apple Podcast.
Nik doesn’t come from the usual bankers/financial institution background. He started as a lawyer in New York, working at firms like Olshan Frome Wolosky LLP and Weil, Gotshal & Manges LLP. He discovered startup pretty quickly, working with founders on term sheet and funding round, so he decided to move to Palo Alto.
In California he started working at Cooley LLP as a lawyer again, but the entrepreneurial vocation was too strong. He joined Talis Capital partner as a co-founder, where he wanted to use his experience as a lawyer first hand, managing his studio, then to Spiral Therapeutics , changing industry entirely, as director of finance operations.
Finally, he founded Sydecar, coming from years of experience in angel investments and rounds in startups. Sydecar makes it simple and efficient for venture fund and syndicate managers to form Special Purpose Vehicles (SPVs) and funds by automating banking, compliance, contracts and reporting. Founded in 2021, Sydecar is on a mission to build the infrastructure that powers private markets.
With him, we will talk about the two faces of the US startup ecosystem, comparing Silicon Valley to New York, but also his business angel experience, the set up of startups in Texas and his experience raising funds for startups and VC.
This was also the last episode of Season 3 for Builders! The podcast will come back in January with more entrepreneurs and investors in the fintech field. Get in touch with me if you wanna suggest someone or if you want to be part of the show!
Coming back to us, I’ve been reading a very interesting study this week, the “2025 M&A report” from Boston Consulting Group (BCG). The Report takes in consideration current M&A activity—globally and regionally. It then explores how periods of uncertainty present opportunities for dealmakers who possess the capabilities to pursue targeted acquisitions and disciplined geographic expansions, considering how companies can create value from cross-border transactions by navigating regional complexities, regulatory challenges, and cultural integration. Here my main takeaways:
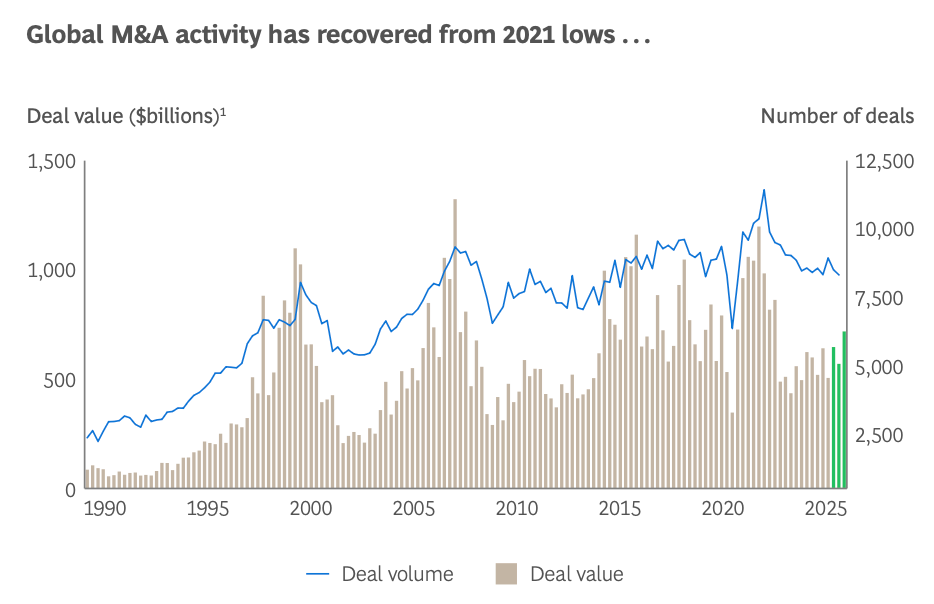
The global M&A market is showing resilience, with aggregate deal value up 10% year over year in the first nine months of 2025 despite geopolitical and tariff headwinds. Activity has concentrated on regionally focused small- and mid-cap deals and on transactions driven by strategic growth and capability building. North America led by value, with technology the most active sector. Megadeals rebounded to 27 transactions of $10 billion or more, up from 21 in 2024, though below the 40 seen in 2021. Large deals above $500 million remain subdued, SPACs are marginal, and private equity deal value rose 38% year to date, led by technology, industrials, and energy.
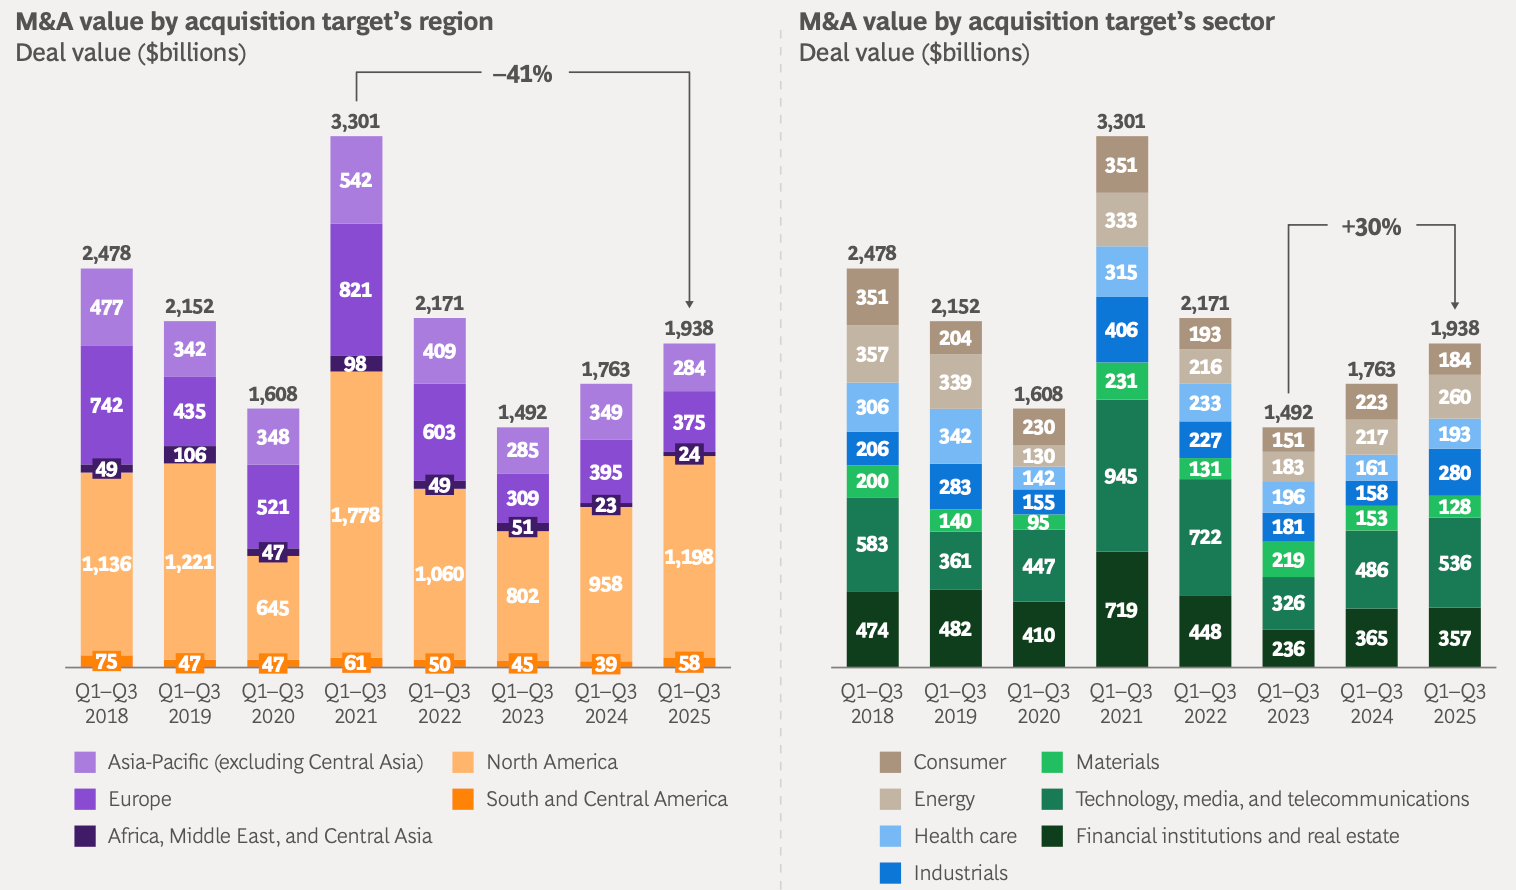
The Americas led global M&A over the first nine months of 2025, with deal value reaching $1.26 trillion, up 26% year over year. North America accounted for $1.20 trillion, or 62% of global activity, with Canada rising 96% and South and Central America up 47%. Asia-Pacific declined 19% to a ten-year low of $284 billion, despite gains in Singapore (38%), mainland China (11%), and Australia (1%), offset by sharp drops in Hong Kong (–73%), India (–20%), and South Korea (–13%). European M&A totaled $375 billion, down 5%, with strong growth in the Netherlands (263%), Switzerland (109%), Germany (45%), Italy (28%), and the Nordics (31%).
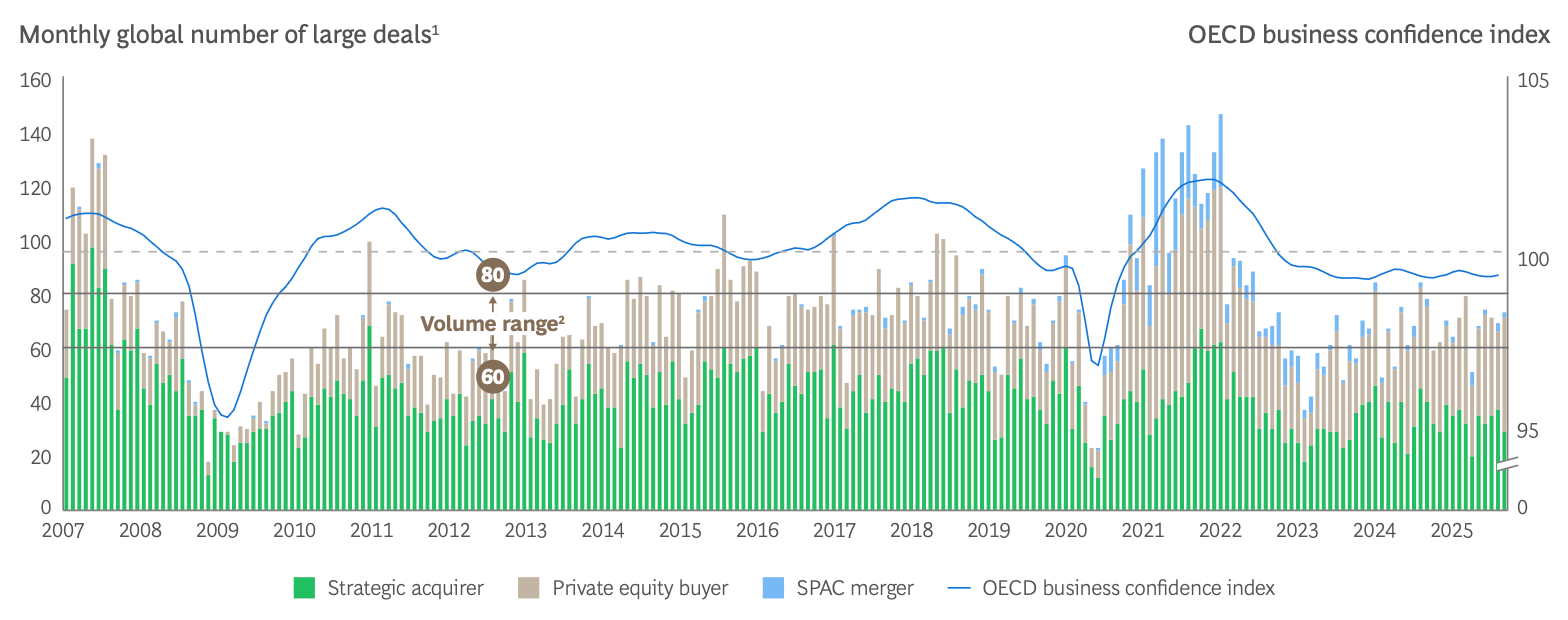
Private equity firms hold roughly $2 trillion in dry powder as of early October 2025, sustaining pressure to deploy capital despite global fundraising slowing sharply from the 2021 peak. Venture capital funding rose about 36% year over year in the first nine months of 2025, according to Crunchbase, though levels remain below 2021–2022 highs, with AI attracting the largest rounds despite valuation concerns. BCG’s M&A Sentiment Index points to stronger momentum in technology and energy, weaker in industrials and consumers. Stabilizing interest rates, recovering valuations, and strong corporate balance sheets support activity, while delayed divestitures, paused large deals, and a backlog of IPOs signal significant pent-up demand and supply.
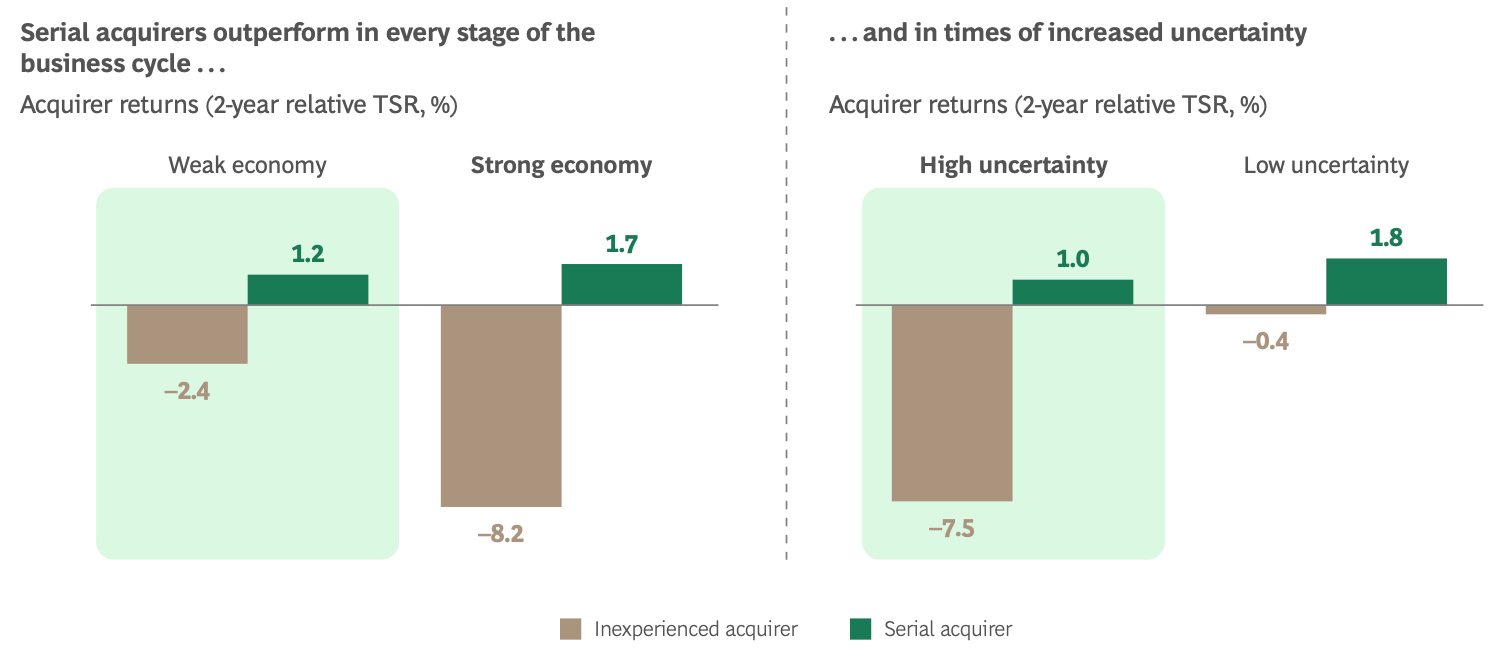
Experienced dealmakers consistently outperform peers by treating volatility as an opportunity rather than a constraint. BCG data shows serial acquirers generate higher two-year relative TSR in weak economies (1.2% vs –8.2%), strong economies (1.7% vs –7.5%), and high-uncertainty periods (1.0% vs –2.4%). Success increasingly depends on integrating M&A into core strategy, using flexible deal structures, rigorous scenario planning, and advanced AI tools to accelerate due diligence and uncover value. With technological disruption, supply-chain risk, and sustainability pressures rising, acquisitions and divestitures are becoming central to long-term transformation, resilience, and sustained shareholder value creation.
Anyway we saw a lot of interesting news this week. Ripple secures OCC approval to launch a national trust bank, Revolut expands in Spain with new offices in Madrid and Barcelona, Aspire secures an EMI license, Lovable closes a crazy $330M round and Trade Republic secures a $12B valuation in a $1.2B secondary deal. But also, Monzo Bank acquires Habito, PayPal launches a banking license application in Utah, Revolut launches mobile plans in UK and Poland, and Deutsche Bank integrates with Wero. Lots of movements in the VC ecosystems, with new funds from Kibo Ventures, Swish Ventures, Lightspeed, but also Radical Partners, Fortino Capital and Cloudberry VC . And finally, some very interesting funding rounds from fintech startups like Esusu, Olea, LI.FI, Imprint, Givefront, RedotPay and many others.
But let’s take a closer look at the main news of the last seven days.
Rounds
- LI.FI raises $29M to scale cross-blockchain price discovery and routing
- Wealthfront raises $486M in Nasdaq IPO at $2B valuation
- Esusu raises $50M Series C at $1.2B valuation to expand rent-based credit building
- Octane® raises $100M Series F to accelerate fintech expansion
- PolyAI raises $86M Series D to scale enterprise voice AI
- Lovable reaches $6.6B valuation as Accel backs Europe’s no-code AI champion
- RedotPay raises $107M Series B as stablecoin payments scale globally
- Sequence raises $20M Series A to automate revenue operations with AI agents
- Tether.io backs lightning-native payments with $8M investment in Speed⚡️
- Olea raises $30M Series A led by BBVA to scale digital trade finance
- Thread Bank raises $30.5M to scale embedded banking platform nationwide
- Diligent Capital Partners leads $12M investment in Philippine neobank Tonik
- Imprint raises $150M Series D at $1.2B valuation to redefine brand loyalty
- Was in the air, but now is official: Lovable raises $330M at $6.6B valuation
- Plata Card secures up to $500M backing as it prepares full banking launch in mexico
- HashKey Group raises $207M in Hong Kong IPO as crypto listings rebound
- Givefront raises $2M to modernize financial infrastructure for U.S. nonprofits
VC funds
- Kibo Ventures secures €80M first close for Fund IV, targets pan-European expansion
- Omri Casspi expands Swish Ventures with $100M opportunity fund
- Lightspeed Venture Partners raises record $9B to double down on AI
- Former SV Angel partner Beth Turner launches $45M solo fund Valkyrie
- Radical Partners launches Italy’s first fully independent VC Fund-of-Funds
- PSV Hafnium closes €60M fund to scale nordic university spinouts
- Fortino Capital raises €700M to scale Europe’s next B2B SaaS leaders
- Startuplab closes €32m Fund V to scale Norway’s next generation of tech founders
- Neil S W Murray closes $6M Fund III to back early-stage Nordic founders
- Cloudberry VC closes a €30M VC fund to back semiconductors in Europe
News on the market
- Nexo acquires Buenbit to establish a Latin America hub in Buenos Aires
- Last week, Tether.io proposed a €1.1B bid for Juventus Football Club, Agnelli family rejects it, at least for now
- BaFin imposes tighter oversight on N26 after compliance failures
- Ripple secures OCC approval to Llaunch US National Trust Bank
- Mastercard and TerraPay partner to expand global acceptance for digital wallets
- Monzo Bank acquires Habito to make mortgages a core banking product
- Revolut enters UK and Poland telecom market with unlimited 5G mobile plans
- Aspire secures EU EMI license and launches European hub in the Netherlands
- Trade Republic reaches €12.5B valuation in €1.2B secondary transaction
- Visa launches global stablecoins advisory practice as market tops $250B
- PayPal moves toward banking license with industrial bank application in Utah
- Deutsche Bank goes live With Wero, expanding european instant payments
- Google enters India’s credit card market with UPI-linked flex card
- Revolut expands spanish footprint with new Madrid and Barcelona offices and 800 planned hires
Italian market
- -
And here some useful resources for everyone involved in the ecosystem:
Events you don’t want to miss
- FIBE | Berlin - 15th-16th April 2026 (Link here)
You have a cool event you want to mention or to sponsor? Feel free to send me a DM.
New funds
I recently spoke with Marco Scotti from Raspberry Ventures. Thanks to their Y Combinator Alumni network, they unlock access to the top 10% of YC companies for Angel investors. Co-investing up to $3M across 15 - 25 companies in each YC batch, 4 batches a year, before Demo Day; and before the Silicon Valley VCs come in and take allocations in the best companies.
Their next batch YC W26m is closing February 1st, 2026. You can take a look here if you are interested!
Take also a look at the last edition of the newsletter, Weekly update #111.
Topics
Related funding
| Company | Round | Amount | Date |
|---|---|---|---|
| Tonik Added · · Weekly update #112 | 12,000,000 USD | 18 December 2025 | |
| Plata Card Added · · Weekly update #112 | 500,000,000 USD | 18 December 2025 | |
| Sequence Added · · Weekly update #112 | Series A | 20,000,000 USD | 16 December 2025 |
| RedotPay Added · · Weekly update #112 | Series B | 107,000,000 USD | 16 December 2025 |
| Esusu Added · · Weekly update #112 | Series C | 50,000,000 USD | 11 December 2025 |
| Olea Added · · Weekly update #112 | Series A | 30,000,000 USD | 17 December 2025 |
| Thread Bank Added · · Weekly update #112 | 30,500,000 USD | 15 December 2025 | |
| Octane Added · · Weekly update #112 | Series F | 100,000,000 USD | 15 December 2025 |
| LI.FI Added · · Weekly update #112 | Series A extension | 29,000,000 USD | 11 December 2025 |
| PolyAI Added · · Weekly update #112 | Series D | 86,000,000 USD | 16 December 2025 |
| Lovable Added · · Weekly update #112 | 17 December 2025 | ||
| Lovable Added · · Weekly update #112 | 330,000,000 USD | 18 December 2025 | |
| Imprint Added · · Weekly update #112 | Series D | 150,000,000 USD | 17 December 2025 |
| Givefront Added · · Weekly update #112 | Seed | 2,000,000 USD | 18 December 2025 |