Weekly update #152
Before the news of the week, a small announce from my side:
Before the news of the week, a small announce from my side:
Weekly update is now Builders in Fintech
After 151 issues, this newsletter, the podcast and everything around them now live under one name: Builders in Fintech. Same weekly update, same Monday slot, but now with a home: [buildersinfintech.ai](http://buildersinfintech.ai/).
Behind it is the database I’ve been building from every issue since November 2023. Here’s what’s live:
- 2,400+ fintech funding rounds, each sourced and editorially reviewed, with investors, lead flags and amounts in the currency announced.
- The Builders Fintech Funding Index: a weekly read on fintech deal activity against its 12-week average. This week: 215.
- Investor scorecards: how often an investor backs the same company again within 24 months.
- Podcast knowledge: all 53 episodes turned into summaries, timestamped facts and Q&A. You can search what founders and VCs actually said and jump to the moment on YouTube.
- The Embargo Desk for founders and PR teams: send announcements under embargo and they publish on time.
One more thing. The whole database is open to AI assistants through a free MCP server: no key, 19 tools, listed in the official MCP Registry. Connect it to Claude or any MCP client and ask things like “Which investors were most active in European payments rounds this year?” Details at buildersinfintech.ai/for-agents. The data is also free to download (CC BY 4.0) on GitHub, Hugging Face and Zenodo.
Thank you for reading, 151 issues in. Builders in Fintech is still the same newsletter, now with more around it. Now, back to the news.
Stripe agreed to acquire Parafin, Kalshi Agarwal is in talks to raise about $1B at a $40B valuation, and Valley National is paying $340M for Bluevine. Below: The latest episode of the podcast with Nika Kurdiani from TBC Uzbekistan and McKinsey & Company report on wallet adoption, a survey of 300+ corporates, investors and sponsors on the 12–25% of banking wallet that changes hands every year, the week’s rounds and funds, and three managers raising now.
The podcast: Episode #53 aired last Tuesday: my guest was Nika Kurdiani, CEO of TBC Uzbekistan. You can take a look at it here on LinkedIn or here on Substack, full episode here on YouTube and here on Spotify.
All episodes: YouTube · Spotify · Apple Podcasts · Amazon. Founders and VCs who want to come on the show: message me on LinkedIn.
Lisbon, 6–8 October. I’ll be speaking at Fintech Meetup Europe, the first European edition of the meetings first event, at FIL in Lisbon next week. If you are there, message me on LinkedIn and let’s find a slot.
The report: the 12–25% of banking wallet that moves every year
McKinsey & Company, Anchor or drift: What it takes to capture wallet share in 2026. The 2026 CIB Voice of the Customer Survey draws on more than 300 corporations, institutional investors and financial sponsors, plus C-suite interviews, on how they split business among banks and nonbanks. Here my main takeaways:
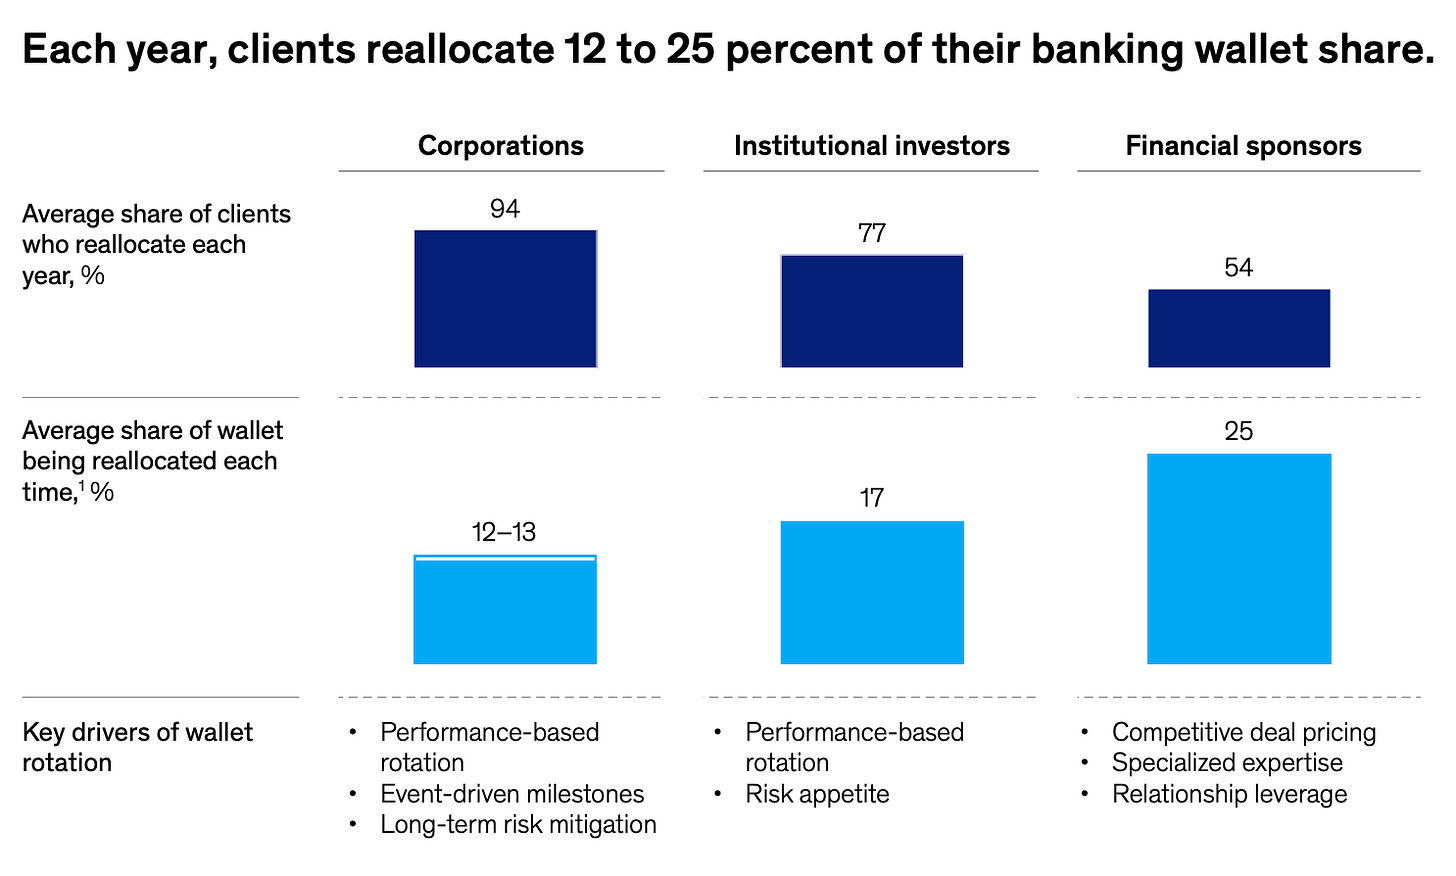
The numbers. Clients reallocate 12–25% of their banking wallet every year. About 94% of corporates reassess allocations annually but move only 12–13% per cycle; 77% of institutional investors reassess and move 17%; 54% of sponsors reassess but move up to 25% when they do. Operational cash management stays put; FX, hedging and trade finance retender every quarter; M&A and event financing drive the occasional structural shift.
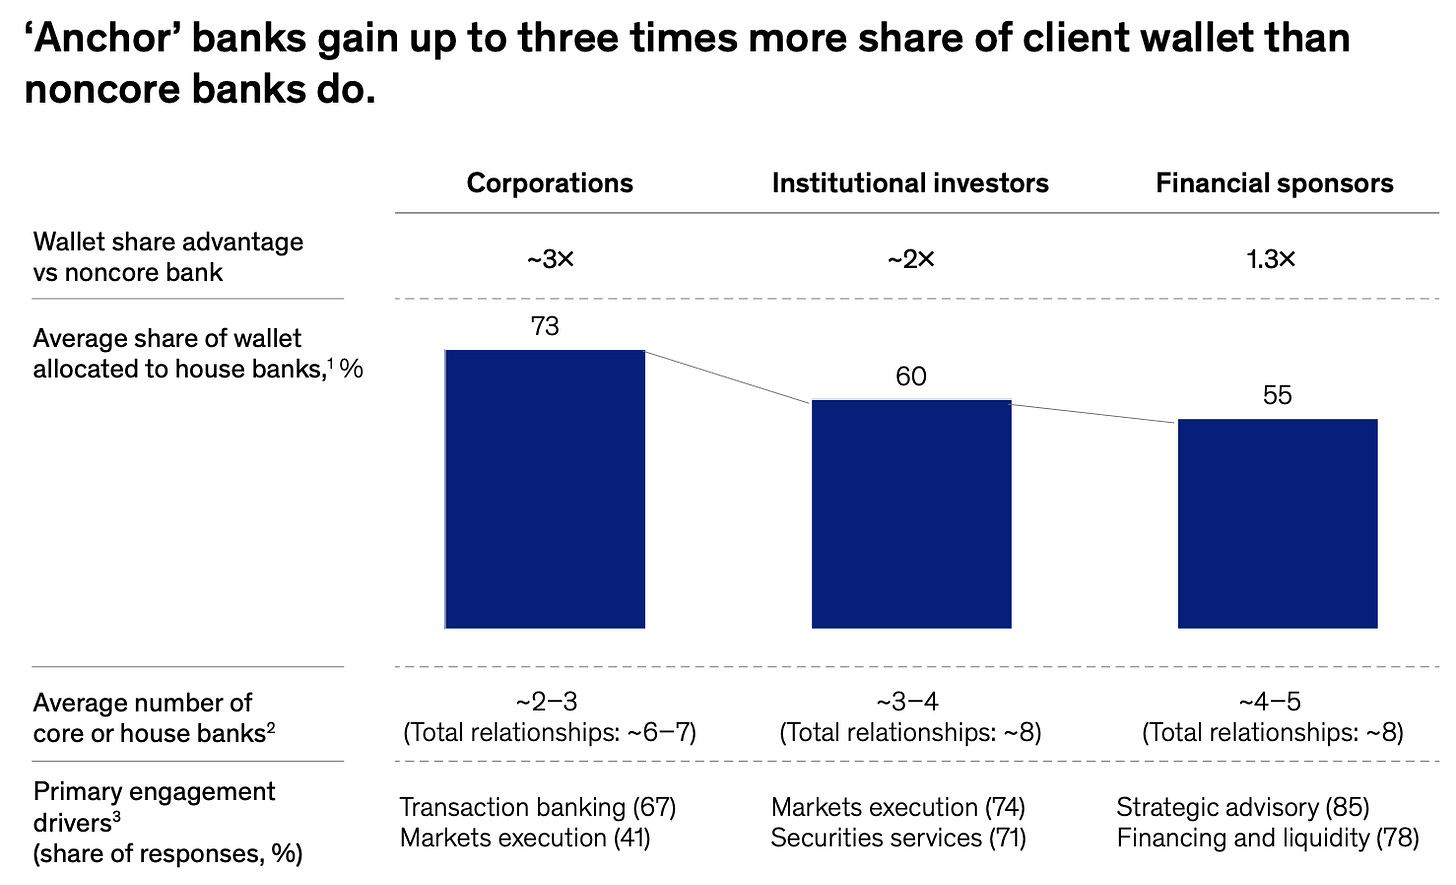
Anchor status. House banks get a disproportionate share. Corporates consolidate about 73% of wallet with their top three providers, institutional investors 60%, sponsors 55%. The advantage over a non-core bank is roughly 3× for corporates, 2× for investors and 1.3× for sponsors. Corporates run two to three house banks out of six or seven relationships; sponsors four to five out of eight. About 92% of sponsors say they drive portfolio-company banking decisions.
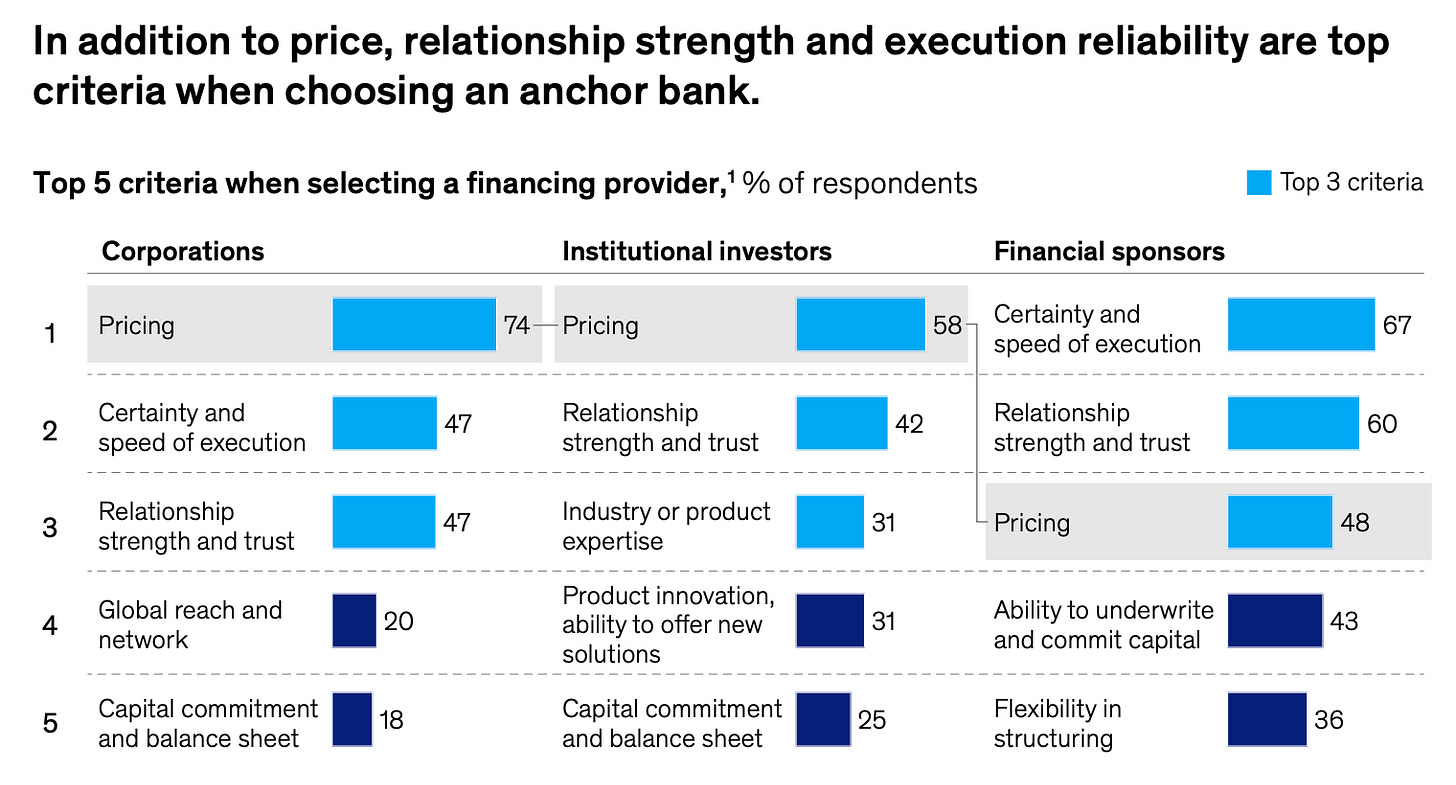
Beyond price. Pricing ranks first for corporates (74% of respondents) and investors (58%), but sponsors put certainty and speed of execution first (67%), relationship strength second (60%) and price third (48%). Corporates rank execution certainty and relationship strength joint second at 47%. Investors list sector expertise (31%) and product innovation (31%) in their top five, with more than 40% of their AUM now in alternatives.
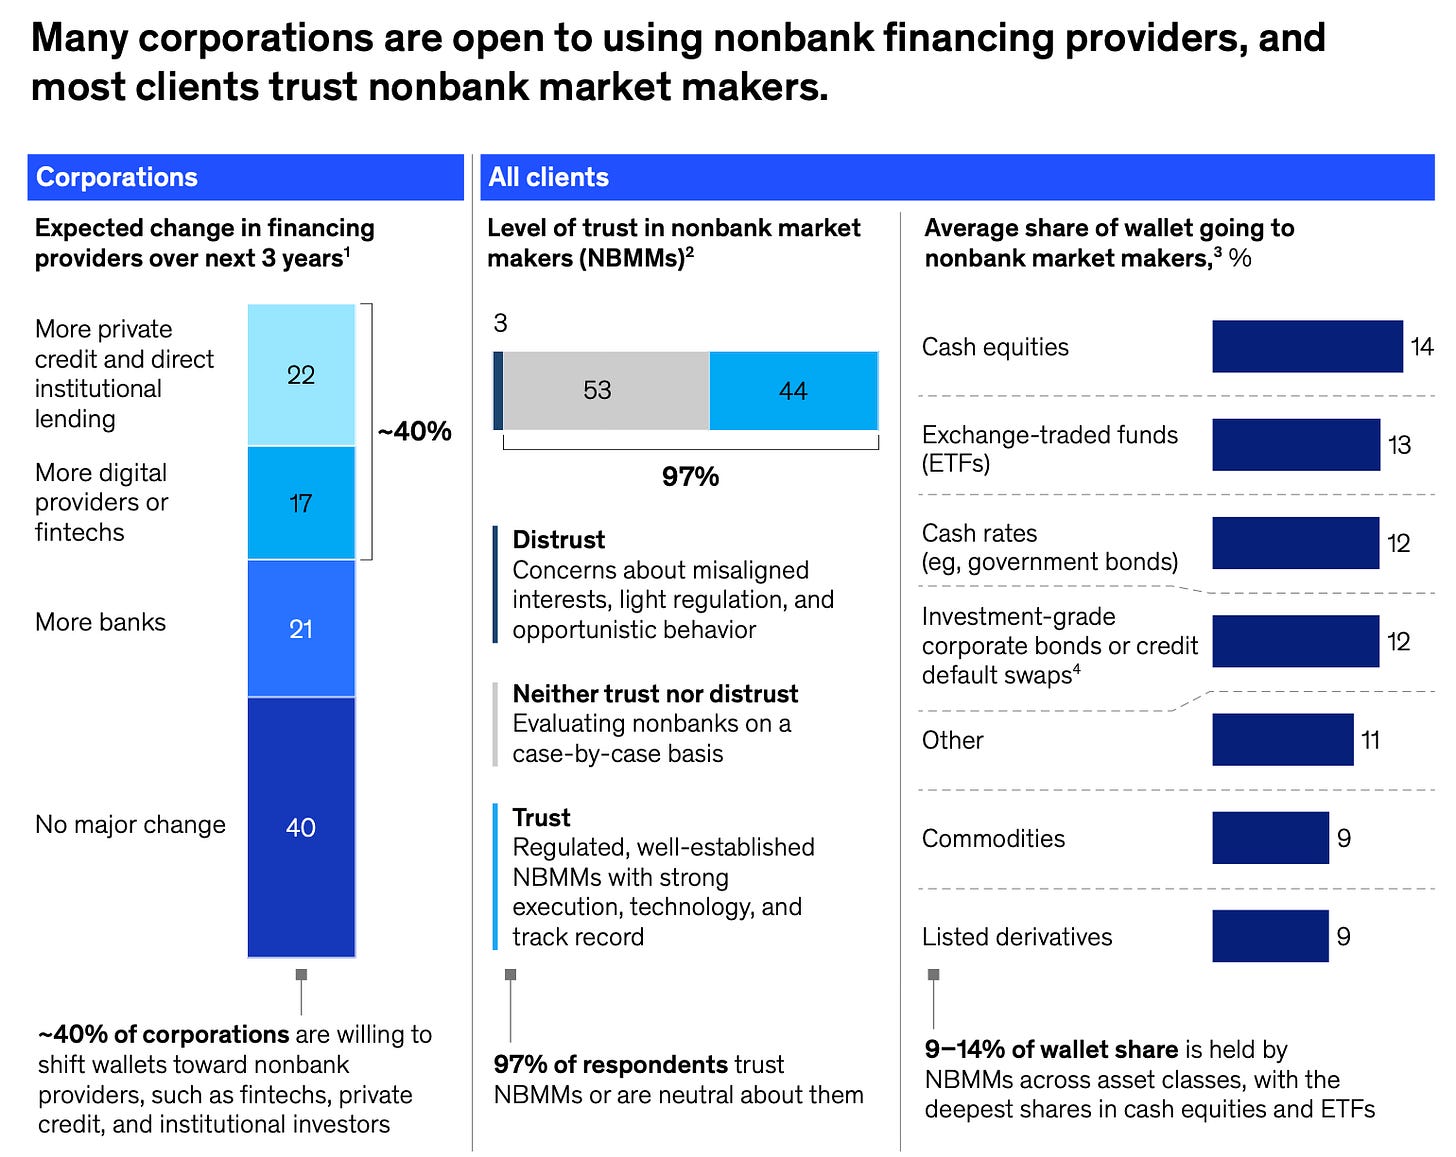
Nonbank competition. About 40% of corporates expect to shift financing toward nonbanks over the next three years: 22% to private credit and direct lending, 17% to fintechs. 67% of sponsors already use direct lenders and private credit, mainly for NAV facilities. Nonbank market makers hold 9–14% of wallet by asset class, deepest in cash equities (14%) and ETFs (13%); only 3% of clients say they distrust them. Fintechs lose on product breadth, enterprise delivery and regulatory robustness; private credit on pricing, covenants and valuation opacity.
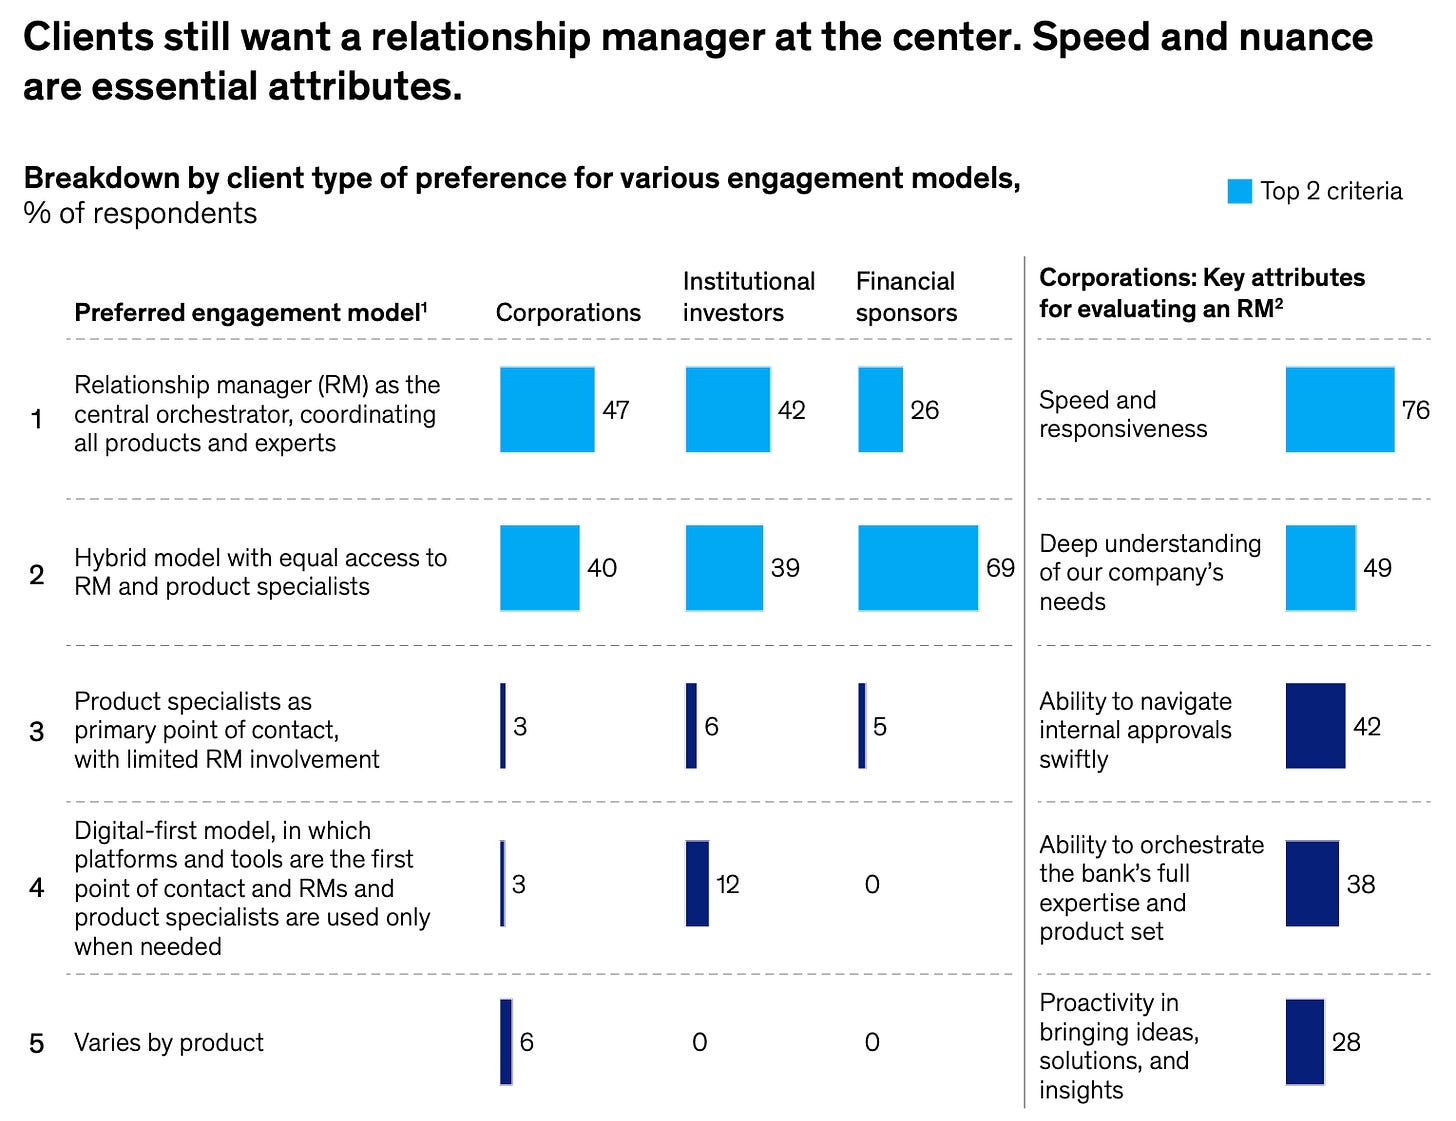
The relationship manager. 47% of corporates and 42% of investors want the RM as central orchestrator; 69% of sponsors want a hybrid model with direct access to specialists. Digital-first coverage polls at 3%, 12% and 0%. Corporates grade an RM on speed and responsiveness (76%) and understanding of the company’s needs (49%). McKinsey’s conclusion: AI tools will commoditise, and the differentiator becomes the RM’s judgement and ability to orchestrate the whole bank.
The read. The contestable slice is the flow business, and that is where the week’s news sits. Stripe is buying Parafin to put credit next to payments for 18,000 platforms; Valley National is paying $340M mostly for Bluevine’s $2.1B of small-business deposits; Citi is settling stablecoin checkout for corporate clients with Coinbase; and five European schemes formed a Madrid entity to connect 130M wallet users. Each one targets the products McKinsey says retender every quarter rather than the sticky operating core. The survey also explains why fintechs still rarely become the house bank: 40% of corporates are open to them, but on breadth, enterprise delivery and regulatory robustness they come up short, which is why the charter and licence applications of the last month (Bastion, Chime, Revolut) matter more than product launches. Watch whether sponsors, the most mobile segment at 25% a year, push portfolio-company banking to nonbanks, and whether the 17% of corporates leaning toward fintechs for financing turns into named mandates in 2027.
The week in six stories
- Stripe agrees to acquire Parafin. Terms were not disclosed and closing is expected in the coming months. Founded in 2020 by Sahill Poddar and Vineet Goel, Parafin lets software platforms offer credit underwritten on platform data and has financed more than 60,000 businesses; Stripe will bring its products to the more than 18,000 platforms built on it, alongside Stripe Capital.
- Kalshi in talks to raise about $1B at a $40B valuation. Reuters reports Sequoia Capital and Wellington Management are in talks to lead, with Tiger Global and Dragoneer also in discussions; the round has not closed. Kalshi raised $1B at $22B in May and reported more than $40B of trading volume in August.
- Valley National Bancorp agrees to acquire Bluevine for $340M. About $255M in cash and 6.3M Valley shares, closing expected in early 2027. Bluevine brings 175,000 active customers and $2.1B of deposits, 99% from non-borrowers; co-founder and CEO Eyal Lifshitz joins Valley as head of small business banking.
- Homeward raises a $120M Series D led by Saluda Grade plus $330M in asset-backed debt. Citi Ventures, Magnetar, Norwest, Adams Street and LiveOak took part. The Austin company, led by CEO Tim Heyl, has worked with 25,000 agents and facilitated more than $4B of residential transactions.
- Jeeves raises a $110M Series C led by CoinFund. AllianceBernstein, Andreessen Horowitz, Coinbase Ventures, CRV, GIC, ParaFi, Vista, Wintermute and Y Combinator joined. Stablecoin activity is about $1.5B of annualised volume; the company launches a stablecoin wallet with payouts to 190 countries and extends its cards from 25 to 35 countries.
- Open USD goes live, issued by Bridge. The stablecoin from Open Standard, the company founded by Coinbase, Mastercard, Shopify, Stripe and Visa, launched on 30 September on Ethereum, Solana, Base and Tempo, with more than $1B in committed launch liquidity and free 1:1 mint and burn; Stripe makes it the default stablecoin on its platform.
Also: BANCOMAT, Bizum, Wero, MBway and Vipps MobilePay create the European Network for Payments, a Madrid entity to connect 130M users in 13 countries; Outmarket AI $34.5M Series B led by SignalFire; erad $22M Series A led by MEVP; Blockchain.com targets a $500M US IPO at a $4–6B valuation; Checkout.com reports $750M annualised net revenue and targets $150M EBITDA; Apple Pay launches in India with Axis Bank; Nubank says it is not pursuing a deal with Monzo; MNT-Halan plans to float 20% of its Egyptian business.
Funds. Seven new vehicles this week: KASZEK (reported ~$600M Fund VII, as former Nubank CFO Guilherme Lago joins as partner), Headline ($400M EU VIII, seed and Series A in Europe, backed by EIF and EBRD), Protego Ventures ($125M Fund I, Israeli defence), DIG Ventures ($120M Fund III, European AI infrastructure, LPs include Horsley Bridge and Sofina), IronWave (€105M first close of its debut fund, €5–15M minority stakes in European B2B software), Eastend Ventures (A$30M debut fund for South Australia, WA and Queensland, anchored by Funds SA) and Freesbee ventures ($15M Fund II, applied AI, $300–500K tickets).
All rounds
Equity
- TXSE Group — third funding round, size undisclosed, takes the Texas Stock Exchange’s capital to $430M, US
- Jeeves — $110M Series C led by CoinFund, stablecoin-native banking platform for global enterprises, US
- Outmarket — $34.5M Series B led by SignalFire, AI for commercial insurance brokers, US
- erad — $22M Series A led by MEVP, Shariah-compliant SME working capital, Saudi Arabia
- Underdogs Group — €20M equity and debt led by Nextalia Ventures, MadTech buy-and-build, Italy
- Complaion — €13.5M co-led by Eurazeo and Italian Founders Fund, ISO certification and compliance for SMEs, Italy
- Blue Fire AI — $9M round as Mizuho’s Asset Management One takes a minority stake, AI for active investment management, Singapore
- Promenaut — $8.9M total funding as HSBC invests and joins as design partner, orchestration of AI agents in banks, US
- Marble — €6.5M Series A led by Smartfin, open-source fraud and AML compliance platform, France
- Stay — R$30M (about $5.8M) Series A led by Citrino, corporate pensions as an employee benefit, Brazil
- Elio Mortgage — $5.1M pre-seed co-led by Motive Partners and Social Leverage, AI-native mortgage brokerage, US
- Walapay — $4.6M seed led by Generative Ventures, cross-border payments infrastructure, US
- Mona — $3.5M led by Sandberg Bernthal Venture Partners, AI capital-matching for small businesses, US
- Humanos — $3.2M seed led by Anthemis, live risk scores for AI agents, Portugal
- FRANK — €2.9M co-led by Armilar and Start Ventures, AI back office for insurance brokers, Portugal
- Computis — €2M pre-seed led by Techshop Capital, AI-run accounting for SMEs, Italy
Debt and credit
VC funds
- Kaszek — reported ~$600M Fund VII nearing close, LatAm, as former Nubank CFO Guilherme Lago joins as partner
- Headline — $400M EU VIII, seed and Series A in Europe with a focus on AI
- Protego Ventures — $125M Fund I final close, early-growth Israeli defence companies
- DIG Ventures — $120M Fund III, pre-seed and seed AI infrastructure in Europe
- IronWave — €105M first close of its debut fund, €5–15M minority stakes in European B2B software, Wendel Growth spin-out
- Freesbee Ventures — $15M Fund II, applied AI from late seed to Series A, $300–500K tickets
Market news
Stablecoins, crypto and tokenisation
- Open Standard launches Open USD, issued by Bridge and backed by Visa, Stripe, Mastercard and Coinbase, live on four chains
- Citi and Coinbase expand their partnership so Citi’s corporate clients can accept stablecoin payments
- CoinMarketCap acquires crypto derivatives data platform Coinglass
- Blockchain.comtargets a $500M US IPO at up to $6B valuation, Bloomberg reports
M&A and capital markets
- Stripe agrees to acquire Parafin to bring embedded small business credit to the 18,000 platforms built on Stripe
- Kalshi in talks to raise about $1B at a $40B valuation, with Sequoia and Wellington set to lead
- Valley National Bancorp agrees to acquire Bluevine for $340M to add $2.1B in digital small business deposits
- Zilch taps banks for a London IPO as soon as 2027
- Nubank says it is not pursuing a deal with Monzo after reports of £8–10bn takeover talks
- Checkout.comsays annualised net revenue hits $750M, up 28%, and targets $150M adjusted EBITDA for 2026
Payments and infrastructure
- BANCOMAT, Bizum, Wero, MB WAY and Vipps MobilePay launch the European Network for Payments, a Madrid entity to connect their wallets
- ECB and Brazil’s central bank study linking TIPS with Pix for instant euro-Brazil payments
- Apple Pay launches in India with Axis Bank as first partner
- Aljazira Bank selects Thunes to power international remittances from Saudi Arabia
Licensing, expansion and people
- Alpaca secures MAS in-principle approval for a Capital Markets Services licence in Singapore
- Trade Republic launches a free current account in Greece
- Revolut appoints Álvaro Alberdi as Head of Business Growth for Southern Europe and LatAm
AI, agents and products
Builders Fintech Funding Index
215 (last full week, week of 21 Sep). 26 equity rounds recorded, against a 12-week average of 12. Median disclosed USD round: index 107. Our round coverage expanded in September 2026, so the Index overstates activity until mid-December. Full reading
Raising now
Space for GPs and solo GPs launching funds. Not paid. If you’re raising and want to be listed, message me on LinkedIn.
- Parallax Ventures — fintech, LatAm. Fund I: +50% IRR, 0.7x DPI. Raising Fund II. [link] · gennari@parallax.vc
- Founder Factor — YC-focused. Just closed investments in YC W26 and is expanding the current vehicle to double down on the batch. [link]
- RedFish Capital Partners — private equity, Italian SMEs in growth and mature phases. 40%+ IRR track record, €200M+ AUM. Raising a new AIF with a soft commitment from the European Investment Fund. redfish.capital · investor.relations@redfish.capital
Performance figures are provided by the managers. Nothing here is investment advice.
Events, next 30 days
- Fintech Meetup Europe — Lisbon, 6–8 Oct
- TOKEN2049 Singapore — Singapore, 7–8 Oct
- Money20/20 USA — Las Vegas, 18–21 Oct
- MERGE Madrid — Madrid, 27–29 Oct
- Hong Kong FinTech Week — Hong Kong, 2–6 Nov
Later:Africa Stablecoin Summit, Johannesburg (12–13 Nov) · Solana Breakpoint, London (15–17 Nov) · Singapore FinTech Festival (18–20 Nov) · Fintech Nerdcon, San Diego (19–20 Nov) · Bitcoin MENA, Abu Dhabi (7–8 Dec) · Abu Dhabi Finance Week (7–10 Dec) · TOKEN2049 Dubai (21–22 Apr 2027) · Money20/20 Asia, Bangkok (27–29 Apr 2027)
Want an event listed or sponsored? DM me.
Previous edition: Weekly update #151